

Revenue & Calc
Set bay capacity, opening days, slot throughput, utilization, seasonal factors, package shares, and realized prices. Revenue rolls these assumptions into annual plans while Calc builds the monthly sales schedule.


The Car Wash Financial Model is an Excel planning template for an attended, four-bay hand wash operating in a leased facility. It turns available bay hours, vehicle throughput, utilization, seasonality, and service-package prices into monthly sales and a 2026–2030 operating forecast.
The workbook combines business-specific operating drivers with integrated financial planning, statements, and decision reports.
Set bay capacity, opening days, slot throughput, utilization, seasonal factors, package shares, and realized prices. Revenue rolls these assumptions into annual plans while Calc builds the monthly sales schedule.
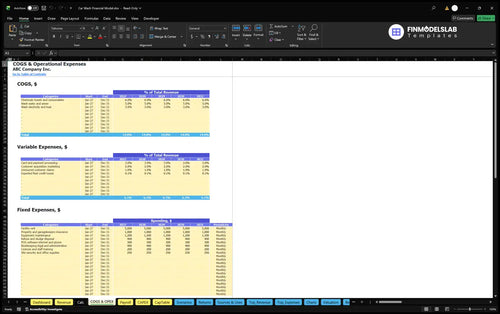
Edit consumables, utilities, transaction costs, marketing, rent, maintenance, staffing levels, and annual pay. These schedules calculate distinct direct, variable, fixed, and personnel expense categories.
Specify equipment and improvements, equity contributions, and optional financing facilities. Dedicated schedules track capital spending, depreciation, ownership funding, borrowing, interest, and repayments.
Review the Income Statement, Cash Flow, Balance Sheet, Dashboard, Summary, Scenarios, Returns, Valuation, Ratios, and supporting charts. Checks flag reconciliation or input issues.
Sales are calculated from one pool of completed vehicle services, then allocated among five priced wash packages.
The volume engine multiplies available bays × scheduled hours × open days × slots per bay-hour × utilization × monthly seasonality. It does not apply a second demand limiter or use payroll staffing as an additional cap on sold vehicles.
The starting inputs are four bays, 10 operating hours per day, 26 open days per month, and two 30-minute service slots per bay-hour. Utilization rises across the five years from 35% in 2026 to 65% in 2030.
The Revenue Forecast connects bay capacity, utilization, service mix, and realized wash prices to projected vehicle counts and annual sales. Its linked monthly calculations incorporate the January-through-December seasonal multipliers and the selected launch timing.
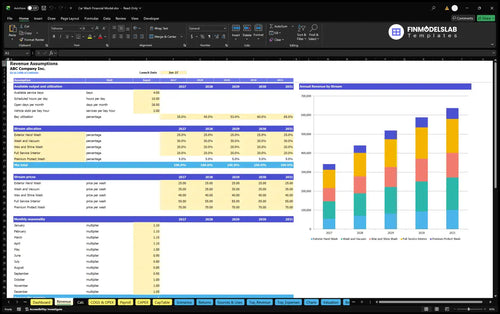
The package mix is 25% Exterior Hand Wash at $25, 30% Wash and Vacuum at $35, 20% Wax and Shine at $40, 20% Full Service Interior at $55, and 5% Premium Protect at $70. These shares sum to 100%, producing a $39.25 weighted price per completed service.
4 bays × 10 hours/day × 26 days × 2 services/bay-hour × 35% utilization = 728 washes; 728 washes × $39.25 = $28,574 revenue.
Monthly seasonal multipliers range from 0.80 in July to 1.15 in March and sum to 12.00 for the year. In the stated 2026 case, that produces 8,736 completed services and $342,888 in annual revenue before any change to the package mix.
Direct wash costs, revenue-based variable expenses, monthly overhead, and fixed-base-pay staffing are modeled as separate expense pools.
COGS assumptions total 14% of revenue: chemicals and consumables at 6%, wash water and sewer at 5%, and electricity and heat at 3%. Variable operating expenses add 6.1% of revenue across processing, customer acquisition, uninsured claims, and expected fleet-credit losses.
Fixed overhead includes facility rent, insurance, equipment maintenance, waste disposal, software, administration, training, and site security. The illustrative facility rent input is $5,000 per month; total fixed expenses are $105,000 in each forecast year.
The COGS and Operating Expenses forecast organizes percentage-based direct and variable costs separately from monthly fixed expenses. Use it to test whether higher wash volumes provide enough contribution to cover rent, maintenance, and other site operating costs.
| Expense category | 2026 | 2030 |
|---|---|---|
| COGS | $48,004 | $89,151 |
| Variable expenses | $20,916 | $38,844 |
| Fixed expenses | $105,000 | $105,000 |
| Payroll | $217,000 | $289,000 |
Category values are rounded; personnel expenses are not duplicated in other expense groups.
The Payroll Forecast plans attendant staffing and site-manager pay by role. The selected case increases average wash-attendant staffing from 4.5 to 6.5 full-time equivalents, keeps one site manager, and includes fixed annual base salaries of $36,000 and $55,000 per FTE, respectively.
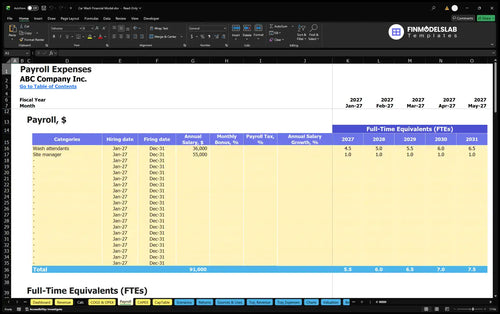
Payroll is $217,000 in 2026 and $289,000 in 2030. These fixed base salaries are counted once through Payroll, outside COGS and other operating categories; employer taxes, benefits, and personal taxes are excluded from the specific illustrative assumptions.
Startup equipment, preopening outlays, working capital, and owner contributions are planned separately from recurring wash operations.
The case specifies $90,000 for pumps and wash equipment, $65,000 for water reclaim and treatment, $120,000 for drainage and bay improvements, and $15,000 for vacuums and interior equipment. These four assets total $290,000, excluding other equipment, durable signage, and cash setup items.
The Capital Expenditure Plan schedules equipment and site improvements, separates depreciable and non-depreciable spending, and connects asset purchases to the workbook’s financial statements. Changing a wash-bay investment affects capital requirements rather than automatically reducing the operating EBITDA shown in the example.
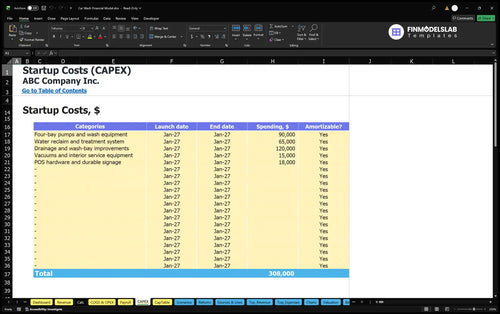
Additional opening cash items include deposits, initial permits, branding, preopening pay, and professional setup. Working-capital controls assume two accounts-receivable days, 13 accounts-payable days, and nine inventory days, which inform receivables, supplier timing, and inventory rather than vehicle-demand assumptions.
The Sources and Uses of Funds report reconciles projected sources of money with operating payments, investments, financing movements, and retained cash. It helps examine where opening owner contributions and any separately modeled borrowings are allocated over selected forecast periods.
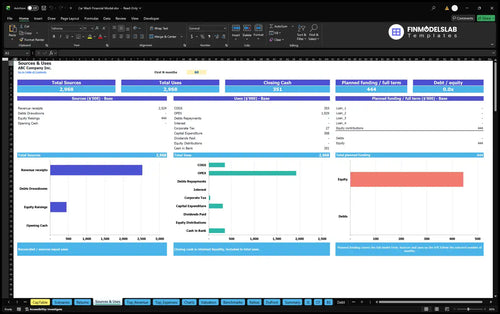
Illustrative initial owner funding is $443,546, based on opening assets, other setup cash, physical working capital, and a three-month recurring-cost reserve. No new financing is assumed in this example, although optional loan structures can be entered through the workbook’s Debt Controls.
The selected case estimates annual sales, operating expenses, and EBITDA for 2026 through 2030 in nominal U.S. dollars.
| Year | Revenue | Operating expenses | EBITDA |
|---|---|---|---|
| 2026 | $342,888 | $390,920 | -$48,032 |
| 2027 | $440,856 | $428,612 | $12,244 |
| 2028 | $519,230 | $462,365 | $56,865 |
| 2029 | $587,808 | $494,149 | $93,659 |
| 2030 | $636,792 | $521,995 | $114,797 |
Figures are illustrative planning outputs rounded to whole dollars; individual displayed differences may reflect rounding.
The projection moves from a $48,032 EBITDA loss in 2026 to $12,244 positive EBITDA in 2027, reaching $114,797 in 2030. That progression reflects higher bay utilization and sales against a comparatively stable fixed-overhead assumption, alongside rising attendant payroll and revenue-linked expenses.
EBITDA measures operating earnings before depreciation, interest, and tax; it is not net profit or free cash flow. The Income Statement, Balance Sheet, and Cash Flow schedules serve different purposes, and no specific net earnings or cash-surplus result is established by this case brief.
The Cash Flow Forecast tracks monthly operating receipts and payments, capital outlays, owner funding, optional borrowing, and debt service. This separate liquidity view is needed to examine cash timing because stronger EBITDA alone does not establish whether opening reserves or future cash balances are adequate.
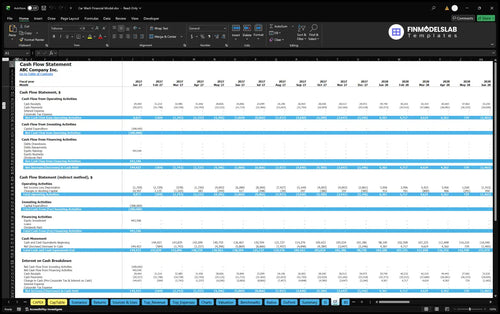
The workbook provides separate operating, liquidity, investment-return, and scenario tools rather than equating positive EBITDA with recovered capital.
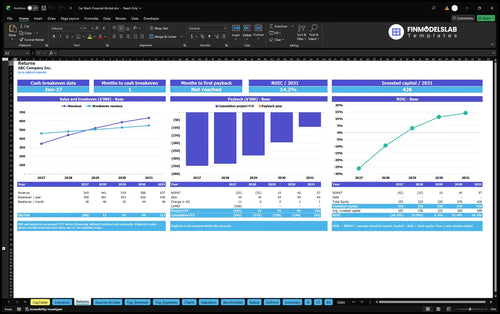
Sales break-even tests the revenue needed to cover relevant operating costs; cash break-even checks when net cash movement turns positive. Investment payback measures when cumulative project cash flow recovers the investment, while annual ROIC evaluates returns on invested capital.
The Returns analysis combines sales break-even, cumulative project cash flow, investment payback, and annual return on invested capital. Review these as separate measures when deciding whether the bay-utilization plan and equipment investment justify their operating and cash requirements.
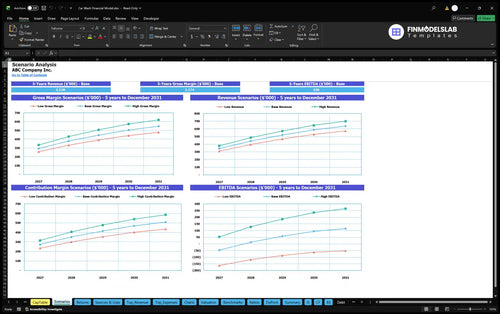
Dashboard Scenario Controls apply Low, Base, and High multipliers to revenue, COGS, variable costs, fixed expenses, and payroll. Compare different utilization, margin, and wage assumptions with financial statements and management charts rather than treating the example as a guaranteed outcome.
The Financial Scenario Analysis compares Low, Base, and High cases for revenue, gross margin, contribution margin, and EBITDA. It shows how changes in selected drivers affect operating performance, without asserting a specific valuation or cash-return result for the sample site.
These answers clarify which assumptions are editable and how to interpret the illustrative financial results.
Yes. Edit bay count, operating hours, open days, slot throughput, and utilization in the Revenue inputs; the monthly vehicle and sales forecast responds.
Yes. Each of the five wash packages has a realized price and a share of the one completed-vehicle service pool.
Yes. Wash attendants and a site manager are planned separately through Payroll, with average FTE and fixed annual base-pay assumptions.
No. The sales, expenses, and EBITDA are illustrative forecasts based on estimated assumptions for a hypothetical suburban Southeast U.S. hand-wash operation.
No. EBITDA excludes investment and financing cash flows; review the Cash Flow Statement and working-capital schedules to evaluate liquidity.
Yes. The Returns report covers sales break-even, cash break-even, project payback, and annual ROIC, but the supplied case does not establish specific values for them.
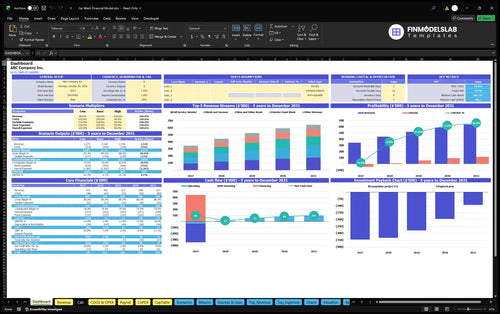
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
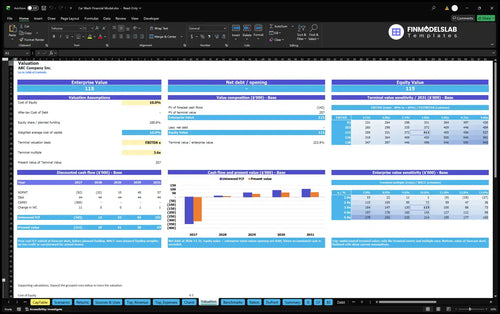
DCF valuation and sensitivity analysis.
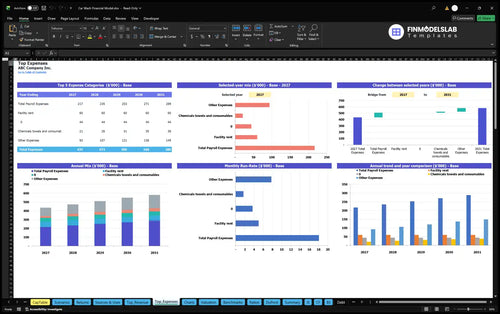
Largest costs and spending trends.
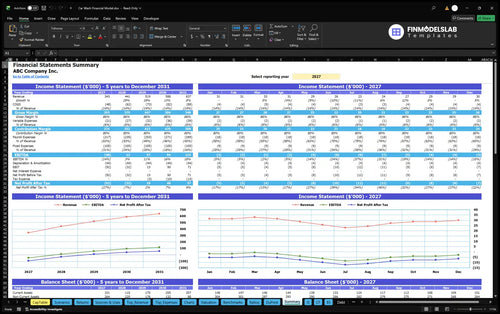
Annual and monthly financial performance.
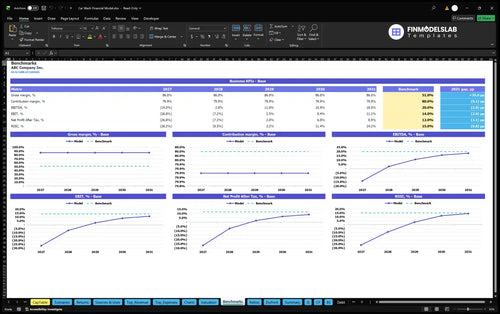
Compare margins and returns to benchmarks.

I used to have statements and charts spread across different files, so every update felt messy. This template pulled everything into one place and cut my prep time for client calls by hours.

Setting up low, base, and high cases was always a hassle. Here, the scenarios are already structured, so I could compare them in minutes and get the numbers ready for a meeting the same day.
Building a car wash model from scratch took too long, especially when I needed a quick answer. This template saved me a full weekend of work and gave me a clean starting point I could use right away.