What Is a Realistic Pay Range for Casino Hotel Owners?
For a manager-run U.S. commercial Casino Hotel resembling the Nevada Gaming Control Board's FY2025 cohort with $36 million to $72 million of annual gaming revenue, a defensible base case is about $3.56 million a year of owner income after modeled tax and reinvestment reserves on $96 million of annual revenue. The model falls to $0 at $66.9 million of revenue and rises to about $9.45 million at $110.4 million. Main constraints are 24/7 payroll, gaming taxes and promotions, hotel overhead, debt service, and reinvestment. This is not EBITDA, GAAP net income, or guaranteed salary; management is already in payroll, while ownership splits, extraordinary projects, and actual taxes beyond the reserve are excluded. The benchmark is the Nevada Gaming Abstract FY2025, used as a mature commercial casino-hotel proxy rather than a tribal casino, online casino, or mega-Strip resort.
Owner income$3.56MNet margin4%Revenue for target pay$94.9MBusiness difficultyHard
How much can a Casino Hotel owner make?
A mature Casino Hotel can generate several million dollars of owner cash, but the range is wide because it combines casino regulation with hotel fixed costs. In the Nevada Gaming Control Board's FY2025 $36 million-$72 million gaming-revenue cohort, 21 properties averaged $95.94 million of total revenue and a $80.51 million median. They also reported 65% occupancy, a $112.29 average room rate, and a 92.3% gross margin before departmental and G&A expenses. That supports the article's $96 million revenue and 92% gross-margin base case.
“Make” has several meanings. Revenue comes from gaming, rooms, food, beverage, and other departments. Operating profit or EBITDA-like cash flow is after operations but before some financing, depreciation, tax, and capital items; accounting profit can be lower after depreciation and interest. Owner salary pays for work, while distributions reward equity. This calculator treats the owner as non-operating: management is already in labor, and owner income is residual cash after debt service plus modeled tax and reinvestment reserves.
Owner income calculator
Estimate residual owner cash and the revenue needed to support a target draw after operating costs, debt service, and modeled reserves.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Casino yield per room-day
$211 slots + $33 tables
FY2025 Nevada properties in the selected cohort generated about $211.16 of slot revenue and $32.95 of table revenue per available room-day; a small shift in gaming yield moves owner cash faster than most line-item cuts.
2
Occupancy and ADR
65% / $112 ADR
Rooms were 25.2% of cohort revenue. Filling rooms at the right rate also feeds gaming, food, beverage, and loyalty activity.
3
Labor productivity
About 40% of revenue
Reconstructed payroll, payroll taxes, benefits, and officers' pay were roughly two-fifths of cohort revenue, making staffing efficiency a first-order owner-income lever.
4
Gaming tax, comps, and promotion
9.4% tax / 27.4% comps
The cohort's casino department reported gaming taxes and licenses equal to 9.4% of casino revenue, while total contra revenue was 27.4% of gaming revenue. Generosity without measured incremental win can erase distribution capacity.
5
Non-gaming mix
56.6% of revenue
Rooms, food, beverage, and other revenue together exceeded gaming revenue in the selected cohort, but department margins differ sharply; food can drive traffic without contributing much profit.
6
Debt and reinvestment
3.9% interest / 10.1% D&A
Interest and depreciation/amortization in the cohort show why a casino hotel can report positive operating cash yet little accounting profit and why distributions need a capital reserve.
Want to test the casino, hotel, and debt assumptions in a full forecast?
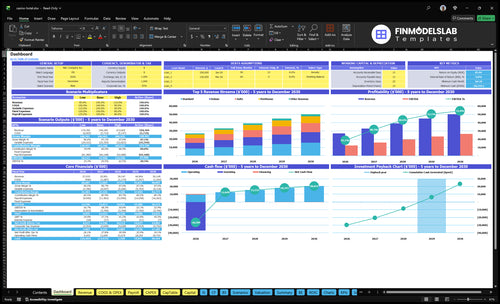
The Casino Hotel Startup Financial Model Template includes a business-specific dashboard for occupancy, ADR, gaming revenue, cash flow, and scenario analysis. The preview is useful for checking whether room yield, casino win, payroll, debt service, and capital assumptions tell the same story before you treat any residual cash as an owner distribution.
What revenue level supports a $3 million annual owner draw?
In the base model, about $94.91 million of annual revenue supports a $3 million annual target owner income after the modeled 24% tax reserve and 20% reinvestment reserve. That threshold sits close to the $95.94 million average total revenue reported by the selected Nevada casino-hotel cohort, which is why the $96 million base case is a useful planning midpoint rather than an aspirational outlier.
Here's the quick math. At $96 million of sales and a 92% gross margin, annual gross profit is $88.32 million. Labor and cash overhead are $36.6 million each, marketing $1.56 million, and debt service $7.2 million, leaving $6.36 million before reserves. The 44% combined reserve is $2.80 million, leaving $3.56 million of owner income. Base operating break-even before owner distributions is about $89.09 million of annual revenue: $81.96 million of operating costs divided by the 92% gross margin.
Base-case cash waterfall
$96.0M annual revenue
$88.32M gross profit at 92%
$81.96M labor, overhead, marketing, and debt service
$3.56M owner income after $2.80M of modeled reserves
Break-even checkpoints
About $89.09M revenue covers base operating cash costs
About $94.91M supports a $3.0M annual target after reserves
Every extra $1M of revenue is not $1M of owner cash
Debt and capital reserves must clear before distributions are safe
Can a Casino Hotel run without the owner working on site?
Yes, and this model assumes it does. At this scale, a Casino Hotel cannot rely on the owner to cover shifts: gaming, surveillance, security, cage, hotel, housekeeping, food and beverage, facilities, finance, and compliance run around the clock. The BLS profile for gambling services workers notes that casino work commonly includes nights, weekends, and holidays, while BLS lodging-manager data describes full-time management and on-call coverage in round-the-clock lodging facilities.
The calculator's $3.05 million monthly labor cost already includes professional management and officers, so the owner has no salary inside labor. If an owner serves as president, GM, CFO, or another executive, pay a market salary through payroll and treat additional distributions as equity income. Otherwise “free labor” is counted again as profit. A new $300,000 owner salary would reduce residual distributions by roughly $300,000 before payroll taxes and benefits unless it replaces a budgeted executive.
Manager-run assumption
Owner is not scheduled into casino or hotel operations
Professional management is included in labor cost
Owner income is residual cash after reserves
Passive distributions depend on covenants and liquidity, not just profit
If the owner works full-time
Assign a real salary to the job performed
Add payroll tax and benefits where applicable
Remove any replaced manager cost before claiming savings
Keep salary separate from distributions in board and tax records
Key Takeaways
A researched base case supports about $3.56M of annual owner cash on $96M of revenue after modeled reserves.
Base operating break-even is about $89.09M of annual revenue; a $3M target draw needs about $94.91M.
Gaming yield, labor, rooms, comps and taxes, non-gaming mix, and debt/reinvestment explain most owner-income variation.
Owner salary pays for work; distributions pay equity. Do not count the same dollars twice.
How do low, base, and high cases change Casino Hotel owner income?
The modeled owner-income range runs from $0 in the downside case to $9.45 million in the high case, after each scenario's tax and reinvestment reserves. The spread reflects uneven local demand: the American Gaming Association's State of the States 2026 reported $78.62 billion of U.S. commercial gaming revenue in 2025 with materially different state results. Stress-test local gaming and hotel demand rather than applying one national growth rate.
Owner income scenarios
Low, base, and high cases keep financing constant while changing demand, gross margin, staffing, overhead, marketing, and reinvestment needs.
Casino Hotel low, base, and high owner-income scenarios after modeled reserves.
Planning dimension
Low CaseDownside
Base CasePlanning
High CaseUpside
Launch modelOperating path
Downside operating case at $66.9M annual revenue with weaker casino and room demand; existing fixed cost base remains heavy.
Stabilized manager-run property at $96M annual revenue, close to the selected Nevada cohort average.
Strong-yield property at $110.4M annual revenue with more payroll, overhead, and marketing to support volume.
$8M monthly revenue; 92% gross margin; approximately 65% occupancy and cohort-like revenue mix.
$9.2M monthly revenue; 93% gross margin; stronger gaming yield and room demand with incremental service capacity.
Cost driversMonthly cash load
$2.55M labor
$2.8M overhead
$90K marketing
$600K debt
24% tax + 25% reinvestment reserve
$3.05M labor
$3.05M overhead
$130K marketing
$600K debt
24% tax + 20% reinvestment reserve
$3.2M labor
$3.2M overhead
$150K marketing
$600K debt
24% tax + 20% reinvestment reserve
Owner income rangeAfter modeled tax and reinvestment reserves
$0
Operating costs exceed gross profit, so the model permits no owner distribution.
$3,561,600
Base residual owner cash after $2.80M of annual modeled reserves.
$9,448,320
Higher demand absorbs added staffing and overhead, leaving substantially more residual cash.
Best fitDecision use
Use for lender and liquidity stress testing when occupancy, gaming yield, or food and beverage traffic miss plan.
Use for annual budgeting, target-pay planning, staffing, and reserve policy at a stabilized regional casino hotel.
Use for upside testing only when the property can support more volume without sacrificing service, compliance, or maintenance.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Why can accounting profit and owner cash tell different stories?
An asset-heavy Casino Hotel can produce operating cash while reporting weak accounting profit. In the selected FY2025 Nevada cohort, depreciation and amortization were about 10.1% of revenue, interest expense was 3.9%, and the group reported a 3.2% pre-federal-tax loss despite positive departmental income. The calculator omits noncash depreciation but includes debt service and a reinvestment reserve, so it is a cash-distribution bridge, not a full P&L.
Taxes create another gap. The 24% tax reserve is a planning holdback, not a forecast. The IRS 2026 rate schedule reaches a 37% top individual marginal rate, while entity structure, state taxes, deductions, basis, and ownership can change the actual bill. Financing can be restrictive too: 13 CFR 120.110 lists businesses deriving more than one-third of gross annual revenue from legal gambling activities as ineligible for SBA business loans, so owners should not assume ordinary small-business government-guaranteed financing is available.
What the P&L can show
Revenue by gaming, rooms, F&B, and other departments
Departmental profit and G&A expense
Depreciation, amortization, and interest
Accounting income before or after tax
What must clear before a draw
Payroll, gaming tax, utilities, security, and vendor payments
Principal and interest due under financing agreements
Tax reserve, cage and working-capital liquidity, and covenant tests
Maintenance and capital reserve for rooms, gaming floor, and building systems
Which six income drivers matter most in a Casino Hotel?
The six strongest owner-income drivers are casino yield, room occupancy and ADR, labor productivity, gaming taxes and promotions, non-gaming mix, and capital structure. The Nevada Gaming Abstract's detailed casino-hotel statements show why: gaming and rooms lead revenue, payroll is a major cash cost, taxes and comps absorb casino win, and depreciation plus interest reveal a heavy capital base. Track them as one system.
1. Casino yield per room-day and gaming mix
Measure gaming win against the property's occupied-room engine
Gaming is the first lever because one more dollar of casino win generally carries more owner-income potential than one more dollar of low-margin food sales, provided it is not bought with excessive comps. In the FY2025 Nevada cohort used here, the reported per-room-per-day statistics were about $211.16 of slot revenue and $32.95 of table revenue. With roughly 900 available rooms in an average property, a $10 improvement in combined gaming revenue per available room-day can represent about $3.3 million of additional annual gaming revenue before related taxes, comps, labor, and marketing.
Do not equate more machines with more profit. Track win per unit, theoretical versus actual hold, occupied-room gaming conversion, player frequency, and profit after incentives. A high-volume segment consuming free rooms, food, entertainment, and credits can add far less owner cash than headline gaming revenue suggests.
Track yield, not just casino volume
Review gaming economics by segment and daypart so promotional spend is tied to incremental contribution.
Slot win per unit and per available room-day
Table drop, hold, and win by pit
Gaming revenue per active loyalty customer
Net contribution after gaming tax and comps
2. Room occupancy, ADR, and casino-hotel cross-spend
Use rooms as both a profit center and a demand feeder
Rooms represented 25.2% of total revenue in the selected Nevada FY2025 cohort, with 65% occupancy and a $112.29 average room rate. Those figures are property-specific rather than a national hotel target, but they fit the modeled scale. What matters is whether the casino hotel can hold rate without losing profitable gaming demand.
For roughly 900 rooms, moving occupancy from 65% to 70% at a $112 ADR adds about 16,400 occupied room nights and roughly $1.84 million of annual room revenue before housekeeping, commissions, utilities, and comps. The larger upside can be casino and F&B spend from those additional guests. Conversely, discounting rooms too deeply may fill the hotel while diluting total-property yield.
Track total revenue per occupied room
Pair hotel metrics with casino and non-gaming spend so revenue management optimizes the whole property.
Occupancy, ADR, and RevPAR
Comped versus cash-paid room nights
Gaming win per occupied room
Total guest spend by segment and channel
3. Labor productivity across 24/7 departments
Protect service and compliance while removing idle labor hours
Labor is hard to flex because casino, hotel, surveillance, security, cage, facilities, and guest-service functions need continuous coverage. Reconstructing payroll, taxes, benefits, officers, and employee lines in the selected Nevada cohort puts labor near 40% of revenue, with about 718 employees per property. Nationally, BLS reported a $35,630 median annual wage for gambling services workers in May 2024 and $85,580 for gambling managers; a full property also employs lodging, food-service, technical, finance, and executive staff.
At the $96 million base case, every one percentage point of revenue spent on labor equals $960,000 a year. Cutting a point of labor without hurting casino yield or hotel service can add close to that amount to pre-reserve profit; cutting coverage that causes slower table openings, dirty rooms, regulatory failures, or lower guest retention can destroy more value than it saves.
Schedule to demand by department
Use revenue-per-labor-hour and service measures together; a pure payroll percentage can encourage false savings.
Labor cost as percent of property revenue
Revenue per paid hour by department
Rooms cleaned per housekeeping hour
Open gaming positions versus profitable demand
4. Gaming taxes, comps, loyalty, and customer acquisition
Judge promotions on incremental contribution after tax
Gaming taxes and promotional reinvestment can turn headline win into much less distributable cash. In the modeled Nevada cohort, gaming taxes and licenses were 9.4% of casino department revenue, and total contra revenue was 27.43% of gaming revenue. The exact tax burden depends on jurisdiction; the American Gaming Association State of Play map summarizes state-by-state commercial gaming requirements, which is why the article does not apply one Nevada tax rate nationwide.
The base case budgets $1.56 million a year of paid advertising, about 1.6% of revenue, while comps and gaming taxes remain embedded in property economics. If a loyalty offer creates $1 million of gaming win but consumes $300,000 of comps, $100,000 of gaming tax, and $150,000 of service cost, contribution is about $450,000 before shared overhead, not $1 million.
Track reinvestment by customer value tier
Comp rooms, free play, food credits, hosts, and paid media should be evaluated against incremental net contribution.
Promotional reinvestment as percent of theoretical win
Gaming tax and license cost per gaming dollar
Acquisition cost by channel and loyalty tier
Repeat trip frequency and dormant-player reactivation
5. Non-gaming revenue mix and departmental margin
Grow the departments that add contribution, not just traffic
In the selected cohort, gaming was 43.4% of revenue; rooms, food, beverage, and other departments supplied the remaining 56.6%. The hotel can attract overnight guests and amenities can extend stays, but revenue mix is not profit mix. The FY2025 Nevada detail showed food department gross margin of 65.8% but departmental income of only 2.4%, while beverage departmental income was 50.0% and rooms departmental income was 53.4% in the same cohort.
A restaurant may support gaming and hotel demand even with a thin standalone P&L, but its subsidy should be visible. If food revenue rises $1 million at a 2.4% department contribution, direct department profit is only about $24,000 before shared G&A. The same growth in a stronger-margin department can create far more owner cash.
Run departmental contribution statements
Measure each outlet both on standalone profit and on the gaming or room demand it supports.
Departmental income by rooms, food, beverage, and other
Spend per occupied room and per gaming visit
Outlet labor and cost of sales
Incremental casino win tied to events and amenities
6. Debt service, reinvestment reserve, and distribution policy
Separate property cash flow from cash that is safe to distribute
Casino hotels consume capital through room renovations, gaming equipment, surveillance, building systems, technology, and compliance upgrades. In the selected cohort, interest expense was 3.9% of revenue and depreciation plus amortization about 10.1%. The calculator translates that capital intensity into $7.2 million of annual debt service and a 20% base reinvestment reserve on positive profit before reserves.
At base, the property has $6.36 million of annual profit before reserves. The 24% tax reserve takes $1.526 million and the 20% reinvestment reserve takes $1.272 million, leaving $3.562 million for the owner. A lender covenant or a major room renovation could require keeping more cash. Financing options may also be narrower than in ordinary hospitality because federal SBA eligibility rules exclude businesses deriving more than one-third of gross revenue from legal gambling.
Approve distributions only after a cash test
Use a board-level distribution policy that checks debt, liquidity, taxes, and capital needs before sending cash to owners.
Debt-service coverage and covenant headroom
Minimum operating and cage liquidity
Tax reserve balance versus estimated liability
Rolling 12- to 24-month maintenance capital plan
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Casino Hotel Bundle
Choosing a selection results in a full page refresh.