Where Does Owner Income Come From in a Casino Resort?
Casino Resort Bundle
For a privately controlled, manager-run regional Casino Resort in the United States, a full-equity owner can realistically see $0 of safe distribution in a weak year, about $1.7 million of annual owner income in a stabilized base case, and about $5.1 million in a strong case. This article models roughly a 300-400-room regional property rather than a Las Vegas Strip mega-resort: the base case uses $38.4 million of annual revenue, an 83% gross margin after non-labor direct costs, $13.2 million of payroll, $12.6 million of fixed overhead, $1.08 million of marketing, $2.16 million of principal-and-interest debt service, then a 22% tax reserve and 18% reinvestment reserve. The Nevada Gaming Control Board FY2025 Gaming Abstract anchors that scale: casinos with rooms and $12 million-$36 million of gaming revenue averaged $36.95 million of total revenue, but the cohort collectively lost money before federal tax. The $1.7 million base case therefore assumes a materially better operator. It excludes partner splits, extraordinary renovation capex, and any personal tax bill above the modeled reserve.
Owner income$1.7MNet margin4%Revenue for target pay$38.6MBusiness difficultyHard
Owner income calculator
Stress-test owner take-home after direct margin, payroll, resort overhead, marketing, debt service, and reserves.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Gaming floor yield
$879/sq. ft.
The FY2025 Nevada comparison band reported about $879 of annual gaming revenue per gaming-floor square foot; a 10% lift on a 26,000-square-foot floor can move more than $2 million of revenue before added variable costs.
2
Occupancy and ADR
52.5% / $111.80
The same regional cohort averaged 52.5% hotel occupancy and a $111.80 room rate, leaving meaningful upside for a property that can fill weekday rooms without over-discounting.
3
Payroll productivity
34.4% base
Base payroll is $13.2 million, or 34.4% of revenue. One percentage point of annual revenue is $384,000, so scheduling discipline quickly reaches owner cash.
4
Comps and acquisition
20.24% comp ratio
The Nevada cohort's complimentary contra revenue equaled 20.24% of gaming revenue, so offer design, reinvestment, and guest acquisition must create profitable repeat play rather than expensive traffic.
5
Fixed cost floor
$1.05M/mo
Utilities, occupancy, insurance, surveillance, maintenance, compliance, and administration keep running when rooms or tables are quiet; that is why a small revenue miss can erase distributions.
6
Debt and reserves
40% held back
The base model reserves 40% of positive pre-reserve profit for taxes and reinvestment after paying debt service, converting accounting profit into a much smaller amount that is safe to distribute.
Want to test the resort assumptions in a full forecast?
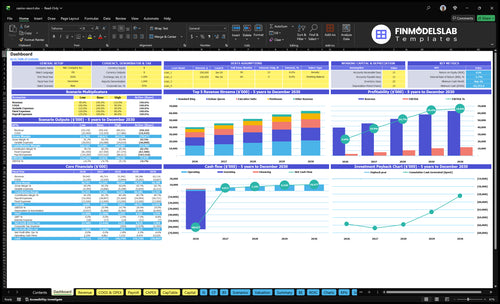
The Casino Resort Five-Year Financial Model Template provides a business-specific dashboard for testing room occupancy, ADR, gaming revenue, food and beverage, payroll, capex, cash runway, and scenario changes together. The screenshot is useful for checking whether a strong owner-income result is supported by the balance sheet and cash flow, not just by a profitable month.
How much revenue does a Casino Resort need before the owner can take cash?
In the base model, the resort needs about $35.0 million of annual revenue just to cover the modeled direct margin and monthly operating-cost stack before owner reserves or target pay. To support the $1.8 million annual target owner take-home after a 22% tax reserve and 18% reinvestment reserve, the calculator raises that threshold to $38.6 million. This sits close to the FY2025 Nevada regional comparison: the Gaming Abstract's $12 million-$36 million gaming-revenue band reported $36.95 million of average total revenue and a $31.13 million median, but also a collective 10.9% loss before federal income taxes. Revenue alone is not enough; the cost structure has to work.
The calculator's 83% base gross margin is lower than the cohort's reported 90.2% accounting gross margin because this tool keeps payroll separate and puts non-labor direct costs above the line. Food and beverage cost of sales, gaming taxes, commissions, processing, and other variable guest costs sit in gross margin; payroll does not. Nevada's current nonrestricted gaming fee schedule reaches 6.75% on monthly gross gaming revenue above $134,000, before device and table fees and other taxes.
Base break-even math
$3.2M monthly revenue
83% gross margin = $2.656M gross profit
$2.420M monthly operating costs
$236K profit before reserves
$141.6K monthly owner income after reserves
What this estimate hides
Jackpot and table-game hold volatility
Partner or minority-owner distribution rights
Major room-tower or casino-floor renovations
Working-capital swings around events and holidays
Any tax liability above the planning reserve
Can a Casino Resort run without the owner?
Yes, and at this scale it generally should be manager-run; the owner should not be treated as the free general manager, surveillance director, hotel manager, or finance department. The base case includes hired management inside the $1.1 million monthly payroll and treats owner income as residual cash after operating costs and reserves. As a labor benchmark, the BLS reported a $85,580 median annual wage for gambling managers in May 2024, while a resort also needs lodging, food and beverage, security, maintenance, finance, compliance, and marketing leadership.
Salary pays for labor; distributions pay for ownership. If the owner actively works as an officer, compensation should be separately justified; the IRS guidance on paying yourself explains that owner-payment rules depend on entity form. The calculator excludes owner salary from labor cost so the same dollars are not counted twice. An active owner can allocate the residual between supportable compensation and distributions with tax advisers; a passive owner generally looks to distributions.
Manager-run economics
Payroll includes hired operating leadership
Owner cash is not a labor-cost shortcut
Department heads protect controls and compliance
Performance incentives can follow EBITDA and guest KPIs
Owner role choices
Passive owner: distributions only
Executive owner: market-based compensation plus distributions
Do not call unpaid owner labor profit
Do not distribute cash needed for debt or capex
How do occupancy, ADR, and gaming win change take-home?
They move owner income through different channels, and the best properties make the channels reinforce each other. The Nevada FY2025 comparison band averaged 52.5% occupancy and a $111.80 average room rate, while a stronger regional resort can run much higher: Monarch's 2025 Atlantis results reported 82.6% occupancy and a $164.61 ADR, and Monarch Black Hawk reported 80.1% occupancy with a $223.36 ADR. Those are adjacent public-company comparables, not promises for a new independent property.
Occupied rooms feed gaming, food, beverage, spa, and events. At 350 rooms and a $135 ADR, every five occupancy points are roughly $862,000 of annual room revenue before room-specific costs. Gaming hold adds another volatility layer. At a large Strip comparable, MGM's 2025 Las Vegas Strip results reported slot win of 9.4% of handle and table-game win of 25.2% of drop. The rates are not transferable, but they show why handle, drop, mix, and hold must be tracked separately from visits.
Hotel levers
Occupancy by weekday and weekend
ADR after discounts and comps
RevPAR by segment
Room guests converted to gaming and dining
Gaming levers
Slot handle and win per unit
Table drop and hold
Gaming revenue per square foot
Comp cost per profitable repeat guest
What has to be paid before a Casino Resort distribution is safe?
A distribution is only safe after direct costs, payroll, property overhead, marketing, scheduled debt service, regulatory obligations, taxes, and a realistic reinvestment reserve are funded. Nevada illustrates why compliance is not a minor line item: the state's nonrestricted gaming application process sits alongside ongoing tax, licensing, reporting, and internal-control requirements. In the FY2025 comparison cohort, advertising and promotion equaled 2.3% of total revenue, interest expense 4.8%, energy 2.1%, utilities 1.3%, and rent of premises 12.7%. A property can show positive departmental income and still have little or no distributable cash after the full stack.
The base calculator converts $236,000 of monthly profit before reserves into $141,600 of owner income by holding back $94,400. Revenue, accounting profit, EBITDA, owner salary, owner draw, and safe cash are not interchangeable. EBITDA ignores principal repayment and recurring capital needs; a draw is merely cash transferred to an owner, not proof the business earned it.
Emergency liquidity for equipment and compliance events
Key Takeaways
The base case produces about $1.7M of annual owner income on $38.4M of revenue after debt service and 40% combined reserves.
A weak $28.8M revenue year produces no owner income because payroll, overhead, and debt do not fall fast enough.
Gaming floor yield, occupancy and ADR, payroll productivity, comps, fixed overhead, and debt plus reserves are the six strongest owner-cash levers.
Treat owner salary as payment for work and distributions as residual ownership cash; never count the same dollars twice.
How do the low, base, and high Casino Resort cases compare?
The scenario spread is wide because casino-resort economics are nonlinear. The low case keeps a large cost floor and produces no distribution; the base case clears it narrowly; the high case adds payroll, marketing, overhead, and debt alongside stronger revenue. That pattern is consistent with Red Rock's 2025 Las Vegas segment data, which reported $1.98 billion of revenue, $545.7 million of payroll and related costs, $102.0 million of gaming taxes, $323.7 million of other segment expenses, and $915.9 million of segment Adjusted EBITDA.
Casino Resort owner-income scenarios
Three reconciled operating cases using the same calculator presets, with higher-case labor and overhead rising alongside revenue.
Low, base, and high Casino Resort planning cases for owner income.
Planning dimension
Low CaseDownside
Base CasePlan
High CaseUpside
Launch modelRevenue and margin posture
$2.4M monthly revenue
80% gross margin
Demand shortfall
$3.2M monthly revenue
83% gross margin
Stabilized regional property
$4.5M monthly revenue
84% gross margin
Strong gaming and room demand
Typical setupManager-run regional resort
$1.00M labor
$1.00M fixed overhead
$70K marketing
$180K debt service
$1.10M labor
$1.05M fixed overhead
$90K marketing
$180K debt service
$1.40M labor
$1.20M fixed overhead
$130K marketing
$200K debt service
Cost driversWhat moves cash fastest
Fixed labor floor
Soft room and gaming demand
35% combined reserves if profitable
Gaming floor yield
Occupancy and ADR
Payroll and fixed overhead
40% combined reserves
More staffing and marketing
Higher maintenance load
50% combined reserves
Strong gaming and room conversion
Owner income rangeAfter tax + reinvestment reserves
$0
$1.70M
$5.10M
Best fitHow to use the case
Use this to test a weak demand year where the property still pays staff, overhead, and debt but owner distributions stop.
Use this as the stabilized planning case for a regional property that outperforms the weak FY2025 cohort without assuming mega-resort economics.
Use this to test strong gaming and room productivity while still funding extra staff, marketing, overhead, debt, and a larger reinvestment reserve.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest Casino Resort income drivers?
Owner income is most sensitive to six linked decisions: how much gaming revenue the floor produces, how efficiently rooms are filled and priced, how payroll scales with demand, how aggressively comps and acquisition spend are controlled, how much fixed cost the property carries, and how much debt plus reinvestment must be funded before distributions. The detailed sections below use the same six drivers and keep the base model's $38.4 million annual revenue and $1.7 million owner-income result as the reference point.
1. Gaming floor yield
Manage win per square foot, not just headcount
The FY2025 Nevada casinos-with-rooms comparison band reported about $879 of annual gaming revenue per gaming-floor square foot, including about $897 for slots. The group's average gaming floor was roughly 25,873 square feet. Here's the quick math: 25,873 square feet multiplied by $879 is about $22.7 million of annual gaming revenue. A 10% improvement in productive yield is therefore about $2.27 million of extra gaming revenue before gaming taxes, promotions, labor reactions, and other variable costs.
The owner should manage profitable handle, drop, hold, machine mix, table utilization, and guest reinvestment rather than raw foot traffic.
Track floor productivity weekly
Separate demand from luck and mix so one favorable hold month does not become a permanent budget assumption.
Slot handle and win per active machine
Table drop, hold, and hours open
Gaming revenue per square foot
Win per loyalty member and trip
2. Hotel occupancy and ADR
Fill the hotel without buying unprofitable rooms
The Nevada comparison band averaged 52.5% occupancy and a $111.80 room rate, while the stronger 2025 Monarch regional resorts ran around 80% occupancy with materially higher ADR. The gap matters because hotel rooms are both a profit center and a customer-acquisition channel for the casino. At 350 rooms and a $135 ADR, a five-point occupancy increase produces about $862,000 of annual room revenue before incremental housekeeping, commissions, amenities, and comps.
The question is whether those guests also generate profitable gaming, food and beverage, and event spend. Discounted rooms can lift occupancy while destroying contribution through comps and weak on-property spend.
Track profitable occupied-room value
Do not optimize occupancy by itself. Measure the whole wallet after acquisition cost and complimentary benefits.
Occupancy by day of week
ADR and RevPAR after discounts
Total resort spend per occupied room
Casino conversion from hotel guests
3. Payroll productivity
Protect service while keeping labor variable
Casino resorts have labor in almost every revenue and control function, so payroll behaves less like a simple percentage and more like a stair-step cost. The base model uses $13.2 million of annual payroll, or 34.4% of revenue, before owner pay. The BLS gambling-services wage data shows a May 2024 median of $35,630 across gambling-services workers and $85,580 for gambling managers, before adding payroll taxes, benefits, overtime, security, hotel, maintenance, food and beverage, and administrative roles.
At $38.4 million of revenue, one percentage point is $384,000. If scheduling, automation, cross-training, or hours of operation remove one full point of labor without damaging revenue or compliance, the base model would retain roughly $230,000 of that amount for the owner after the 40% combined reserve. The danger is cutting too hard and losing gaming availability or guest service.
Schedule against demand, not habit
Use labor hours per occupied room and per gaming revenue unit so payroll reacts before a soft month reaches the cash account.
Payroll as a percent of revenue
Labor hours per occupied room
Casino labor per gaming revenue dollar
Overtime and open-position coverage
4. Comps and customer acquisition
Buy profitable repeat play, not vanity traffic
The Nevada FY2025 cohort reported total complimentary contra revenue equal to 20.24% of gaming revenue, and advertising and promotion equal to 2.3% of total revenue. Marketing cannot be judged only by visits or database size. On $20 million of gaming win, one comp-ratio point is $200,000 of nominal revenue value. The cash cost varies by benefit, but the owner still needs a contribution test.
The base calculator holds paid marketing at $90,000 per month and handles complimentary and directly variable guest costs in gross margin. Keeping those buckets separate prevents a common planning error: hiding customer-acquisition cost in three places and then overstating the owner margin.
Track reinvestment by profitable segment
Measure the incremental win and total resort contribution generated after free play, room comps, food, host cost, and paid media.
Comp value as a percent of theoretical or actual win
Acquisition cost per retained guest
Repeat trips by segment
Incremental contribution after offers
5. Fixed overhead and property cost
Underwrite the cost floor before forecasting upside
The base case carries $1.05 million of monthly fixed overhead before payroll, marketing, debt service, and direct costs. That is not excessive for a regional casino resort when the comparison cohort reported rent of premises at 12.7% of revenue, energy at 2.1%, utilities at 1.3%, real-estate taxes at 1.0%, and other G&A at 13.1%. The mix varies sharply depending on whether the owner controls the real estate, has a master lease, or operates inside a larger development.
Fixed-cost leverage cuts both ways. If base monthly revenue falls from $3.2 million toward $2.4 million while fixed overhead only drops from $1.05 million to $1.00 million, the property crosses into a cash loss and owner income goes to zero. That is why a cheap acquisition with a bad lease can be more dangerous than a higher purchase price with a cleaner cost structure.
Separate true fixed costs from controllable overhead
Build a monthly cost floor that still exists at 50% occupancy and a soft gaming month, then stress it before taking distributions.
Occupancy cost and property taxes
Energy and utilities per open square foot
Maintenance backlog and insurance
G&A cost per revenue dollar
6. Debt service and reinvestment reserves
Convert operating profit into durable owner cash
Debt and reinvestment can erase attractive operating profit. The base case pays $180,000 of principal and interest monthly, then holds back 40% of positive pre-reserve profit. That turns $2.832 million of annual profit before reserves into $1.699 million of modeled owner income while funding recurring property refreshes.
Large operators show the same basic distinction at a different scale. Red Rock reported $2.01 billion of 2025 net revenue and $848.6 million of consolidated Adjusted EBITDA, yet property ownership still sits beside depreciation, interest, development spending, and balance-sheet obligations. For an individual owner, the safest distribution policy is based on cash after debt and planned capital, not on EBITDA alone.
Set a distribution gate
Do not distribute simply because the income statement is positive. Require liquidity, debt coverage, and funded capital plans first.
Debt-service coverage after a downside stress
Months of unrestricted operating cash
Funded room and gaming-floor capex
Owner distributions after tax and reinvestment reserves
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.