What Is the Earning Potential for Electronics Repair Shop Owners?
For an owner-operated U.S. consumer electronics repair storefront, a realistic planning range is roughly $13,000 to $169,000 a year in owner income after modeled tax and reinvestment reserves, with a base case of $83,232 on $720,000 of annual revenue. The base model uses $60,000 of monthly sales, a 72% gross margin after direct non-labor costs, then $20,000 of employee payroll, $8,000 of fixed overhead, $3,000 of marketing, and $2,000 of debt service. The owner works full time as lead technician and manager, so owner labor is not duplicated in payroll. The figure is after a 22% modeled tax reserve and 10% reinvestment reserve, but it is not a guaranteed draw or a substitute for actual taxes, emergency cash, or one-off capital needs.
Owner income$83KNet margin12%Revenue for target pay$722KBusiness difficultyModerate
How much can an electronics repair shop owner make?
The answer changes sharply depending on whether the owner works on the bench or expects passive distributions. This model covers a service-first storefront repairing smartphones, laptops, tablets, game consoles, and similar devices. That scope aligns with the Census definition of NAICS 811210 electronic and precision equipment repair. The base case targets about $83,000 a year after reserves; the low case produces about $13,000 and the high case about $169,000.
Revenue is driven by completed repair jobs, not walk-ins. A useful planning unit is completed paid repairs per open day × average repair ticket. Current national repair-chain pricing shows iPhone screen repairs starting at $79, while device type, model, parts choice, data work, board-level complexity, and warranty policy can move individual tickets much higher. The $130 base average ticket used here is therefore a planning assumption for a mixed consumer-electronics shop, not an industry-wide published average.
Owner income calculator
Adjust repair revenue, margins, staffing, overhead, financing, and reserves to estimate owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
At $60,000 of monthly revenue, the base case produces $43,200 of gross profit. Operating costs total $33,000, leaving $10,200 before reserves. A $2,244 tax reserve and $1,020 reinvestment reserve leave $6,936 monthly, or $83,232 annually, for the owner. Revenue is sales, while accounting profit can include noncash items and classify interest differently. This model's profit before reserves is a planning cash result, not GAAP operating profit or EBITDA. Owner salary means payroll compensation for work performed; an owner draw or distribution is cash withdrawn as an owner. The calculator treats owner take-home as the post-reserve residual, so a non-working owner must add replacement management or lead-technician payroll before calling it passive or safely distributable.
1
Completed repairs per day
18/day base
Throughput determines whether the shop spreads payroll and rent across enough paid jobs to create owner cash.
2
Average repair ticket
$130 base
Service mix, device value, diagnostic charges, and add-on work determine revenue from each completed job.
3
Parts and direct-cost control
72% gross margin
Parts buying, freight, warranty callbacks, payment fees, and write-offs decide how much sales remain before payroll.
4
Technician payroll and owner role
$20K/month
The base case carries employee payroll separately while the owner works as lead technician and shop manager.
5
Customer acquisition efficiency
5% of sales
The model budgets $3,000 monthly for marketing; weak conversion can spend cash without adding completed repairs.
6
Overhead and financing burden
$10K/month
Base fixed overhead plus debt service consumes $10,000 before marketing, taxes, reinvestment, or owner income.
Want to test the repair shop assumptions in a full forecast?
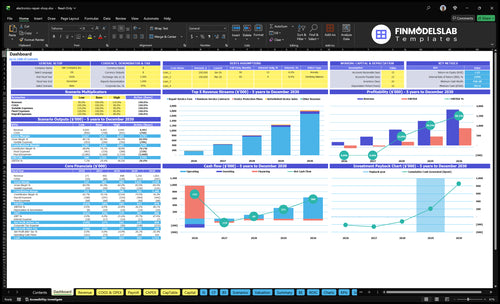
The Electronics Repair Shop Excel Financial Model for Startups provides a business-specific model structure for changing revenue streams, payroll, cost assumptions, capital spending, financing, and scenarios. The dashboard preview is useful for testing whether repair volume, service mix, parts cost, staffing, and funding assumptions tell the same cash-flow story rather than treating owner income as a stand-alone percentage of sales.
What repair volume and ticket size support an $80K owner income?
The base case needs about 18 completed repairs per day across 26 open days at roughly a $130 average ticket to reach $60,000 of monthly revenue. That volume is demanding but plausible for an owner plus multiple technicians if the mix includes quick phone work and longer computer or console jobs. As a capacity reference, a large national repair chain says many iPhone repairs can be completed in 45 minutes or less; that is not a promise for independent shops or for complex laptop, board-level, liquid-damage, or data-recovery work.
Capacity means completed paid jobs after diagnostics, parts availability, approvals, and warranty rework. Losing 12 paid repairs in a month at a $130 ticket removes $1,560 of revenue and about $1,123 of gross profit at the 72% modeled margin.
Base sales math
About 460 completed repairs per month.
About $130 of revenue per completed repair.
Roughly $60,000 monthly and $720,000 annual revenue.
72% gross margin leaves $43,200 per month before employee payroll and overhead.
What this estimate hides
Simple screen and battery work can turn quickly; board repairs and data work can occupy a bench much longer.
Parts stockouts create idle labor even when customer demand is strong.
Free diagnostics may create traffic without revenue unless approval rates are tracked.
Warranty callbacks consume technician time without creating a second sale.
How much payroll can the shop carry before owner pay disappears?
In the base model, employee payroll is capped at $20,000 per month before owner pay, or one-third of revenue. For context, May 2025 BLS national wage data lists computer, automated teller, and office machine repairers at a $24.46 mean hourly wage and $22.99 median hourly wage. That occupation is an adjacent proxy rather than a perfect match for smartphone bench technicians, so local hiring budgets should be checked against actual job postings and required skill levels.
The base case assumes the owner is a productive lead technician and manager. For passive ownership, add replacement payroll. A $6,000 monthly loaded manager or lead-tech cost cuts profit before reserves from $10,200 to $4,200 and lowers modeled annual owner income from $83,232 to about $34,272 under the same reserve percentages.
Owner-operated shop
Owner performs diagnostics, complex repairs, approvals, scheduling, and vendor decisions.
Employee payroll excludes the owner to prevent counting owner compensation twice.
$83,232 base owner income combines the reward for labor and residual ownership profit.
Track owner bench hours separately so the business can be valued on a normalized payroll basis.
Manager-run shop
Add a market-rate lead technician or manager before calling remaining cash passive income.
Require the added payroll to create enough throughput or owner freedom to justify its cost.
A $6,000 monthly replacement role needs roughly $8,333 of additional sales at a 72% gross margin just to restore the same pre-reserve profit.
Do not label a distribution as salary when no labor is being performed.
When does an electronics repair shop really break even?
With the base 72% gross margin and $33,000 of monthly operating costs, the shop's modeled operating break-even is about $45,833 of monthly revenue before owner income and reserves. To support the chosen $7,000 monthly owner-pay target after the 22% tax reserve and 10% reinvestment reserve, the required revenue rises to $60,131 per month. Financing changes that floor directly: the SBA 7(a) program permits uses including working capital, equipment, supplies, and certain debt refinancing, but every dollar of required monthly principal and interest still has to be carried by repair gross profit.
Break-even is also a cash-flow test. Parts can be paid before pickup and warranty callbacks consume labor without new revenue. Local licensing obligations vary by location, as the SBA licensing guidance notes. Taxes are a separate claim on cash: the model's 22% reserve is only a planning bucket, not a universal rate. The IRS estimated-tax guidance explains when owners may need estimated payments.
Two break-even floors
Operating break-even: about $45,833 monthly revenue at the base margin and cost structure.
Owner-pay floor: about $60,131 monthly revenue for a $7,000 monthly target after modeled reserves.
Every extra $1,000 of recurring monthly cost requires about $1,389 of revenue at a 72% gross margin.
Break-even should be tested against realistic paid jobs per day, not a spreadsheet percentage alone.
Cash safe to distribute
Pay parts vendors, employee payroll, rent, utilities, insurance, software, and marketing first.
Pay scheduled debt service and retain enough cash for known warranty rework and equipment needs.
Set aside tax cash separately from operating cash.
Only the residual after these claims should be considered an owner draw or distribution.
Key Takeaways
The base owner-operated model produces $83,232 of annual owner income on $720,000 of annual revenue after modeled reserves.
Owner income is not passive profit when the owner is also the lead technician and manager; replacement payroll can cut distributions sharply.
About $45,833 of monthly revenue covers the base operating cost structure, but roughly $60,131 is needed to support the modeled $7,000 monthly owner-pay target.
Throughput, ticket size, parts margin, payroll discipline, customer acquisition, and financing burden matter more than revenue growth by itself.
What do low, base, and high owner-income scenarios look like?
The scenarios produce $12,792, $83,232, and $168,588 of annual owner income after modeled reserves. The low case keeps minimum rent, marketing, and debt costs despite soft demand; the high case adds labor and overhead as sales rise. Independent repair economics also depend on parts and information access. The FTC continues attention to repair restrictions and right-to-repair issues, so not every device family should be modeled as equally serviceable.
Owner income scenarios
Three internally consistent repair-shop cases using the same calculator assumptions and reserve logic.
Electronics Repair Shop low, base, and high owner-income planning cases.
Planning factor
Low CaseConservative
Base CaseStabilized
High CaseStrong demand
Launch modelMonthly revenue engine
$36,000 monthly revenue
About 11-12 repairs per day at a $120 ticket
$60,000 monthly revenue
About 18 repairs per day at a $130 ticket
$95,000 monthly revenue
About 24 repairs per day at a $150 ticket
Typical setupOwner and staffing model
Owner plus one core technician
Lean storefront and limited parts depth
Working owner plus two technicians and support coverage
Mixed phone, computer, tablet, and console work
Larger technician team and front-desk coverage
More business-account and premium repair work
Cost driversMargin and monthly burden
68% gross margin and $12,000 labor
$11,000 other monthly operating costs
72% gross margin and $20,000 labor
$13,000 other monthly operating costs
74% gross margin and $30,000 labor
$18,000 other monthly operating costs
Owner income rangeAfter modeled tax and reinvestment reserves
$12,792
$83,232
$168,588
Best fitWhen the case is useful
New shop or soft traffic
Narrow service mix and limited referral base
Established neighborhood demand
Working owner with repeatable processes
Dense demand and commercial accounts
Disciplined parts purchasing and larger-team capacity
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers have the biggest effect on owner income?
The six highest-impact levers in this model are repair throughput, average ticket, direct-cost margin, technician payroll and owner role, customer acquisition efficiency, and overhead plus financing burden. They interact: adding marketing is useful only if it creates completed jobs; adding technicians is useful only if demand and parts availability keep them productive; raising ticket prices helps only if approval and repeat behavior remain healthy. Payment economics also belong in direct costs. For example, Square's current U.S. retail pricing lists 2.6% plus $0.15 for in-person card payments on its Free plan, so card mix alone can absorb several percentage points of a repair ticket before payroll begins.
1. Completed repairs per day
Treat paid throughput as the first revenue constraint
The base case assumes about 18 completed paid repairs per open day. Devices waiting for parts, declined estimates, and warranty comebacks consume time without new sales. A national repair chain says many iPhone jobs can be finished in 45 minutes or less, but a mixed independent shop must also absorb slower diagnostics and computer work.
Here's the quick math: two additional completed repairs per day at a $130 average ticket across 26 open days add about $6,760 of monthly revenue. At the 72% base gross margin, that creates about $4,867 of gross profit. If the existing team can absorb the work without more payroll or overhead, the same 32% reserve structure would leave roughly $3,309 more monthly owner income, or about $39,700 a year. If another technician is required, that incremental payroll must come out first.
Track the funnel from intake to paid pickup
Bench utilization is less useful than paid completion because only paid work funds owner income.
Devices checked in per day
Estimate approval rate
Completed paid repairs per technician day
Average days waiting for parts
Warranty comeback hours
2. Average repair ticket and service mix
Raise value per job without pricing away approvals
Public pricing shows some iPhone screen repairs starting at $79, while model-specific jobs can be much higher. The $130 average ticket here is a blended planning assumption across phones, tablets, computers, consoles, converted diagnostics, and limited add-ons after discounts and warranty work.
A $10 increase in realized average ticket across roughly 460 monthly repairs adds about $4,600 of revenue. At a 72% gross margin, that is $3,312 of additional gross profit before any extra operating cost. After the base reserve percentages, it could add about $2,252 per month, or roughly $27,000 per year, to owner income. The sensitivity works in reverse when price discounting, low-value battery work, or poor upsell discipline pulls the average down.
Measure realized ticket, not posted price
Use the amount actually collected after discounts and redo work.
Average collected ticket by device category
Diagnostic-to-repair conversion
Accessory and service add-on dollars per repair
Discount percentage
Gross profit dollars per completed ticket
3. Parts cost, payment fees, and warranty rework
Protect gross margin before worrying about net margin
Gross margin here is revenue left after parts, freight, consumables, payment processing, and warranty allowance; employee payroll is separate. The 72% base margin therefore implies 28% direct non-labor costs. Parts quality, rush freight, failed components, write-offs, and free repeat work can move that percentage quickly.
A three-percentage-point gross-margin improvement on $60,000 of monthly sales adds $1,800 to monthly gross profit. With no change in payroll or overhead, the base reserve settings would leave roughly $1,224 more monthly owner income, or about $14,700 annually. Warranty policy needs equal attention. The FTC warranty guide explains that written coverage involving both repair parts and workmanship can trigger federal warranty-law requirements, so a shop should price the cost of its promise and document terms clearly rather than treating comeback work as invisible labor.
Track margin leakage by repair type
A strong overall percentage can hide one device family that consistently destroys cash.
Parts cost as a percentage of each repair category
Freight and rush-order cost per job
Payment fee percentage
Warranty comeback rate and hours
Inventory write-offs and obsolete parts
4. Technician payroll and the owner's working role
Hire only when the added bench capacity earns its payroll
Headcount can outrun demand quickly. The May 2025 BLS national mean wage of $24.46 an hour for computer, automated teller, and office machine repairers is an adjacent labor anchor; local electronics technicians vary by skill and market. The base model uses $20,000 monthly employee labor cost while the owner remains productive.
If one additional technician costs $4,500 per month on a loaded basis, the shop needs about $6,250 of extra monthly sales at a 72% gross margin merely to cover that payroll before owner reserves. At a $130 ticket, that is about 48 additional completed repairs per month, or almost two extra repairs per open day. Hiring ahead of that demand lowers owner income; waiting too long can increase cycle time, lost approvals, and burnout. The decision should be based on paid backlog and technician productivity, not just a crowded counter.
Normalize owner labor before calling profit passive
Separate the economics of working in the shop from the return on owning it.
Revenue per paid technician hour
Completed jobs per technician day
Loaded payroll as a percentage of revenue
Owner bench and management hours
Normalized replacement payroll for the owner role
5. Customer acquisition, approvals, and repeat business
Judge marketing by completed profitable repairs
The base case budgets $3,000 per month for marketing, equal to 5% of revenue. That is a planning assumption, not an industry benchmark. The right budget is the one that produces profitable completed jobs after cancellations, free diagnostics, price shoppers, and warranty work.
One useful sensitivity: if $3,000 creates 120 booked repair opportunities, acquisition cost is $25 per booking. If only 80% become completed paid repairs, the effective acquisition cost becomes $31.25 per completed job. At a $130 average ticket, 96 completed repairs generate $12,480 of revenue and about $8,986 of gross profit at a 72% margin. Subtract the $3,000 marketing spend and the campaign contributes about $5,986 before the rest of operating costs and reserves. If completion drops to 50%, the economics deteriorate fast even though website leads look healthy.
Track marketing through to collected cash
Lead counts do not pay the owner; profitable completed jobs do.
Marketing spend by channel
Cost per booked repair
Booked-to-completed conversion
Revenue and gross profit per acquired customer
Repeat and referral share of completed jobs
6. Overhead, debt service, reserves, and cash discipline
Protect the cash that accounting profit does not protect
The base shop carries $8,000 of fixed overhead and $2,000 of debt service each month before marketing, a $10,000 burden equal to about 16.7% of sales. Rent, utilities, insurance, software, and administration do not fall automatically in a weak week, and debt must still be paid in cash.
Reserves are what keep owner draws from becoming a liquidity problem. The base model withholds 22% of positive profit-before-reserves for tax planning and another 10% for reinvestment. These are internal planning percentages, not legal tax rates. The shop should also handle used devices and batteries correctly; the EPA electronics guidance notes that lithium-ion batteries and devices containing them should not go into household garbage or recycling and directs businesses and consumers to appropriate local options. Disposal, data handling, tools, fixtures, and warranty replacement all belong in the real cash plan even when they are not large monthly line items.
Set a distribution rule before cash piles up
Owner cash should be the last use of funds, not the first.
Minimum operating cash balance
Accounts payable and parts commitments
Next 90 days of debt service
Tax reserve balance versus expected liability
Tool, fixture, warranty, and replacement-capex reserve
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Electronics Repair Shop Bundle
Choosing a selection results in a full page refresh.