What Is the Earning Potential for Ghost Kitchen Owners?
Ghost Kitchen Bundle
For a U.S. single-site, owner-operated ghost kitchen using a second-generation commercial kitchen, a realistic stabilized planning range is roughly $70,000 to $100,000 of annual owner income when sales are near $1.0 million to $1.3 million and costs stay disciplined. The base case here produces $84,000 a year on $100,000 of monthly revenue, after a 22% tax reserve and 8% reinvestment reserve. That owner cash is the residual after ingredients, packaging, delivery-platform economics, hired labor, fixed overhead, marketing, and $3,000 of monthly debt service. It is not a guaranteed salary, EBITDA, or a promise that all accounting profit is safe to distribute.
Owner income$84KNet margin7%Revenue for target pay$1.23MBusiness difficultyHard
What could a ghost kitchen owner take home at different sales levels?
The base case produces $7,000 of monthly owner income, or $84,000 a year, after modeled tax and reinvestment reserves. That is materially above the restaurant industry’s 2024 median pre-tax margin of 4.0% for limited-service operators because this model is explicitly owner-operated: the owner covers the general-manager role and is paid from residual owner cash rather than being included in hired payroll. The National Restaurant Association’s 2025 report on 2024 operating data is a useful reality check on how little margin ordinary restaurant operations leave before owner-specific labor and financing choices are considered.
The calculator therefore answers a specific question: after non-labor direct costs, hired payroll, fixed overhead, marketing, debt service, and the selected reserves, how much cash remains for an owner who is actively running the kitchen business? It does not decide whether that cash should legally be treated as salary, guaranteed payment, draw, or distribution. That depends on entity structure and tax advice.
Owner income calculator
Estimate owner take-home from revenue, direct-cost margin, hired payroll, overhead, financing, reserves, and target pay.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Order volume × average order value
~105 orders/day × $31.75
The base case needs roughly $100,000 of monthly sales. Small misses in order count compound quickly because the kitchen still carries payroll and rent.
2
Channel mix and platform fees
15%-30% marketplace commission
Third-party delivery can buy reach, but commission-heavy sales reduce contribution margin unless menu pricing and direct-order conversion compensate.
3
Food, packaging, and gross margin
54% base gross margin
The model leaves 54 cents of each sales dollar after ingredients, packaging, platform economics, refunds, and payment processing, before labor.
4
Labor productivity and owner coverage
$27K/month hired labor
The base case assumes the owner handles the manager role. Adding a hired GM without more sales can cut owner distributions sharply.
5
Fixed-cost load and debt
$13K/month overhead + debt
Occupancy, utilities, software, insurance, repairs, and financing must be paid even when order volume softens.
6
Repeat orders and marketing efficiency
$4K/month base marketing
Acquisition spend only creates owner cash when repeat behavior and contribution profit exceed the cost of promotions, ads, and loyalty activity.
Want to test the assumptions in a full ghost kitchen forecast?
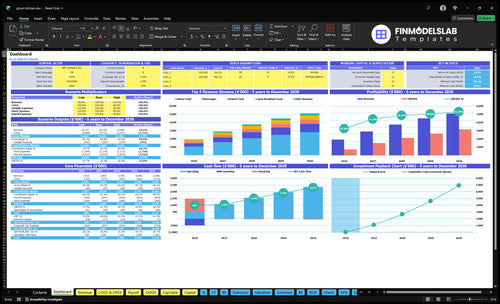
The Ghost Kitchen Financial Model Template for Excel and Google Sheets includes a business-specific dashboard where order volume, average ticket, margins, cash runway, and operating assumptions can be tested together. The screenshot is useful for checking whether the owner-income assumptions in this article still hold after changing channel mix, labor, or startup financing.
What revenue does a ghost kitchen need to pay the owner $96,000 a year?
In the base case, the kitchen needs about $102,646 of monthly revenue, or $1.23 million annualized, to leave $8,000 a month for the owner after the modeled 22% tax and 8% reinvestment reserves. Before any owner income or reserves, operating cash break-even is lower: $44,000 of monthly operating costs divided by a 54% gross margin equals about $81,481 of monthly sales. The gap between those two thresholds is the cost of funding a meaningful owner take-home instead of merely keeping the doors open.
That revenue target should be translated into orders. At a $31.75 blended average order value, $102,646 per month is about 108 orders a day over 30 days. Demand exists for delivery—National Restaurant Association off-premises research reported in 2025 that 37% of U.S. adults order delivery at least weekly—but demand alone does not guarantee that one concept can capture 100-plus profitable orders every day.
Translate sales into kitchen throughput
$100,000 monthly sales is about $3,333 per calendar day.
At $31.75 per order, the base case needs about 105 daily orders.
The $96,000 owner-pay target lifts that to about 108 daily orders.
Peak dinner throughput matters more than the monthly average if demand is concentrated.
What the sales target hides
A $5 average-ticket drop requires roughly 20 more orders a day at the same monthly revenue.
A two-point gross-margin loss raises the revenue needed for the same owner target.
Promotions can raise order count while lowering contribution per order.
Capacity must include prep, packaging, pickup staging, and order-error recovery.
How do delivery commissions and food cost change owner take-home?
They are the fastest way for a ghost kitchen to look busy while producing little owner cash. The base model’s 54% gross margin is not an industry statistic; it is a planning assumption built after non-labor direct costs. As an anchor, the National Restaurant Association reported that limited-service restaurants had a 32.4% median food and non-alcohol beverage cost ratio in 2024. Restaurant food-cost data therefore supports using low-30s food cost as a starting point, not as the whole direct-cost stack.
Delivery platforms can consume another large slice. DoorDash’s current U.S. merchant pricing lists 15%, 25%, and 30% delivery commissions across its Basic, Plus, and Premier marketplace plans. DoorDash merchant pricing makes the channel tradeoff explicit: a marketplace order can be expensive, but it may acquire a customer the restaurant would not otherwise reach. Direct ordering is not free either; DoorDash states that some Online Ordering packages charge 2.9% plus $0.30 per order for processing even at 0% commission. DoorDash’s fee explanation is why the model treats payment processing and platform economics as direct costs rather than hiding them in marketing.
Base direct-cost bridge
Food benchmark anchor: roughly 32% of sales.
Marketplace commissions depend on the share of orders routed through third parties.
Packaging, refunds, and payment processing consume additional contribution.
The modeled result is a 54% gross margin before hired payroll.
Protect contribution, not just order count
Measure contribution dollars per order by channel.
Price marketplace menus only within platform and local-rule constraints.
Push repeat customers toward owned ordering where the economics are better.
Watch refunds and packaging waste as part of direct cost, not overhead.
Key Takeaways
The base owner-operated case produces $84,000 of annual owner income on $1.2 million of annual revenue after modeled reserves.
Cash break-even is about $81,481 a month, while supporting $8,000 of owner pay requires about $102,646 a month.
Platform commission, food cost, packaging, and labor can absorb most of the sales dollar before the owner is paid.
A manager-run ghost kitchen needs more revenue because the owner’s operational labor must be replaced with paid management.
Can a ghost kitchen run without the owner?
Yes, but the owner’s economic return is usually much lower unless sales are high enough to fund management. The base calculator deliberately excludes owner pay from labor cost because the owner is assumed to work as the operations lead. The Bureau of Labor Statistics reported a May 2024 median annual wage of $65,310 for food service managers, with $63,040 in food services and drinking places. BLS food service manager wage data provides a sensible replacement-cost anchor before payroll taxes and benefits.
If you add roughly $6,000 a month of manager payroll and burden to the base case without increasing revenue, profit before reserves falls from $10,000 to about $4,000 a month. After the same 22% tax and 8% reinvestment reserves, owner income falls from $84,000 to about $33,600 a year. That is the difference between owner-operator income and something closer to passive ownership income. It also shows why an owner’s “salary” should not be confused with the business’s residual distributions.
The base $27,000 hired-labor assumption equals 27% of sales because management labor is supplied by the owner. For comparison, the National Restaurant Association reported that salaries, wages, and benefits were a median 31.7% of limited-service sales in 2024. Restaurant labor-cost benchmarks make the owner-labor reclassification visible instead of pretending the business is unusually efficient. At the hourly level, BLS reported May 2024 medians of $17.71 for restaurant cooks and $16.45 for food preparation workers; local wages can be much higher. BLS cook wage data and BLS food-preparation wage data are better starting points than assuming minimum-wage staffing.
Owner income combines compensation for work with residual profit.
The $84,000 figure is not a passive return on capital.
Manager-run economics
Add a market manager wage plus payroll burden.
Keep the owner out of scheduled labor assumptions.
Require higher revenue before paying regular distributions.
Judge passive return after management, debt, taxes, and reinvestment.
How much cash should stay in the business before distributions?
More than the accounting profit suggests. In the base month, the kitchen generates $10,000 of profit before reserves, but the model holds back $2,200 for tax and $800 for reinvestment, leaving $7,000 for the owner. The 22% and 8% rates are planning assumptions, not tax rules. The IRS notes that self-employed owners may need quarterly estimated tax payments, and pass-through income can be taxable to owners even when cash is not distributed. IRS guidance on estimated taxes and pass-through income is the reason tax cash should be separated before treating bank balance as spendable owner income.
Entity structure also changes the salary-versus-distribution question. For an S corporation, the IRS says shareholder-employees must receive reasonable compensation for services before non-wage distributions. IRS reasonable-compensation guidance means the owner cannot simply label all residual cash a distribution to avoid payroll treatment. A sole proprietor or partnership uses different mechanics. The operating model should calculate the business economics first, then a CPA should map those economics to the entity.
Debt creates cash-flow pressure that accounting profit can obscure. This model includes $3,000 of monthly principal-and-interest service. SBA 7(a) loan rates are negotiated but subject to maximums tied to base rates, and the agency’s current program page shows caps that vary by loan size. SBA 7(a) loan terms illustrate why founders should stress-test debt service rather than assume launch financing will stay cheap. Food-service compliance also varies by jurisdiction: the FDA notes that restaurant oversight is typically handled at state and local levels. FDA Food Code adoption guidance supports budgeting for local permits, inspections, training, and compliance rather than treating a delivery-only kitchen as regulation-free.
Pay these claims before a distribution
Vendor invoices, payroll, payroll taxes, rent, utilities, and insurance.
Marketplace adjustments, refunds, software, and marketing commitments.
Debt principal and interest due before the next owner draw.
Estimated taxes, repair reserve, equipment replacement, and working capital.
Profit is not the same as safe cash
EBITDA excludes debt principal and often excludes replacement capex.
Accounting profit may include revenue before all cash has settled.
Owner salary pays for work; distributions pay ownership after obligations.
A reserve policy converts profit into a sustainable draw instead of a bank-balance guess.
What do low, base, and high ghost kitchen owner-income cases look like?
The range is wide because ghost kitchens have high operating leverage. A low case at $70,000 monthly revenue produces only $4,560 of annual owner income after reserves; the base case at $100,000 monthly revenue produces $84,000; and the high case at $150,000 monthly revenue produces $166,320. The high case is not simply more sales with the same cost base: labor rises to $43,000 a month, fixed overhead to $13,000, and marketing to $7,000 to support greater throughput.
These cases should be read against restaurant cost structure, not as salary promises. Limited-service occupancy cost was a median 5.2% of sales in 2024, with higher urban readings, according to National Restaurant Association occupancy data. A ghost kitchen may avoid dining-room space, but it still needs compliant production space, ventilation, utilities, storage, pickup staging, and enough access for couriers. Underwrite the actual lease and common-area charges rather than assuming “no dining room” means low occupancy cost.
Owner income scenarios
Three coherent operating cases using the same calculator presets for revenue, margin, payroll, overhead, marketing, debt, reserves, and owner target pay.
Low, base, and high Ghost Kitchen owner-income planning cases.
Planning factor
Low CaseConservative
Base CasePlanning case
High CaseUpper case
Launch modelMonthly revenue and margin
$70,000 monthly revenue
50% gross margin
$100,000 monthly revenue
54% gross margin
$150,000 monthly revenue
58% gross margin
Typical setupOwner role and throughput
Owner-operated
About 75 orders/day at about $31 AOV
Owner-operated
About 105 orders/day at $31.75 AOV
Owner-operated with added production staff
About 145 orders/day at about $34.50 AOV
Cost driversMonthly operating costs before reserves
$21,000 labor + $9,000 fixed overhead
$2,000 marketing + $2,500 debt
$27,000 labor + $10,000 fixed overhead
$4,000 marketing + $3,000 debt
$43,000 labor + $13,000 fixed overhead
$7,000 marketing + $3,000 debt
Owner income rangeAfter tax + reinvestment reserves
$4,560
Low demand leaves almost no distributable cash.
$84,000
Base owner-operated take-home.
$166,320
Higher throughput with higher staffing and marketing.
Best fitWhen the case is useful
Slow ramp or weak repeat demand
Platform-heavy and discount-sensitive mix
Stable single-site operation
Owner covers management role
Proven kitchen throughput
More direct and repeat ordering
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest ghost kitchen income drivers?
Owner income rises when added sales create contribution dollars faster than they add payroll, platform fees, overhead, debt claims, and reserves. Demand exists—the 2025 off-premises restaurant report found that 37% of adults order delivery at least weekly—but local order density and unit economics determine whether that demand becomes owner cash.
1. Order volume × average order value
Build sales density before adding complexity
The base case is about 105 orders a day at a $31.75 blended ticket for 30 days: roughly $100,000 of monthly revenue. Ten more daily orders at the same ticket add about $9,525 of sales and, at a 54% gross margin, about $5,144 of gross profit before any extra labor or marketing. Profitable order density matters more than app-order count alone.
Track the peak, not just the monthly average
Dinner capacity usually constrains growth before quiet-hour capacity does.
Orders per peak half-hour.
Average order value by daypart and channel.
Ticket time, cancellations, and refunds.
Contribution dollars per kitchen labor hour.
2. Channel mix and platform commission
Use marketplaces for reach without surrendering the margin
DoorDash’s U.S. marketplace delivery plans currently charge 15%, 25%, or 30% commissions. If 40% of $100,000 monthly sales sits on a 25% plan and comparable direct processing costs about 3%, shifting 10 percentage points of total sales to direct ordering saves about 22% of $10,000, or $2,200 a month before added direct-marketing expense. With the base 30% reserve load, that can mean roughly $1,540 more monthly owner cash if volume holds.
Track contribution by channel
Marketplace volume is valuable only when its post-fee contribution and repeat behavior justify the acquisition cost.
Commission and processing dollars per order.
Marketplace versus direct revenue share.
Repeat rate by acquisition source.
Net contribution after promotions and refunds.
3. Food, packaging, and gross margin
Protect every point of contribution margin
The 2024 limited-service median food and non-alcohol beverage cost was 32.4% of sales. Ghost kitchens also absorb packaging, marketplace commissions or direct processing, refunds, and other order-linked costs, so the model uses a 54% gross margin. At $100,000 of monthly sales, one margin point is $1,000 of gross profit; after the base 30% reserves, it is about $700 of monthly owner income if other costs do not change.
Reconcile recipe cost to actual cost
Purchasing, waste, over-portioning, substitutions, and remakes create the gap between theoretical and realized margin.
Recipe and packaging cost per item.
Food purchases as a percentage of sales.
Waste, remake, and refund rate.
Gross margin by menu item and bundle.
4. Labor productivity and owner coverage
Price the owner’s labor before calling the remainder profit
The base hired-labor budget is $27,000 a month, or 27% of sales, because the owner supplies management; the 2024 limited-service median for salaries, wages, and benefits was 31.7%. BLS reported a May 2024 median of $65,310 for food service managers. Adding roughly $6,000 a month for a manager plus burden drops modeled annual owner income from $84,000 to about $33,600 if revenue is unchanged. That is the economic cost of making the kitchen less owner-dependent.
Track labor output, not labor percentage alone
Normalize payroll for the owner role before comparing manager-run and owner-operated economics.
Labor dollars per 100 orders.
Orders per cook-hour at peak.
Owner hours worked each week.
Replacement-manager cost.
5. Fixed-cost load and debt service
Know the revenue floor that does not disappear
Base hired labor, fixed overhead, marketing, and debt service total $44,000 a month. At a 54% gross margin, operating cash break-even before owner income and reserves is about $81,481 of monthly sales. Supporting the $8,000 monthly owner target after reserves needs about $102,646. The 2024 limited-service median occupancy ratio was 5.2% of sales; actual ghost-kitchen rent can vary sharply by city, ventilation, storage, and kitchen condition.
Track fixed claims as runway
A $2,000 increase in monthly fixed overhead requires about $3,704 more revenue at a 54% gross margin before preserving the same owner-pay target.
Occupancy cost versus trailing sales.
Debt service before distributions.
Cash runway in months of fixed claims.
Equipment repair reserve.
6. Repeat orders and marketing efficiency
Make acquisition spend earn back through contribution profit
The base model spends $4,000 a month on marketing outside marketplace commissions. At a 54% gross margin, that spend needs about $7,407 of incremental revenue just to cover its gross-profit cost before extra labor. At a $31.75 ticket, that is about 233 incremental orders a month, or roughly eight a day. A campaign delivering only 120 additional orders produces about $2,057 of gross profit before labor—well short of the $4,000 spend.
Track payback by customer cohort
Repeat contribution should repay acquisition cost; otherwise marketing can grow revenue while reducing distributable cash.
Customer acquisition cost by channel.
30-day and 60-day repeat rate.
Contribution profit per acquired customer.
Direct-order migration from marketplaces.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.