How Should an Owner Estimate Income from an Ice Skating Rink?
Ice Skating Rink Bundle
For a U.S. owner-operated, single-sheet indoor ice skating rink, a practical planning range is about $47,880 to $259,860 a year of owner income after modeled tax and reinvestment reserves, with a base case of $154,836 on $1.38 million of annual revenue. The base case assumes the owner works as the general manager, hired payroll runs about $408,000 a year before owner pay, fixed facility overhead is about $420,000, marketing is $36,000, debt service is $102,000, and non-labor direct costs leave an 87% gross margin. That is materially stronger than many public-rink economics: a Waukesha County ice arena budget shows how personnel, utilities, maintenance, and depreciation can absorb most facility revenue. The modeled owner income is not passive profit, not EBITDA, and not a guaranteed distribution; it excludes any investor preferred return and uses a planning tax reserve rather than the owner's final personal tax bill.
Owner income$155KNet margin11%Revenue for target pay$1.30MBusiness difficultyHard
What could an ice skating rink owner take home at your revenue level?
The calculator below models a single indoor sheet with year-round rentals, public sessions, programs, and ancillary sales. Current municipal pricing provides a useful floor for revenue assumptions: the City of Burnsville's 2026 ice-center fee schedule lists hourly ice from $135 to $280 and public skating at $6 to $8. Labor has to be built separately from gross margin; the BLS recreation-worker benchmark reports a $35,380 national median annual wage in May 2024, with lower pay in other amusement and recreation industries. The model therefore treats payroll as a major operating line instead of hiding it inside cost of sales.
Owner income calculator
Estimate owner cash after rink operating costs, financing, and modeled reserves.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Paid ice-hour utilization
$135-$280/hr
Prime-time contract hours carry the fixed refrigeration plant; empty weekday ice is the fastest way to lose owner cash.
2
Revenue per visit
$7-$8 gate
Admission is only the start. Skate rental, parties, lessons, sharpening, and concessions raise revenue without adding another sheet.
3
Labor coverage
$34K/mo base
Scheduling attendants, ice crew, instructors, and admin to the actual program calendar protects the owner's residual cash.
4
Ice-plant efficiency
20%-25%
Modern refrigeration can materially change electricity and maintenance exposure, but savings must justify the capital required.
5
Contract retention
1,870 hrs
League, school, club, and lesson contracts make demand more predictable and reduce the need to reacquire every skating hour.
6
Capital reserve
$2.19M system
Compressors, floors, boards, and resurfacing equipment can dwarf one year's owner draw if the reserve policy is too thin.
Want to test the rink assumptions in a full forecast?
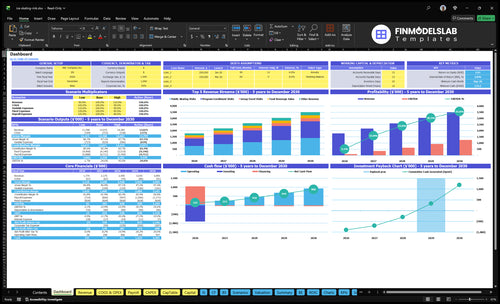
The dashboard preview helps you pressure-test the same owner-income inputs used here: skating revenue by stream, payroll, cost of sales and operating expenses, capital spending, cash flow, and low/base/high scenarios. The Ice Skating Rink Excel Financial Model for Startups is most useful when you replace generic assumptions with your actual lease or mortgage, utility history, club contracts, program calendar, and financing terms.
How much revenue does a single-sheet ice rink need before the owner gets paid?
In the base model, operating break-even before owner pay and reserves is about $92,529 a month, or roughly $1.11 million a year. To support a $9,000 monthly owner-income target after the modeled 34% combined reserve, the calculator needs $108,203 a month, or $1.30 million a year. A current City of Edina open-skating listing shows a $7 admission and a $125 annual pass, which illustrates why public skate alone rarely carries a private indoor rink's full fixed-cost load.
One coherent way to reach the $1.38 million base revenue is a planning mix of about 2,250 contracted or rental-equivalent ice hours at a $235 blended rate, 30,000 public/open-hockey visits averaging roughly $10 including rental attachment, about $350,000 from lessons, camps, clinics, and parties, and roughly $200,000 from concessions, sharpening, retail, sponsorship, and other ancillary activity. Those are planning assumptions, not national averages. They require a schedule that sells prime ice repeatedly and converts some low-demand hours into programming instead of leaving the refrigeration plant running for an empty sheet.
Base revenue math
Annual revenue: $1.38M
Direct non-labor costs: about $179K
Gross profit: about $1.20M
Operating break-even: about $1.11M
What changes the target
One more paid prime hour can add $200-plus revenue
Discounted summer ice needs more volume
Programs raise yield on weak hours
Manager payroll raises the break-even line
Can an ice skating rink owner step away from daily management?
Yes, but the owner-income number should fall unless the rink grows enough to pay a replacement manager. The BLS entertainment and recreation manager data put the May 2024 median at $77,180 nationally and $70,270 in fitness and recreational sports centers. Employer payroll costs also sit above cash wages: the 2026 IRS Employer's Tax Guide sets the employer Social Security rate at 6.2% and Medicare at 1.45% before state unemployment, workers' compensation, or benefits.
This base case deliberately leaves the owner's general-manager labor out of the $34,000 monthly labor input, because the calculator's residual is the owner's total cash capacity. If you add roughly $7,000 to $8,000 a month of all-in replacement management cost, pre-reserve profit falls dollar-for-dollar and after-reserve owner income can fall by roughly $55,000 to $65,000 a year. That does not mean the remaining cash is automatically a tax-free distribution. For an S corporation, the IRS reasonable-compensation guidance says shareholder-employees must receive reasonable compensation for services before non-wage distributions are made.
Owner-operated case
Owner covers GM scheduling and vendor control
Hired payroll excludes owner compensation
$155K is total modeled owner cash capacity
Salary and distributions must be split correctly
Manager-run case
Add manager wage plus payroll burden
Raise revenue or accept lower distributions
Track labor dollars per paid ice hour
Do not call unpaid owner labor passive profit
Why can a busy ice rink still have weak owner cash flow?
Because more activity also increases utility, maintenance, staffing, and replacement wear, while debt and capital reserves are paid in cash. In 2025, Waukesha County authorized extra ice-arena spending after stronger customer activity, including $25,500 of higher utilities and $33,000 of higher maintenance. A private owner cannot treat every incremental ticket dollar as distribution money when the compressor plant, resurfacer, rental inventory, and building are consuming cash at the same time.
The capital tail is the largest hidden risk. A 2025 Minnesota state capital-budget request for La Crescent's community arena listed a $2.19 million ice-system replacement, a $1.64 million rink floor, and a $386,312 dasher-board system. Those are public-project figures, not quotes for this model, but they show why a 12% reinvestment reserve is economically different from an accounting expense. Depreciation may spread equipment cost over years; the contractor invoice and loan principal still require cash.
That distinction is why the calculator should not be read as an income statement. Revenue is the top line. Gross profit here is revenue after selected non-labor direct costs. The $19,550 base monthly “profit before reserves” is a cash-planning subtotal after labor, overhead, marketing, and full debt service, so it is not EBITDA: EBITDA would exclude interest and depreciation and would not deduct loan principal. Accounting profit would include accrual items such as depreciation. Owner salary is compensation for work; owner distributions come from remaining equity cash. The safest draw is what is left only after vendors, payroll, occupancy, debt, taxes, maintenance, and a real replacement reserve are covered.
Cash that must stay in the rink
Payroll and employer taxes
Power, gas, water, dehumidification, and repairs
Debt principal and interest
Equipment and floor replacement reserve
Cash the owner can consider
Reasonable salary for actual work performed
Distribution only after operating obligations
Tax reserve before discretionary draws
Extra cash after seasonal and capex buffers
Key Takeaways
The base owner-operated case produces about $155K after modeled reserves on $1.38M of annual revenue.
Operating break-even is about $1.11M before owner pay; a $108K annual owner target needs about $1.30M of revenue under the base reserve settings.
Hiring a general manager without adding sales reduces owner cash because the current labor line assumes the owner fills that role.
Ice-plant, floor, boards, and other capital needs justify a real reinvestment reserve even when accounting profit looks positive.
What do low, base, and high owner-income scenarios look like?
The biggest swing is not ticket price alone; it is whether the rink can keep enough hours and visits productive while staffing and facility costs rise with demand. Scale can be substantial: the City of Plymouth says its three-sheet Plymouth Ice Center draws more than 600,000 visitors a year. That is not a single-sheet benchmark, but it shows why location, club relationships, tournament traffic, and program depth can create very different revenue ceilings. The scenarios below hold debt service constant but increase labor, overhead, marketing, and reserve percentages as revenue grows.
Owner income scenarios
Low, base, and high cases use the same calculator logic and increase costs as activity increases.
Ice Skating Rink low, base, and high owner-income planning cases.
Scenario factor
Low CaseSlower demand
Base CaseOwner-operated
High CaseStrong utilization
Launch modelDemand and owner role
Slower schedule with discounted off-peak ice and the owner still covering management.
Diversified single-sheet rink with contracts, public sessions, programs, and owner-GM coverage.
Dense prime schedule, stronger programs and events, plus more hired coverage to support volume.
Typical setupMonthly run rate
$95K monthly revenue
86% gross margin
$31K labor
$34K fixed overhead
$115K monthly revenue
87% gross margin
$34K labor
$35K fixed overhead
$150K monthly revenue
88% gross margin
$44K labor
$39K fixed overhead
Cost driversWhat absorbs revenue
$2.5K marketing
$8.5K debt service
20% tax reserve
10% reinvestment reserve
$3K marketing
$8.5K debt service
22% tax reserve
12% reinvestment reserve
$5K marketing
$8.5K debt service
24% tax reserve
15% reinvestment reserve
Owner income rangeAfter modeled tax and reinvestment reserves
$47,880After modeled reserves
$154,836After modeled reserves
$259,860After modeled reserves
Best fitHow to use the case
Stress-test a thin schedule where the owner still works full time and safe distributions are modest.
Plan a stable owner-operated single sheet with diversified revenue and disciplined reserve funding.
Test strong demand only with the extra payroll, utilities, maintenance, and marketing needed to serve it.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move ice skating rink owner income the most?
The six levers below all flow into the same base model. The important point is sequence: sell the sheet, raise the revenue earned per occupied hour, staff to demand, control the plant, lock in repeat contracts, and then keep enough cash for equipment that eventually fails. A rink can look full and still produce weak owner income if only one of those six is working.
1. Paid ice-hour utilization
Make every hour clear its contribution hurdle
Ice time is the core inventory because refrigeration, occupancy, and much of maintenance continue whether the sheet is sold or empty. Burnsville's 2026 schedule spans $135 weekday-morning ice to $280 winter prime time, so a realistic operator should track both hours sold and realized dollars per hour rather than a single sticker rate. In the base case, 2,250 contract or rental-equivalent hours at a $235 blended realization produce about $529,000 of annual revenue before public sessions and programs.
Here's the sensitivity: adding five paid prime-equivalent hours a week at $235 creates about $61,100 of annual revenue. At an 87% gross margin, that adds roughly $53,000 of gross profit before incremental staffing, utilities, and marketing. If those hours can be filled without a new full-time shift, a meaningful portion can reach pre-reserve profit; if they require extra staff and plant runtime, the owner gets less.
Track the sheet like perishable inventory
Separate prime, shoulder, and dead hours so discounting does not hide weak utilization.
Paid ice hours per week
Realized revenue per ice hour
Prime-time renewal rate
Unbooked hours by daypart
2. Revenue per visit and program slot
Do not stop the sale at admission
Public skating is useful for community reach and off-peak monetization, but a $7 or $8 gate cannot carry the building by itself. The City of Edina's party pricing lists a $150 open-skating party for 10 guests, with additional guests at $7 admission and $5 skate rental. That illustrates the revenue stack: admission, rental, room time, food, and group convenience can lift the same hour's yield.
The base model assumes about 30,000 public or open-hockey visits and roughly $10 of combined admission/rental revenue per visit, plus separate program and ancillary revenue. If skate-rental attachment rises from 30% to 40% at a $5 rental fee across 30,000 visits, annual revenue rises by $15,000 before rental-skate wear and cleaning. Programs can be more powerful because lessons, clinics, camps, and parties turn lower-demand ice into prepaid blocks.
Track yield, not just attendance
Visitor count is incomplete unless you know how much each visit contributes.
Revenue per public-skate visit
Skate-rental attachment rate
Program revenue per ice hour
Party and concession spend per group
3. Labor coverage and owner role
Schedule labor against the actual ice calendar
Rinks need front-desk coverage, skate rental, ice resurfacing, cleaning, instructors, event support, and administration across nights and weekends. A Waukesha County 2025 arena plan showed about 4.03 FTE and roughly $336,000 of personnel cost for one public arena, while this private base case uses $408,000 of hired payroll because it assumes a broader commercial program calendar. The figures are not directly comparable, but both show that labor is too large to treat as incidental overhead.
The owner is the missing role in the calculator's payroll. That is intentional: the base output includes the economic reward for the owner also serving as general manager. If the owner steps away and adds $90,000 of annual all-in management cost, base pre-reserve cash falls from $234,600 to about $144,600. With the same 34% reserve setting, owner cash capacity would fall by roughly $59,400, all else equal.
Separate labor from ownership return
Price the owner's work even when the owner does not run a formal payroll line in the planning model.
Labor dollars per paid ice hour
Payroll as a percent of revenue
Owner hours worked per week
Cost of replacement management
4. Refrigeration, utilities, and maintenance efficiency
Control the plant before chasing another promotion
An ice rink is a refrigeration business wrapped inside a recreation business. The La Crescent capital request says a new ice system was expected to be about 20% to 25% more energy efficient than the existing system, with a low-emissivity ceiling expected to add further efficiency. That is a project-specific estimate, not a national benchmark, but it shows why plant condition can change owner economics even when attendance is unchanged.
The base fixed-overhead assumption is $35,000 a month and includes occupancy, utilities, insurance, maintenance, software, and administration. A 10% increase in that line costs $42,000 a year before reserves. Conversely, lowering annual fixed overhead by $30,000 would increase pre-reserve cash by $30,000 and, at the base reserve percentages, increase modeled owner income by about $19,800 if no offsetting capital payment is required.
Measure cost per operating hour
Utility bills are more useful when normalized for ice hours and weather rather than viewed only as monthly totals.
Electric and gas cost per ice hour
Compressor runtime and service events
Maintenance cost per month
Energy project payback after financing
5. Contract retention and recurring demand
Turn clubs and leagues into a forward revenue book
Repeat hockey, figure-skating, school, and lesson contracts reduce acquisition risk because the same block of hours can renew season after season. Waukesha County's 2025 budget for one arena planned about 1,870 contract ice hours, and its notes linked revenue growth to new contract customers and additional hockey teams. That is a public-facility benchmark, but the mechanism is the same for a private rink: recurring blocks make staffing and cash forecasting easier.
Marketing in the base model is $3,000 a month, or $36,000 a year. The goal is not maximum lead volume; it is enough qualified demand to keep the schedule dense and replace churn. If a club representing 200 annual hours at $235 leaves, the revenue hole is $47,000 before any lost concessions or rental attachment. Retention work that prevents that loss may be worth more than a broad consumer campaign that adds scattered low-yield visits.
Run a renewal calendar
Know which contracts expire before the schedule opens to one-off customers.
Renewal rate by organization
Booked hours 90 days forward
Customer concentration by hours
Marketing cost per contracted hour won
6. Debt and replacement-capital discipline
Protect the owner from a false distribution signal
The base model carries $8,500 a month of principal-and-interest debt service and then withholds 12% of positive pre-reserve profit for reinvestment. Those are separate cash uses. Debt pays yesterday's capital; the reserve prepares for tomorrow's compressors, pumps, dasher boards, resurfacing equipment, rental skates, and building work. A rink that distributes both can look highly profitable right before it needs a large emergency check.
In the base case, the reinvestment reserve is $2,346 a month and the tax reserve is $4,301, leaving $12,903 of modeled owner income. If the owner takes the full $19,550 pre-reserve profit instead, the business has no modeled buffer for taxes or equipment. The low case makes the risk clearer: $5,700 of monthly pre-reserve profit becomes only $3,990 of owner cash after a 30% combined reserve. Thin margins do not support aggressive draws.
Set distribution gates before cash arrives
Use policy, not the bank balance, to decide what is actually safe to remove.
Debt-service coverage by month
Minimum unrestricted cash balance
Reinvestment reserve balance
Next major equipment replacement date
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.