Does Owner Income in an Online Learning Platform Depend More on Volume or Margin?
An owner-operated U.S. online learning platform can realistically produce about $91,000 a year of modeled owner income in a stable base case, with a planning range from $0 in a weak-demand case to about $258,000 in a stronger scaled case. The base model assumes about $65,000 of monthly revenue, an 80% gross margin after payment, hosting, refunds, and other non-payroll delivery costs, $40,500 of monthly payroll, overhead, marketing, and debt service, then a 24% tax reserve and 10% reinvestment reserve. The figure is not revenue, EBITDA, a guaranteed salary, or automatically distributable cash; it assumes the founder still performs product, content, and management work and excludes any additional personal tax liability, unexpected legal costs, and major one-time platform rebuilds.
Owner income$91KNet margin12%Revenue for target pay$835KBusiness difficultyModerate
How does an online learning platform turn subscribers into owner income?
For this article, the operating model is a U.S. direct-to-consumer subscription platform selling a library of self-paced professional-skills courses. The base case uses a blended realized price of about $39 per paid subscriber per month, below the regular $59 monthly price currently shown for Coursera Plus, because a smaller platform usually needs annual-plan discounts, promotions, and lower-priced entry tiers. At $65,000 of monthly revenue, that implies roughly 1,670 paid-equivalent subscribers. The owner does not get to keep the subscription receipts: payment fees, content delivery, refunds, contractor royalties, payroll, software, acquisition spend, debt service, taxes, and reinvestment all come first.
The base 80% gross-margin assumption is deliberately different from a large marketplace with substantial partner revenue sharing. Coursera reported a 61.4% Consumer segment gross margin for 2025 in its 2025 Form 10-K, with content costs equal to 38.6% of Consumer revenue. A small platform that owns most course IP and uses limited royalties can plan above that benchmark, but a marketplace that pays instructors or institutions a large revenue share should bring gross margin down accordingly rather than copy the 80% assumption.
Owner income calculator
Estimate owner take-home from subscription revenue, delivery margin, staffing, acquisition spend, reserves, and target pay.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Paid subscribers and retention
1,670 base paid-equivalents
At a $39 blended monthly realization, subscriber count sets the revenue ceiling; churn forces replacement acquisition before growth adds owner cash.
2
Price and plan mix
$39 blended monthly
A $5 lift across 1,670 paid-equivalent subscribers adds about $8,350 of monthly revenue before variable delivery costs.
3
Content and delivery margin
80% base gross margin
Owned content can support strong contribution economics; partner royalties, refunds, and payment fees can pull the margin down quickly.
4
Customer acquisition efficiency
$13K monthly marketing
Base marketing is 20% of revenue. If CAC rises without better retention or ARPU, the owner pay pool is the first thing squeezed.
5
Payroll leverage
$16K monthly non-owner labor
The owner-led base case relies on contractors and a lean team; premature full-time hiring can absorb most of the $11,500 pre-reserve profit.
6
Cash reserves and financing
34% of positive profit reserved
Tax and reinvestment reserves plus debt service separate accounting profit from cash that is actually safe to distribute.
Want to test subscription, churn, and staffing assumptions in a full forecast?
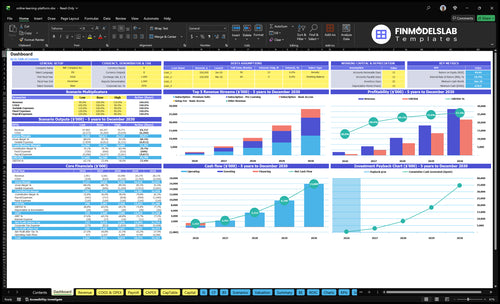
The Online Learning Platform Financial Model provides a business-specific forecast structure for revenue, COGS and operating expenses, payroll, cash flow, scenarios, break-even, and KPI tracking. The dashboard preview is useful for checking whether subscriber growth, plan mix, gross margin, acquisition spending, payroll, and cash runway tell one coherent owner-income story rather than producing a profit number with no liquidity context.
What revenue level supports a $120,000 annual owner target?
In the base cost structure, the calculator needs about $69,564 of monthly revenue, or approximately $835,000 annualized, to support a $10,000 monthly owner target after the modeled reserves. At a $39 blended monthly realization, that is roughly 1,784 paid-equivalent subscribers before allowing for seasonal billing mix. The arithmetic is sensitive to gross margin: every five percentage points of lost margin on $65,000 of monthly sales removes $3,250 from gross profit before payroll or marketing changes.
Revenue math that matters
Subscriber count: active paid accounts, not registrations, determines recurring billing capacity.
Blended realization: annual plans, coupons, failed payments, and tier mix can make realized ARPU lower than the headline plan price.
Payment friction: PayPal's current U.S. fee schedule shows domestic standard credit and debit card payments at 2.99% plus a fixed fee, a useful anchor for direct payment cost in online checkout economics.
What the $835K target hides
It assumes the founder remains the active product and general manager rather than adding a market-rate executive to payroll.
It assumes 80% gross margin, so a high instructor revenue share can push required revenue materially higher.
It assumes $13,000 of monthly marketing is enough to replace churn and still grow; that must be tested against actual CAC and payback.
Can the owner run the platform without a large team?
Yes, but the economics work only if the founder intentionally covers some high-value functions. The base case carries $192,000 a year of non-owner labor, which is lean relative to fully staffing engineering, growth, support, content operations, and management. For context, the U.S. Bureau of Labor Statistics reports a May 2024 median annual wage of $133,080 for software developers, $76,950 for market research analysts, and $20.59 per hour for customer service representatives. A platform that hires all three functions full time, plus payroll taxes and benefits, can easily exceed this base labor budget.
Recurring specialists can be hired as employees or contractors only where workload justifies it.
Owner income is residual cash after operating costs and reserves, so it compensates both founder labor and capital risk.
Manager-run version
Add a realistic product or general-management salary before treating residual profit as passive owner income.
If the company is taxed as an S corporation, the IRS says shareholder-employees must receive reasonable compensation for services before non-wage distributions, so structure pay with professional advice and the IRS compensation rules in mind.
Do not count the manager salary once in labor and then claim the same dollars again as an owner distribution.
Key Takeaways
Base owner income is about $91,000 only after $3,910 of monthly tax and reinvestment reserves.
Subscriber retention and realized ARPU matter more than top-of-funnel registrations because recurring paid accounts fund fixed costs.
A lean owner-operated team can produce better distributions, but owner labor has real economic value and should not be treated as free.
Safe cash is what remains after direct costs, payroll, overhead, marketing, debt, taxes, and reinvestment—not EBITDA or accounting profit alone.
How do churn and customer acquisition change safe distributions?
Churn and CAC determine whether growth creates owner income or only funds a replacement treadmill. In this model, $13,000 of base monthly marketing equals 20% of revenue. If that spend acquires 260 new paid subscribers, CAC is $50; at a $39 realized monthly price and 80% gross margin, gross contribution before labor and overhead is about $31 per subscriber per month, so simple CAC payback is roughly 1.6 months. If acquisition falls to 130 customers at the same spend, CAC doubles to $100 and payback stretches beyond three months before considering churn, refunds, or support.
The operating rule is to calculate paid CAC by channel, cohort retention, gross-margin LTV, and payback together. Marketing claims also carry compliance cost: the FTC's advertising guidance says claims must be truthful, non-deceptive, and evidence-based. A platform selling career outcomes should budget for review of testimonials, outcome claims, and disclosures rather than treating compliance as a zero-cost afterthought.
Retention before scale
Track paid subscribers at the start and end of each month, cancellations, failed-payment losses, and reactivations.
A 5% monthly churn rate requires replacing roughly 84 subscribers each month on a 1,670-member base just to stay flat.
Annual plans can improve cash timing, but deferred revenue is not the same thing as earned profit.
Acquisition before owner draw
Do not cut acquisition to fund a distribution if the result is a shrinking subscriber base next quarter.
Separate brand, affiliate, paid search, social, and partner channels so weak CAC is visible.
Reserve cash for refunds, chargebacks, creative testing, and seasonal acquisition spikes before declaring excess cash.
How should salary, accounting profit, and distributions be separated?
Revenue is the top line; gross profit is revenue after non-payroll direct delivery costs; operating profit or EBITDA-style measures subtract operating expenses but may still ignore debt principal, taxes, capitalized development, and reserve policy. Owner salary pays for work. Owner distributions move residual equity cash to the owner. Safe owner cash is lower than accounting profit whenever debt service, taxes, platform reinvestment, refunds, or working-capital needs consume cash. The IRS emphasizes that federal taxes are generally pay-as-you-go, which is why the model sets aside a tax reserve before owner take-home rather than waiting for filing season.
This calculator intentionally excludes owner pay from laborCost. The active founder's $91,080 base output therefore represents the total residual owner-income pool after modeled reserves, not a pre-set W-2 salary plus another guaranteed draw. In real bookkeeping, the legal form determines whether part of that pool should be wages, guaranteed payments, draws, or distributions. The distinction matters because changing labels does not create cash, and entity-specific payroll and tax rules can change the after-tax result.
What do low, base, and high owner-income cases look like?
The three cases below use the same formula but change demand, gross margin, payroll, overhead, acquisition spend, financing, and reserves together. The low case is intentionally harsh: at $30,000 monthly revenue, 76% gross margin, and $26,500 of operating costs before reserves, the business loses $3,700 per month before owner cash. The high case adds payroll and overhead rather than pretending $130,000 of monthly revenue can be serviced with the base team. For debt-funded growth, remember that the SBA 7(a) program can finance working capital and other eligible needs, but borrowing creates a fixed cash claim that must be paid before distributions.
Owner-income scenarios
Low, base, and high cases use the calculator's matched subscription, margin, staffing, acquisition, financing, and reserve assumptions.
Online Learning Platform low, base, and high planning cases
Scenario factor
Low CaseConservative
Base CasePlanning case
High CaseScaled
Launch modelSubscription scale and demand
$30K monthly revenue
About 1,035 paid-equivalents at $29
$65K monthly revenue
About 1,670 paid-equivalents at $39
$130K monthly revenue
About 2,650 paid-equivalents at $49
Typical setupMargin, staffing, and reserves
76% gross margin
$9K labor
34% combined reserves on positive profit
80% gross margin
$16K labor
34% combined reserves on positive profit
82% gross margin
$30K labor
37% combined reserves on positive profit
Cost driversMarketing, overhead, debt
$8K marketing
$8K overhead
$1.5K debt service
$13K marketing
$10K overhead
$1.5K debt service
$24K marketing
$16K overhead
$2.5K debt service
Owner income rangeAfter modeled tax and reinvestment reserves
$0
$91,080
$257,796
Best fitOperating reality
Early platform or weak retention; owner should prioritize runway over distributions.
Owner-operated niche platform with proven retention and disciplined paid acquisition.
Scaled niche platform with stronger pricing, added staff, and stable acquisition economics.
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six income drivers an online learning platform owner should track?
The six drivers below connect operating behavior to owner cash. They are ordered by economic leverage in this model: subscribers and retention determine recurring volume; price determines revenue per learner; content economics determine contribution margin; acquisition determines the cost to replenish and grow cohorts; payroll determines operating leverage; and reserve and financing policy decides how much accounting profit is actually safe to distribute.
1. Paid subscribers and retention
Build revenue from paid-equivalent learners, not registrations
The base case needs roughly 1,670 paid-equivalent subscribers to generate $65,000 per month at a $39 blended realization. The dangerous shortcut is to model registered users or free trials as if they were customers. A 5% monthly paid churn rate means about 84 cancellations from a 1,670-member base before growth; if marketing adds only 80 new paid users, revenue shrinks even though the funnel still looks active. Coursera's public consumer pricing provides a useful market anchor, but a smaller brand should model its own realized price after annual discounts and promotions rather than assuming the same willingness to pay.
Quick math: improving monthly churn from 5% to 4% preserves about 17 more subscribers in the first month. At $39 each, that is $663 of monthly recurring revenue retained immediately, and the compounding benefit grows if those subscribers stay for additional months. Because most delivery costs are not proportional to every extra learner, retained revenue can be highly valuable to owner cash once support capacity is under control.
Track cohort retention before celebrating signups
Use paid cohorts, not vanity metrics, to determine whether acquisition is funding durable recurring revenue.
Monthly logo churn and revenue churn.
Paid conversion by acquisition channel.
Failed-payment recovery and reactivation.
Three-, six-, and twelve-month cohort retention.
2. Price and plan mix
Use realized ARPU, not the headline plan price
Coursera currently lists regular Coursera Plus at $59 per month and $399 per year, while also running temporary promotions. That spread illustrates why annual plans and discounts change realized monthly economics. The base case deliberately uses $39, not $59, to leave room for lower-tier plans and discounting. If 1,670 paid-equivalent subscribers move from a $39 to a $44 blended realization with no increase in churn, monthly revenue rises by about $8,350. At an 80% gross margin, that creates about $6,680 of additional monthly gross profit before any incremental support, marketing, or tax reserve.
Price increases are not free. Higher prices can reduce conversion or increase cancellation, so the owner should test contribution per visitor and contribution per retained learner, not just ARPU. Annual billing can improve cash receipts, but accounting and cash planning should still recognize that prepaid revenue creates a future service obligation.
Track price realization by plan
Separate sticker price from what customers actually pay after coupons, annual discounts, refunds, and taxes.
Monthly and annual plan mix.
Realized ARPU after discounts.
Conversion rate after price tests.
Refund rate by plan and cohort.
3. Content and delivery gross margin
Protect margin before adding more subscribers
The base model assumes 80% gross margin because payroll is modeled separately and the platform is assumed to own most course IP. That means direct non-payroll costs consume about 20% of revenue. On $65,000 of monthly sales, gross profit is $52,000. If royalties, refunds, payment costs, and hosting push gross margin down to 70%, gross profit falls to $45,500—a $6,500 monthly reduction before a single payroll or marketing dollar changes. The Coursera 2025 Consumer segment's 61.4% gross margin is an adjacent warning that content-sharing economics can be materially heavier than owned-content economics.
Card processing alone is not the whole direct-cost stack. PayPal's U.S. merchant fee schedule shows a percentage-plus-fixed-fee structure for online card payments, while bandwidth, video storage, certificates, proctoring, third-party course licenses, customer refunds, and instructor royalties can all add to cost of revenue. The owner should therefore model gross margin from actual vendor and partner terms instead of assuming “digital” means nearly free delivery.
Reconcile gross margin monthly
Keep direct delivery costs out of payroll and marketing so margin erosion has a clear cause.
Payment fees as a percent of billed revenue.
Refunds and chargebacks.
Content royalties or partner revenue share.
Hosting and video delivery per active learner.
4. Customer acquisition efficiency
Manage CAC against gross-margin payback
The base case spends $13,000 a month on marketing, 20% of revenue. If that produces 260 incremental paid subscribers, CAC is $50. At $39 realized revenue and 80% gross margin, one subscriber contributes about $31 per month before payroll and overhead, so simple gross-margin payback is around 1.6 months. If the same spend produces only 130 paid subscribers, CAC becomes $100 and simple payback extends beyond three months. That extra capital sits in the acquisition funnel instead of the owner's bank account.
Retention determines whether that CAC ever pays back. A channel with cheap first-month conversions but severe cancellation can be worse than a more expensive channel that produces durable annual customers. Also budget for compliant creative and claims review: the FTC requires evidence-based, non-deceptive advertising, which is especially relevant when marketing educational outcomes, career improvement, or testimonials.
Track CAC by channel and cohort
Blended CAC can hide a channel that is destroying contribution margin.
Paid CAC and fully loaded CAC.
Gross-margin CAC payback months.
Conversion rate by landing page and plan.
Retention and refund rate by source.
5. Payroll leverage and the owner's role
Hire only when workload or risk justifies the fixed cost
The base case budgets $16,000 per month for non-owner labor, or $192,000 per year. BLS wage data shows why this is a lean founder-led structure: one median-paid software developer alone was $133,080 in May 2024 before employer taxes and benefits, while marketing and support functions add further cost. The model therefore assumes the owner still performs product management, financial control, content direction, and some growth work, with employees or contractors covering the most repeatable technical, support, and production tasks.
If a founder wants a passive role, payroll should increase before the owner claims the remaining profit as a distribution. Adding $10,000 of monthly management and operating labor to the base case would turn the current $11,500 pre-reserve profit into only $1,500 before reserves, sharply reducing owner take-home. This is why “business profit” and “passive owner income” are not interchangeable.
Track revenue and gross profit per labor dollar
Use hiring thresholds tied to service quality, engineering risk, and contribution rather than calendar milestones.
Payroll as a percent of revenue.
Gross profit per full-time-equivalent worker.
Support tickets and response time per agent.
Owner hours spent in replaceable operating work.
6. Cash reserves, debt, and reinvestment discipline
Distribute only cash that survives reserves and financing
The base case earns $11,500 per month before reserves, then sets aside $2,760 for the 24% tax reserve and $1,150 for the 10% reinvestment reserve. That leaves $7,590 of monthly owner income, or $91,080 annualized. The reserve policy is not an accounting rule; it is a cash-control policy designed to avoid spending money needed for tax payments, content refreshes, security work, platform upgrades, refunds, or runway. The IRS's pay-as-you-go guidance reinforces the need to plan tax cash during the year instead of assuming profit is fully distributable.
Debt creates another fixed claim. The base model includes $1,500 of monthly debt service and the high case $2,500. SBA 7(a) financing can support eligible working-capital and equipment needs, but the program still leaves the business with lender terms and required payments. A founder who uses debt to accelerate content production should model the payment through a downside churn scenario before committing to higher owner draws.
Track cash available for distribution, not just profit
Reconcile the bank balance to obligations before deciding that a profitable month created spendable owner cash.
Tax reserve balance versus expected payments.
Three- to six-month operating cash runway.
Debt-service coverage and upcoming principal payments.
Planned content, security, and platform reinvestment.
Copyright registration can also be a modest but real administrative cost for original course assets; the U.S. Copyright Office fee schedule lists current electronic registration fees, which should be budgeted when formal registration is part of the IP strategy.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Online Learning Platform Bundle
Choosing a selection results in a full page refresh.