What Can an Owner Expect to Take Home from a Property Management Business?
For an owner-operated U.S. third-party residential property management company managing roughly 300 scattered-site single-family and small-multifamily rentals, a realistic base planning case is about $159,936 a year of owner income after a 22% tax reserve and 10% reinvestment reserve on about $840,000 of annual company revenue. The same model produces about $51,912 at a smaller 180-door book and $283,392 at about 440 doors. The revenue logic is anchored to market pricing where full-service management commonly runs around 8% to 12% of monthly rent, then adds leasing, renewal, and coordination fees. This estimate assumes non-owner payroll, fixed overhead, marketing, and company debt are paid first; it excludes the owner's final personal tax settlement and never treats client rent or security deposits as operating cash.
Owner income$160KNet margin19%Revenue for target pay$813KBusiness difficultyModerate
Owner income calculator
Adjust recurring fee revenue, staffing, overhead, financing, and reserves to estimate owner take-home.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Managed doors
300 base-case units
Recurring management fees scale mainly with the number of occupied, rent-paying units under contract; losing 30 doors can erase more owner cash than trimming a few software subscriptions.
2
Effective fee yield
9.5% core fee
A percentage point of management fee on a large rent roll changes revenue quickly, while placement, renewal, and disclosed maintenance coordination fees add a second layer of yield.
3
Staff productivity
$28K monthly payroll
The base case carries about four non-owner FTE. Hiring ahead of door growth can absorb distributions; understaffing can damage service and increase owner churn.
4
Client retention and referrals
Referrals rank #1
Referral-led owner acquisition lowers paid marketing needs, while weak communication can trigger account loss and force the company to replace doors just to stand still.
5
Leasing turnover economics
25% annual placement assumption
Turnovers can create meaningful placement revenue, but they also produce bursts of workload, advertising, inspections, and coordination that must be staffed and priced correctly.
6
Cash reserves and controls
$6,272 monthly reserves
Tax and reinvestment reserves protect payroll, compliance, and working capital; client money is not a substitute for operating cash and should stay segregated.
Want to test the assumptions in a full property management forecast?
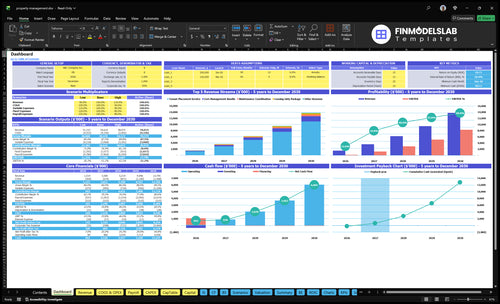
The Property Management Financial Model and Projections Template includes a dashboard and scenario views that can help test managed units, service mix, staffing, cash runway, and owner-income sensitivity together. The preview is most useful for checking whether the revenue engine and payroll plan scale at the same pace rather than assuming every new door drops straight to profit.
How many managed units does it take to support a $160,000 owner income?
In this model, about 300 managed units support roughly $159,936 of annual owner income because the book produces $70,000 of monthly company revenue and $19,600 of monthly profit before reserves. The revenue bridge assumes average collected rent of $2,000 per unit, a 9.5% core management fee, and additional leasing, renewal, and disclosed coordination income. The fee assumption sits inside the 8% to 12% full-service range and 50% to 100% of one month’s rent placement range published by Buildium; the exact door count will move with local rent and scope.
About 75 placements a year at $1,500 each = roughly $9,375 a month averaged across the year.
Renewal, onboarding, and maintenance coordination add about $3,625 a month.
Total modeled revenue = $70,000 a month, or $840,000 a year.
What changes the door threshold
At lower rents, the same percentage fee produces less revenue per door.
Flat-fee markets require a different revenue-per-unit calculation.
More leasing and project work can reduce the number of doors needed, but it increases workload volatility.
Adding a full-time manager before the portfolio grows pushes the threshold upward.
A 300-door book at $2,000 average monthly rent may collect $600,000 for property owners each month, but only contracted management and service fees are company revenue. Client rent is not the company’s sales base for margin, tax, or distribution decisions.
What margin should a property management owner protect?
The model needs about $47,727 of monthly revenue to cover its $42,000 monthly labor, overhead, marketing, and debt service at an 88% gross margin; that is operating break-even before any owner income or reserves. To support the base target of $12,000 monthly owner take-home after the 22% tax reserve and 10% reinvestment reserve, the fixed calculator formula raises required revenue to $67,781 a month, or about $813,372 annualized. Payroll is the biggest controllable step-cost: the BLS reported a $66,700 median annual wage in May 2024 for property, real estate, and community association managers, so an extra experienced manager can quickly absorb $6,000 to $8,000 or more of monthly loaded cash cost in many markets.
Protect the contribution first
The 88% modeled gross margin is a planning assumption after non-labor direct costs, not an industry published margin.
All payroll sits below gross profit in the calculator to prevent direct-labor double counting.
Base payroll is $28,000 a month for non-owner staff; the working owner is paid from residual owner income.
Every $10,000 of lost monthly revenue at an 88% margin removes $8,800 before fixed costs adjust.
Salary is not the same as distribution
Accounting profit is the business result before deciding how much cash to retain.
Owner salary compensates labor; distributions move residual equity cash to the owner.
This calculator combines the owner’s economic take-home into one residual output to avoid counting owner labor twice.
Entity-specific payroll treatment still matters for tax compliance.
If the company is taxed as an S corporation and the owner materially works in the business, the IRS requires reasonable compensation before non-wage shareholder distributions. That means the $159,936 base owner-income figure is not a recommendation to take $159,936 entirely as distributions. It is the cash pool after modeled business costs and reserves; a CPA should determine the wage-versus-distribution split and the owner’s actual federal and state tax liability.
Why can a profitable property manager still be short of cash?
Property management can show accounting profit while operating cash is tight because payroll and software are paid on schedule, leasing fees arrive unevenly, client acquisition costs come before a new portfolio is fully productive, and some cash in the bank may belong to property owners or tenants rather than the company. The NARPM Code of Ethics says funds received on behalf of others should not be commingled with personal or business funds, so security deposits, owner reserves, and rent collections cannot be treated as a free working-capital line.
Base cash bridge
$70,000 monthly revenue creates $61,600 gross profit at the modeled 88% gross margin.
$42,000 of labor, fixed overhead, marketing, and debt service leaves $19,600 before reserves.
$6,272 is retained for modeled tax and reinvestment reserves.
$13,328 remains as monthly owner income, leaving a $1,328 cushion above the $12,000 target.
What this estimate hides
Payroll can hit before a large placement-fee month closes.
Chargebacks, legal costs, fair-housing issues, and emergency staffing can create irregular expenses.
Owner draws taken too early may need to be replaced when tax or renewal season arrives.
Debt principal consumes cash even when accounting depreciation moves the other direction.
The reserve percentages are intentionally planning controls rather than tax promises. A founder who keeps $6,272 a month in tax and reinvestment reserves in the base case has more room to absorb a lost client, a legal bill, or a new hire. The safest distribution policy is therefore based on cash after obligations and reserves, not the P&L headline alone.
Key Takeaways
A 300-door owner-operated book can support about $160,000 of modeled annual owner income when pricing and staffing hold.
Operating break-even is about $47,727 monthly revenue, while the $12,000 target owner pay requires about $67,781 monthly revenue after reserves.
Client rent and security deposits are not company cash; trust-fund discipline is part of owner-income protection.
Owner salary, accounting profit, and distributions are different concepts even when they come from the same economic cash pool.
Can a property management company run without the owner?
Yes, but a manager-run company needs enough revenue per door to replace the owner’s operating labor without crushing distributions. The base case is intentionally owner-operated: the owner handles senior client relationships, escalations, pricing, hiring, and licensed oversight where required, while $28,000 of monthly labor covers non-owner staff. In most states some form of property-management or real-estate licensing is required, according to BLS licensing guidance; California, for example, has separate broker-license experience and coursework requirements. A founder cannot assume that hiring an unlicensed coordinator fully replaces licensed responsibility.
When to hire a general manager
Hire after recurring fee gross profit can cover the role without relying on one-time placement spikes.
Define who owns after-hours escalation, owner retention, compliance, and pricing authority.
Keep the owner’s economic return separate from the manager’s market wage.
Rebuild the calculator with the manager’s loaded payroll added to labor cost.
What makes owner absence possible
Standardized leasing, maintenance, inspection, accounting, and owner-reporting workflows.
Enough recurring revenue that service quality does not depend on the founder doing unpaid work.
A referral engine that lowers the need for constant founder-led selling.
Passive ownership income is usually lower at the same door count. If a replacement general manager costs $90,000 to $120,000 loaded annually, much of the residual owner-income pool becomes payroll. The trade may improve transferability, but it is not free.
How do low, base, and high property management owner-income scenarios compare?
The scenarios below use the same calculator formulas and change revenue, staffing, overhead, marketing, debt service, and reserves together. Use the cases as planning boundaries, then replace the rent roll, local wages, licensing burden, and service package with your market data before making a hiring or distribution decision.
Owner income scenarios
Low, base, and high cases show how managed doors, fee yield, staffing, and reserves change safe owner cash.
Property Management low, base, and high owner-income planning cases.
Planning factor
Low CaseConservative
Base CasePlanning case
High CaseScaled
Launch modelOperating position
Owner-led 180-door book with lean support staff.
Owner-led 300-door book with about four non-owner FTE.
Scaled 440-door book with a larger service and admin team.
Typical setupRevenue assumptions
$38,000 monthly revenue
86% gross margin
Lower fee yield and fewer placements
$70,000 monthly revenue
88% gross margin
9.5% core fee planning assumption
$110,000 monthly revenue
89% gross margin
Stronger rent roll and add-on mix
Cost driversMonthly operating load
$15,000 labor
$7,500 fixed overhead
$2,500 marketing
$1,500 debt service
$28,000 labor
$9,000 fixed overhead
$3,500 marketing
$1,500 debt service
$42,000 labor
$11,000 fixed overhead
$6,000 marketing
$2,000 debt service
Owner income rangeAfter modeled reserves
$51,912
After modeled reserves.
$159,936
After modeled reserves.
$283,392
After modeled reserves.
Best fitHow to use the case
Stress-test a smaller portfolio where fixed staffing and compliance costs are hard to spread.
Use as the main planning case for an owner-operated regional residential manager.
Test scaling economics only when additional staff and service capacity are funded.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest property management income drivers?
The six drivers below explain why firms with the same door count can pay owners very differently. Revenue per door matters alongside staffing, retention, turnover workload, and cash controls. Buildium’s 2026 industry research says 75% of property managers planned to grow, while only 55% had expanded in 2025, a useful reminder that planned portfolio growth does not automatically become profitable scale.
1. Managed doors and collected rent base
Translate doors into fee-bearing rent
Door count is the first ceiling on recurring revenue, but the stronger measure is collected rent under management. In the base case, 300 units at $2,000 average monthly collected rent create a $600,000 monthly rent roll. At a 9.5% management fee, that is $57,000 of recurring company revenue before any placement or renewal work. A 10% loss of doors with the same rent and fee removes about $5,700 of monthly recurring revenue, or $68,400 annually, before any staffing can be cut.
That relationship is why a founder should track both doors and fee-bearing rent. Buildium’s pricing guidance places full-service management at 8% to 12% of monthly rent, so a low-rent market can require materially more doors than a high-rent market to fund the same team.
Track revenue per managed door
Use a rolling monthly figure that excludes pass-through client funds.
Managed doors at month-end
Collected rent under management
Core management fee revenue
Monthly company revenue per door
If revenue per door falls while workload per door rises, owner income is usually next to compress.
2. Effective fee yield and service mix
Price the work you actually perform
Core management fees are only one part of the economics. Buildium lists leasing or tenant-placement fees at 50% to 100% of one month’s rent or roughly $500 to $1,500, renewal fees at $100 to $350, and maintenance markups at 10% to 15% of an invoice. The base model does not assume the top of every range; it uses a $1,500 average placement fee and modest annual renewal and coordination income.
Here is the quick math: lifting the effective management fee from 9.0% to 9.5% on a $600,000 monthly rent roll adds $3,000 of monthly recurring revenue. At an 88% gross margin, that adds about $2,640 before payroll, overhead, reserves, and taxes. Pricing discipline can therefore move owner income faster than chasing a handful of low-value doors.
Track realized fee yield
Compare contracted fees with what is actually billed and collected.
Core fee as a percent of collected rent
Placement revenue per turnover
Renewal fee realization
Disclosed maintenance coordination revenue
Discounts, waived fees, and unbilled scope creep should appear as explicit margin decisions, not surprises.
3. Staff productivity and payroll per door
Do not hire two quarters ahead of revenue
The base case carries $28,000 of monthly non-owner labor and employer burden. That is roughly $336,000 annually spread across about four operating and administrative FTE, while the owner covers senior management. The BLS May 2024 median wage of $66,700 is a useful national anchor for property-management labor, but local wage requirements and role seniority can move the actual payroll significantly.
At 300 units, $28,000 monthly payroll equals about $93 per door each month. If the business hires another $7,000-per-month loaded manager at the same revenue, owner income falls by roughly $4,760 a month after the model’s 32% combined reserves, unless service capacity creates enough new revenue to offset the hire. The operational question is not whether more staff would be helpful; it is when recurring gross profit can support them.
Track doors and revenue per FTE
Use workload and service quality together, not a single headcount ratio.
Managed doors per non-owner FTE
Revenue per FTE
Open maintenance and leasing tasks
Owner escalations per 100 doors
When response times or owner satisfaction deteriorate, capacity is already too tight even if payroll looks efficient.
4. Client retention and referral-led acquisition
Protect the book before buying more leads
Property management growth is unusually sensitive to reputation because an existing owner relationship can be worth years of recurring fees. Buildium’s 2026 trends research says referrals from current clients are the industry’s #1 growth method. That supports the base model’s $3,500 monthly marketing budget rather than assuming every new owner must come from expensive paid acquisition.
Retention is equally important. AppFolio’s owner-experience research says nearly 25% of owners were considering switching property managers, with poor communication a major risk. If a 300-door firm loses 15 doors and each door contributes roughly $190 of monthly core fee revenue at the base rent and fee, about $2,850 of recurring monthly revenue disappears before considering lost renewals or placement work.
Track net door retention
Measure acquisition and churn in the same report.
New doors signed
Doors lost and reasons
Owner referral share of new business
Marketing spend per net new door
A firm adding 20 doors while losing 15 has a very different cash profile from one keeping all 20.
5. Leasing turnover economics
Treat turnover as both revenue and workload
The base scenario assumes about 75 placement events a year, equal to 25% of 300 managed units, at an average $1,500 placement fee. That creates about $112,500 of annual revenue, or $9,375 per month when smoothed for planning. The fee level is consistent with the published placement range, but the 25% turnover rate itself is a planning assumption and should be replaced with the firm’s actual renewal history.
Turnover is not pure upside. Advertising, showing, screening, move-out documentation, repairs, vendor coordination, and owner communication peak at the same time. Buildium’s 2026 report found 75% of property managers reported increased rental fraud, reinforcing the need to budget screening time and controls rather than treating placement fees as near-zero-cost revenue.
Track profit per placement
Separate fee revenue from the labor and direct costs it creates.
Placements per month
Average placement fee
Days vacant before lease
Staff hours and direct spend per placement
A higher turnover month can boost revenue while still hurting owner cash if the operating team is overwhelmed.
6. Cash reserves, debt, and trust-fund discipline
Distribute residual cash, not bank balance
In the base case, $19,600 of monthly profit before reserves becomes $13,328 of owner income after a $4,312 tax reserve and $1,960 reinvestment reserve. The calculator also deducts $1,500 of monthly company debt service before that owner cash is calculated. The reserves are not expenses on a conventional income statement, but they are deliberate cash holds that reduce what is safe to distribute.
Client money must stay outside this decision. The NARPM handling-of-funds standard requires member property managers to keep funds received for others in accordance with law and not commingle them with business or personal money. Licensing rules vary by state, but the economic principle is universal: a bank balance that includes owner reserves or tenant deposits overstates distributable company cash.
Track a distribution-ready cash balance
Close the books before drawing money.
Operating cash excluding all client funds
Tax reserve balance
Reinvestment and working-capital reserve
Next 30 days of payroll, debt, and fixed bills
Only the excess after those obligations is genuinely available for an owner draw or distribution.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Property Management Bundle
Choosing a selection results in a full page refresh.