

Revenue and Calc
Set annual-average managed units, five property-type shares, and monthly management fees. The monthly calculation schedule assigns demand to each contract category and consolidates service-fee revenue.


This Property Management Financial Model is an Excel template for planning fee revenue, staffing, operating costs, and funding at an independent US residential manager. Its demand-based forecast converts managed-unit counts and monthly fees into financial projections for 2026–2030.
The example manages single-family homes, condos, and small multifamily buildings through a hybrid office. Owner rents, deposits, repairs, and capital projects remain outside management-company revenue and expenses.
Edit property management assumptions, then review linked operating schedules, financial statements, and planning reports.
Set annual-average managed units, five property-type shares, and monthly management fees. The monthly calculation schedule assigns demand to each contract category and consolidates service-fee revenue.
Plan field visit and screening costs, percentage-based operating expenses, monthly fixed overhead, annual staffing FTE, and salary rates by role.
Select Low, Base, or High assumptions for revenue and expense groups. The Dashboard also contains working-capital settings and four optional debt facility controls.
The Income Statement, Cash Flow, Balance Sheet, and Summary link profit, cash movement, and financial position.
CAPEX, CapTable, Debt, Returns, Valuation, and Checks support funding, payback, sensitivity, and reconciliation.
Annual-average active managed units are allocated across five property types and multiplied by the corresponding monthly flat fee.
The example grows annual-average managed units from 120 in 2026 to 450 in 2030; interim assumptions are 180, 260, and 350. Each year’s portfolio is allocated once across property types.
The portfolio mix is 35% single-family, 15% condos, 20% buildings of 2–6 units, 15% buildings of 7–12 units, and 15% buildings of 13–24 units. Per-unit fees include leasing, renewals, and coordination.
The Revenue Forecast connects managed-unit demand, property-type allocation, and fee assumptions to annual service-fee revenue. Its monthly Calc schedule applies launch timing and aggregates the five categories without adding owner rental funds.
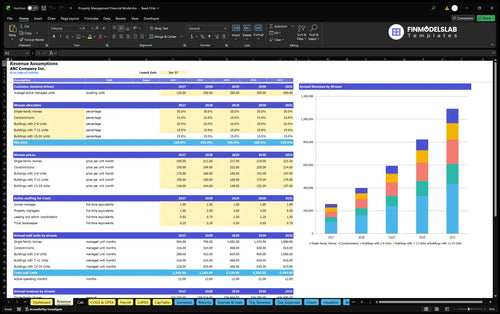
120 managed units × $179.50 weighted monthly fee × 12 modeled months = $258,480 annual revenue.
The 2026 weighted fee reflects the five starting monthly prices: $205, $190, $175, $155, and $140 per managed unit. In 2030, the respective prices are $231, $214, $197, $175, and $157.
This is a demand-led contract model: it does not apply a separate occupancy rate, installed-capacity ceiling, or acquisition limiter. Changing managed-unit counts or fee mix flows into revenue, costs linked to revenue, and resulting profitability.
Service costs and variable overhead scale with fee revenue, while fixed overhead and role-based compensation follow separate assumptions.
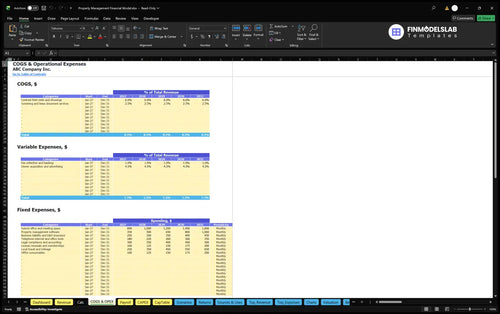
Direct COGS is 8.5% of revenue: contract visits and showings at 6%, plus screening and lease documentation at 2.5%. Variable expenses total 5.5%: fee collection and banking at 1%, plus owner acquisition and advertising at 4.5%.
Fixed monthly expenses cover the hybrid office, software, insurance, office tools, compliance, memberships, travel, and consumables. The hybrid-office line increases from $800 per month in 2026 to $1,600 per month in 2030.
The COGS and Operating Expenses forecast separates direct service costs, variable business expenses, and fixed overhead. Expense dates, frequencies, and annual assumptions feed monthly spending and the margin calculations in the Income Statement.
| Cost category | 2026 | 2030 |
|---|---|---|
| Direct COGS | $21,971 | $92,787 |
| Variable expenses | $14,216 | $60,039 |
| Fixed expenses | $27,960 | $59,400 |
| Payroll | $171,500 | $500,500 |
Rounded category amounts can differ slightly from reported operating expense totals.
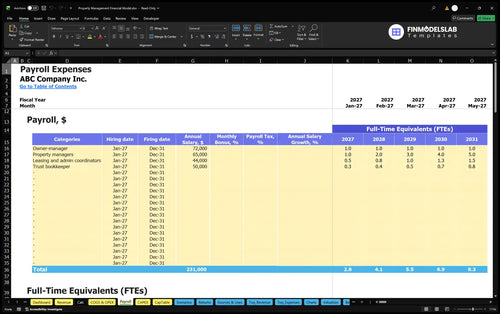
The owner-manager stays at 1 FTE; property managers rise from 1 to 5, coordinators from 0.5 to 1.5, and trust bookkeeping from 0.25 to 0.75 FTE.
The Payroll Forecast shows staffing FTE and annual base pay by role. Salaries are $72,000 for the owner-manager, $65,000 for property managers, $44,000 for coordinators, and $50,000 for the trust bookkeeper.
Startup assets, preopening spending, receivables, and an initial reserve are separate from annual EBITDA.
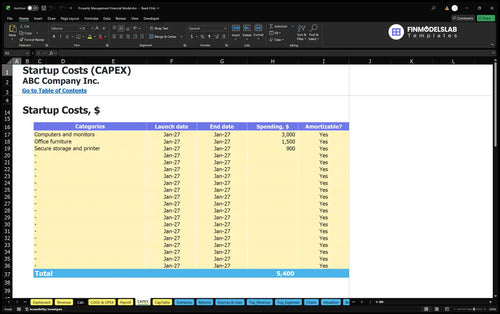
The owner-funded example includes $5,400 in equipment and $10,600 in preopening needs: setup, licensing, software, branding, marketing, and an office deposit.
The Capital Expenditure Plan schedules equipment purchases, spending dates, and depreciation. These asset investments are separate from operating expenses used to calculate EBITDA.
Funding also provides for $10,622 in opening management-fee receivables and an estimated $58,912 three-month project reserve. Together with the launch assets and other cash, these make up approximately $85,534 in initial owner funding.
The Sources and Uses of Funds report reconciles funding with cash allocation. The example uses owner contributions, while optional debt facilities can be configured on Dashboard.
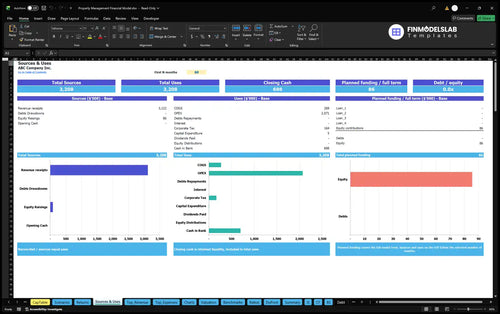
Working-capital settings use 15 receivable days, zero payable days, and zero inventory days. They control cash timing, not sales or proven reserve adequacy.
The illustrative Base case grows management-fee revenue as unit volume and monthly fees increase, while payroll and operating costs also rise.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $258,480 | $235,647 | $22,833 |
| 2027 | $399,276 | $344,039 | $55,237 |
| 2028 | $593,424 | $462,399 | $131,025 |
| 2029 | $823,620 | $585,807 | $237,813 |
| 2030 | $1,091,610 | $712,725 | $378,885 |
Projected results are illustrative, not historical business performance or industry averages. Whole-dollar rounding may affect displayed arithmetic.
Base-case EBITDA rises from $22,833 in 2026 to $378,885 in 2030, as more fee income spreads overhead. The result depends on selected assumptions.
EBITDA is revenue less the documented direct, variable, fixed, and payroll operating expenses. It is not net income or cash flow; interest, depreciation, tax, capital spending, receivables, and financing are separate considerations.
The Cash Flow Forecast analyzes monthly operating, investing, and financing cash movements and reconciles opening to closing cash. Use it to examine receivable timing, startup spending, contributions, and possible liquidity gaps beyond the EBITDA projection.
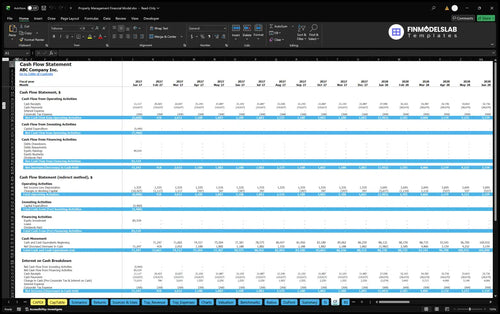
Income Statement, Balance Sheet, and Summary provide linked reports; Dashboard compares Low, Base, and High assumptions. The example supplies EBITDA, not net-profit or cash-balance figures.
The workbook includes separate analyses for operating break-even, cash recovery, capital returns, and valuation sensitivity.
Sales break-even estimates the sales needed to cover the modeled cost structure. Cash break-even considers when cash activity turns positive, while investment payback tracks recovery of invested funds and annual ROIC assesses return on invested capital.
The Returns report compares sales with break-even requirements and tracks project cash flows, cumulative recovery, and ROIC. Those measures help evaluate operational scale and capital recovery without treating positive EBITDA as proof of payback.
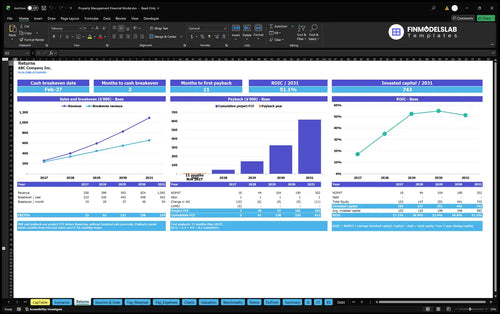
Valuation provides DCF sensitivity; Benchmarks compares entered KPIs, and Ratios and DuPont analyze financial performance. No example valuation, payback date, or ROIC is claimed.
The model helps founders and operators connect their contract portfolio, fee policies, staffing plan, and financing choices.
Use the model to test the consequences of adding managed units, revising the single-family versus multifamily mix, changing per-unit fees, or hiring additional property managers. Compare those decisions using revenue forecasts, expenses, cash flow, and break-even reports.
The example represents a US secondary-market residential manager. Replace estimated fees, salaries, and costs with actual company and local inputs before making funding decisions.
How this model’s inputs and reports work.
Yes. Change annual-average managed units, property-type shares, and per-unit monthly fees to recalculate the demand-based revenue forecast.
No. The illustrative operating model counts management fees only; owner rent, deposits, repair reimbursements, and capital projects are excluded from company revenue.
Payroll uses staffing FTE and salary assumptions by role, including an owner-manager, property managers, coordinators, and a trust bookkeeper.
Yes. It contains linked Income Statement, Cash Flow Statement, Balance Sheet, and Summary worksheets; the published example results are limited to operating EBITDA.
Yes. Dashboard scenario controls adjust revenue, COGS, variable expenses, fixed expenses, and payroll assumptions for comparison.
No committed borrowing is included in the example. The workbook also provides four optional debt facility controls and an equity contribution schedule.
No. Payback, cash break-even, ROIC, and liquidity require separate cash-flow and invested-capital analysis; no specific payback month is claimed.
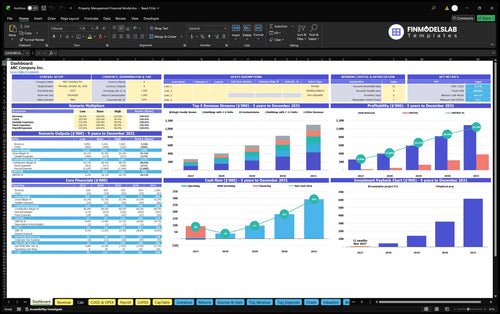
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
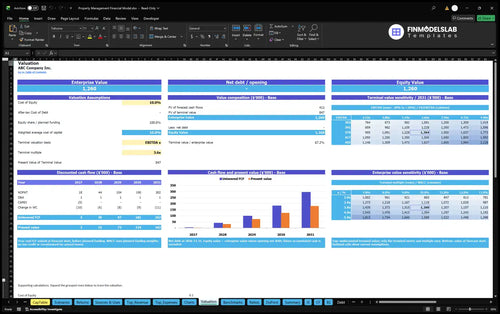
DCF valuation and sensitivity analysis.
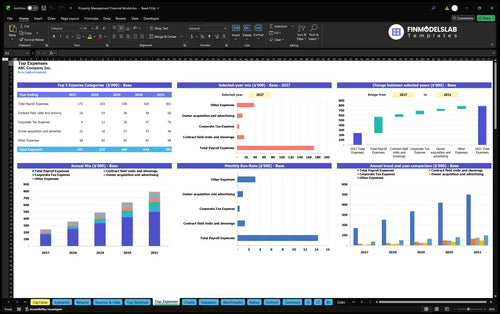
Largest costs and spending trends.
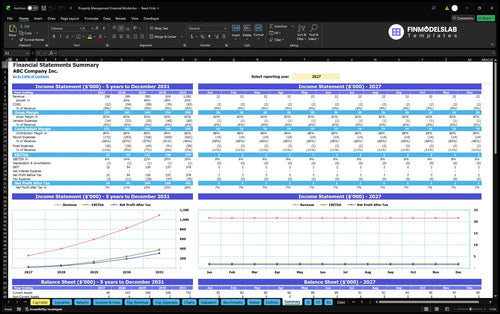
Annual and monthly financial performance.
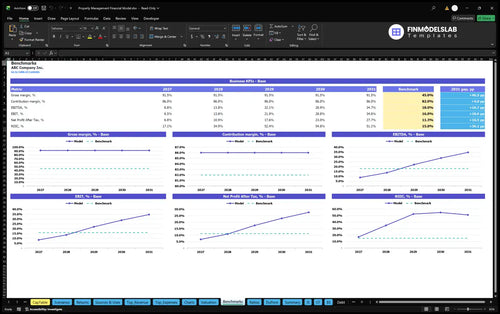
Compare margins and returns to benchmarks.

This template made runway and shortfall timing much easier to see, so I could plan two months ahead instead of guessing. It saved me about 6 hours of manual recalcs every week.

I stopped chasing numbers across tabs and files once everything was organized in one model. It cut our monthly reporting prep by 4 hours and made the board deck much simpler to pull together.
The margin and break-even tabs gave me a clear view of which properties were actually carrying their weight. That helped me tighten pricing assumptions and book a planning review sooner.