How Do Revenue and Margin Affect Owner Pay in a Solar Panel Installation Business?
Solar Panel Installation Bundle
For an owner-operated U.S. residential solar panel installation company, a realistic planning case can produce about $271,000 a year of owner income after modeled tax and reinvestment reserves at roughly nine residential systems per month. The base model uses $280,800 of monthly revenue, a 56% gross margin after non-labor direct project costs, $72,000 of non-owner payroll, $23,000 of fixed overhead, $22,000 of marketing, and $6,000 of debt service. A weak case at about $150,000 of monthly sales leaves no safe owner residual; a scaled high case reaches about $599,000 a year. These are planning assumptions, excluding extra personal tax, owner payroll-tax effects, major warranty shocks, and added working-capital calls.
Owner income$271KNet margin8%Revenue for target pay$3.1MBusiness difficultyHard
How much can a solar panel installation owner make?
A residential installer supports owner income only after volume absorbs payroll, sales expense, permitting, trucks, insurance, and debt. EnergySage reported an average 2026 quote of about $2.60 per watt and $31,135 for a 12 kW system; the U.S. Department of Energy separately breaks residential cost into hardware, fieldwork, office work, and other developer costs in its residential PV benchmark. The base case uses nine roughly 12 kW projects at about $31,200 each, or $280,800 monthly. Roof complexity, electrical upgrades, labor, equipment, financing channel, and state incentives can move that ticket.
The calculator separates non-labor project cost from payroll. A 56% gross margin means 44% of revenue is consumed by hardware, permits, and other non-labor project charges; employee payroll is deducted later. This avoids subtracting installation labor twice.
Owner income calculator
Estimate owner take-home from completed-project revenue, margin, payroll, overhead, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Completed installs
9 systems/mo
Base revenue assumes nine roughly 12 kW residential projects; losing two completions can move sales below the owner-pay threshold.
2
Pre-payroll margin
56%
Hardware, permit, engineering, and other non-labor project costs must leave enough contribution to pay crews and overhead.
3
Crew productivity
$72K/mo payroll
Two efficient crews plus electrical and office support can protect throughput; idle days and overtime squeeze owner cash quickly.
4
Lead economics
$22K/mo
Marketing has to produce signed, installable projects rather than raw leads; weak conversion raises the acquisition cost of every completed job.
5
Permit-to-cash cycle
Weeks to months
Permits, inspections, utility steps, supplier timing, and final collections can consume cash even when the P&L shows a profit.
6
Debt and reserves
$17.6K/mo
Base debt service plus tax and reinvestment reserves absorb cash before the remaining $22,603 monthly owner-income output is safe to consider.
Want to test the assumptions in a full solar forecast?
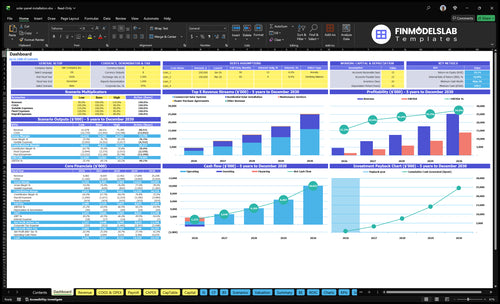
The Solar Panel Installation Startup Financial Model Template provides an editable workbook for customer acquisition, billable activity, costs, payroll, scenarios, statements, and cash flow. The dashboard helps test whether growth improves profitability, payroll scales with workload, and cash remains adequate through design, installation, and collection.
What sales volume supports a six-figure owner income?
Operating break-even is about $220,000 per month before owner reserves and pay. Supporting the $15,000 monthly target after reserves requires $260,227 per month, or $3.12 million per year. At roughly $31,000 for a 12 kW system, that is about eight completed jobs to clear operating break-even and nine to support target pay. DOE notes that PV installation generally takes only a few days, while permits and inspections can take weeks to months, so administrative flow can cap capacity as much as roof time.
Base revenue math
Nine 12 kW jobs at about $31,200 each produce $280,800 monthly revenue.
At 56% pre-payroll margin, gross profit is $157,248 before payroll and overhead.
Base operating costs total $123,000 per month before tax and reinvestment reserves.
The model leaves $22,603 monthly owner income after reserves, or $271,236 annually.
What makes volume fragile
A signed contract is not the same as a completed, collectible installation.
Roof repairs, main-panel upgrades, failed inspections, and utility queues can push jobs into the next month.
Discounting to rescue volume can lower both contract value and pre-payroll margin.
Use completed jobs, installed watts, and collected cash as separate KPIs.
How do labor and crew utilization change take-home?
Labor is a major owner-income line because the company needs field capacity and qualified electrical work. BLS reported a May 2024 median of $51,860 for solar PV installers and a $62,350 median for electricians. Employer cost is higher after payroll taxes, workers' compensation, benefits, overtime, travel, and idle time, so the base case uses $72,000 of monthly non-owner payroll.
Owner-operated structure
The owner covers general management, pricing, vendor oversight, and some sales leadership.
Field crews, electrical work, design or permitting support, and coordination remain paid labor.
The owner's labor is not hidden inside the $72,000 payroll line; owner cash is the residual output.
If the owner stops working in the business, add a replacement manager before treating distributions as passive income.
Quick labor sensitivity
Every extra $10,000 of monthly payroll reduces profit before reserves by $10,000.
At the base 34% combined reserve rate, that can cut owner cash by roughly $6,600 per month if revenue and margin do not improve.
Overtime can be cheaper than a permanent hire during short peaks, but repeated overtime often signals a capacity problem.
Track installed watts per field labor hour and completed jobs per crew-week, not payroll percentage alone.
Key Takeaways
Revenue becomes owner income only after hardware, payroll, overhead, marketing, debt, taxes, and reinvestment needs are covered.
The base case needs about nine average residential installs per month and about $3.12 million of annual revenue to support a $15,000 monthly owner-pay target.
Crew productivity, customer acquisition, and permit-to-cash timing can matter as much as the quoted price per watt.
Owner salary and owner distributions are two ways to deliver owner compensation; they should not be counted twice.
Why can a profitable solar installer still run short of cash?
Solar installation is a working-capital business: equipment, crews, insurance, and permit work may be paid before final customer cash arrives. DOE notes that permitting, inspection, and utility connection are required steps, while its solar soft-cost guidance includes customer acquisition, permitting, financing, installation, supplier payments, and overhead. A profitable P&L can therefore coexist with a tight bank balance.
What cash must fund first
Base non-labor direct project cost is about 44% of sales, or roughly $123,600 in an average month.
Non-owner payroll adds another $72,000 before owner cash is considered.
Debt service is $6,000 monthly even if a project slips out of the completion schedule.
The 10% reinvestment reserve is a retention policy, not a complete substitute for opening working capital.
Cash controls that protect draws
Forecast signed contracts, equipment commitments, installation dates, inspections, and collections separately.
Match supplier terms and customer payment milestones as closely as contracts and state rules allow.
Hold warranty and rework cash outside the owner's normal draw decision.
Do not distribute cash needed for payroll, sales-tax obligations, debt payments, or committed equipment orders.
What do low, base, and high owner-income cases look like?
The low case shows fixed payroll erasing owner cash when installations slip; the high case adds labor, overhead, marketing, and debt rather than treating growth as free. SEIA reported U.S. residential solar installed 4,647 MWdc in 2025, down 2% from 2024, while the market adjusted to the homeowner Section 25D credit ending after 2025. A 2026 plan should stress-test lead conversion and financing sensitivity.
Owner income scenarios
Low, base, and high cases use the same calculator logic for project revenue, pre-payroll margin, staffing, overhead, marketing, debt, and reserves.
Solar Panel Installation low, base, and high owner-income planning cases
Planning factor
Low CaseLow
Base CaseBase
High CaseHigh
Launch modelSales and crew structure
About five installs per month with one core crew and price pressure.
About nine installs per month with two crews and owner-led management.
About sixteen installs per month with added crew capacity and stronger purchasing.
Owner income rangeAfter modeled tax + reinvestment reserves
$0
$271,236
$599,196
Best fitHow to use the case
Stress-test slow demand, discounting, and underused labor.
Budget staffing, debt capacity, and normal owner-pay decisions.
Test whether added crews and purchasing scale without losing cash discipline.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
How should owner salary and distributions be separated?
Owner compensation depends on tax entity and duties. The calculator leaves owner pay outside labor and computes residual cash after project costs, non-owner payroll, overhead, marketing, debt, and reserves. For an S corporation owner who performs substantial services, the IRS generally requires reasonable compensation before non-wage distributions. The modeled $271,236 is therefore not automatically a distribution; actual books may split it between W-2 wages and distributable profit.
Owner-operator
Value the owner's management, estimating, vendor, and sales work rather than treating it as free.
Use the modeled owner-income total as the ceiling for combined wage and distribution cash, not as two separate pots.
If payroll tax on owner wages is not already modeled, reduce safe cash further.
Keep working capital and warranty reserves in the company before approving distributions.
Manager-run ownership
A passive owner must replace the owner's operating work with paid management.
A $90,000 to $120,000 manager salary plus payroll burden is a planning assumption that can materially reduce distributions.
Do not call an owner distribution passive income while the owner is still selling, estimating, scheduling, and supervising crews.
Measure passive return after replacement management, debt, reserves, and maintenance capital.
Six income drivers that decide solar installer owner income
Owner income comes from converting qualified demand into completed, collected projects at enough contribution to fund labor, overhead, financing, and reserves. SEIA's 2025 standard emphasizes contractor qualifications, design, installation, quality management, and inspection in its residential and small-commercial installation requirements, making quality control an economic issue as well as a compliance issue.
1. Completed installations and contract value
Turn signed demand into completed monthly revenue
The cleanest revenue unit for this operating model is a completed residential system. EnergySage's 2026 data puts the average quoted system near 12 kW and about $31,135, which is why the base case uses nine roughly $31,200 jobs per month. Here's the quick math: nine jobs produce $280,800 of monthly revenue; seven jobs at the same ticket produce only $218,400, slightly below the model's roughly $219,643 operating break-even. That two-job difference can move the business from owner-pay capacity to no safe residual even before a major warranty claim.
Do not confuse bookings with revenue capacity. A backlog can look excellent while completed systems lag because of roof readiness, electrical upgrades, inspection reschedules, or utility timing. The owner should manage signed contracts, permit-ready jobs, install-ready jobs, completed jobs, and collected jobs as separate stages.
Track completion velocity, not just leads
Use a weekly pipeline bridge that shows how many projects moved forward and why others stalled.
Completed systems per crew-week
Installed kW per month
Average contract value and $ per watt
Cancellation and reschedule rate
Owner income improves when extra signed work actually clears the operational bottlenecks and reaches collection.
2. Direct project cost and pre-payroll gross margin
Protect contribution before adding payroll
The base model uses a 56% margin after non-labor direct project costs, meaning those costs consume 44% of revenue. On $280,800 of monthly sales, that is about $123,552 for panels, inverters, racking, wiring and balance-of-system materials, permits, project-specific engineering or subcontracted non-labor charges, and similar items. The margin definition is intentionally different from many installer P&Ls because every employee dollar is modeled later in labor.
Published system prices vary widely by source and system size. Lawrence Berkeley National Laboratory's 2024 Tracking the Sun analysis showed clear economies of scale in residential installed prices, with larger residential systems carrying lower median $ per watt than small systems. That supports using size and mix, not one flat national price, when quoting jobs. A two-point drop in this model's gross margin costs about $5,616 of monthly gross profit at base revenue before any reserve effect.
Estimate margin at the job level
Compare estimated and actual non-labor direct cost on every completed project.
Hardware cost per watt
Permit and engineering cost per job
Change orders and electrical-upgrade leakage
Warranty and rework cost by equipment family
Do not chase volume with discounts unless procurement, design standardization, or lower rework genuinely protects contribution.
3. Crew productivity and payroll load
Make each payroll dollar buy install capacity
Base non-owner payroll is $72,000 a month, about 26% of sales. That line covers the people needed to turn designs into safe completed systems: installation labor, qualified electrical work, project coordination, and office or sales support. BLS wage medians provide a national reference, but the business should budget local employer cost, not just hourly wage, because workers' compensation, payroll taxes, benefits, overtime, paid travel, training, and nonproductive weather days all change the cash burden.
The sensitivity is direct. If payroll increases by $10,000 without increasing revenue or gross margin, profit before reserves falls by $10,000. At the base 24% tax reserve plus 10% reinvestment reserve, the owner's after-reserve cash falls by about $6,600. That can still be a good trade if the added labor creates enough completed systems; it is a bad trade if it merely reduces queue pressure without increasing billable throughput.
Measure crew economics weekly
Pair labor cost with production measures so management can distinguish productive staffing from idle capacity.
Installed kW per field labor hour
Jobs completed per crew-week
Overtime and travel hours
Inspection rework hours
When owner labor is covering a real manager or estimator role, record the role explicitly so the business does not appear profitable only because the owner's time is free.
4. Customer acquisition and sales conversion
Pay for installable customers, not activity
The base case spends $22,000 a month on marketing, about 7.8% of revenue. That is a reasoned planning assumption covering paid leads, referral economics, local events, digital demand generation, and sales-channel costs that are not wages. Residential solar is unusually sensitive to customer acquisition because the installer must identify a homeowner who is qualified, willing to buy, suitable for the product, and able to move through permitting and financing. NREL research described customer acquisition as the largest portion of residential solar soft cost and found that better targeting could reduce acquisition cost by 15%, or about $0.07 per watt, in the study setting.
Quick math: if base marketing rises from $22,000 to $32,000 and the business still completes nine projects, the extra $10,000 of spend reduces after-reserve owner cash by about $6,600. If that additional spend adds one more $31,200 project at the base contribution structure without forcing another full crew, it can more than pay for itself. The KPI is therefore acquisition cost per completed, collected installation, not cost per lead.
Follow the funnel to cash
Track conversion stages far enough downstream to see which channels create profitable installations.
Lead to appointment rate
Appointment to signed contract rate
Signed contract to install rate
Marketing cost per completed job
Separate referral, organic, marketplace, dealer, and paid-search economics. A cheap lead source can be expensive if cancellations and site disqualifications are high.
5. Permit-to-cash timing and working capital
Finance the gap between buying and collecting
Solar's cash cycle can be longer than its installation time. The crew may finish a roof in days, but design approval, permits, inspection, interconnection, change orders, and customer financing can extend the overall process. In the base month, the model carries about $123,552 of non-labor direct project cost plus $72,000 of payroll before counting overhead and marketing. If supplier invoices arrive earlier than final customer cash, even one month of timing mismatch can create a six-figure liquidity requirement.
This is why safe distribution is not the same as accounting profit. A project can be profitable on paper while the company has cash committed to the next batch of modules and payroll. The owner's reinvestment reserve is only $3,425 in the static base month because it is a percentage of positive profit, so a startup or fast-growing installer should also fund an opening working-capital reserve separately.
Build a 13-week cash view
Use actual payment dates rather than monthly accounting averages when deciding whether cash can leave the company.
Customer deposits and milestone receipts
Supplier deposits and invoice due dates
Weekly payroll and debt payments
Permit, inspection, and PTO status
Delay owner draws when committed cash is needed to finish sold work. A strong backlog is not a cash reserve.
6. Debt, reserves, and the owner's operating role
Separate profit from spendable owner cash
The base model produces $34,248 of monthly profit before reserves. It then sets aside $8,220 for the modeled tax reserve and $3,425 for reinvestment, leaving $22,603 of owner income. Debt service of $6,000 has already been deducted before that point. This sequence matters: revenue is not income, gross profit is not EBITDA, accounting profit is not necessarily distributable cash, and owner salary is not an extra distribution simply because both labels appear on a tax return.
The owner-role decision changes the economics. In the base case, the owner is active in management. If the company becomes manager-run, add replacement management payroll before calling the remaining owner cash passive. Likewise, if a vehicle or equipment loan is refinanced, model the actual monthly principal-and-interest payment rather than treating depreciation as cash. The target is not maximum draw in a good month; it is a distribution policy that survives a weak month, a warranty event, or two delayed installs.
Approve owner cash only after four tests
Use a monthly distribution gate that protects operations before money leaves the business.
Debt and payroll are fully funded.
Committed project materials are covered.
Tax and reinvestment reserves are funded.
Replacement management is recognized if the owner steps back.
In the base case, $22,603 is the modeled monthly owner-income output. Treat it as a planning ceiling for combined owner compensation, not a guaranteed check.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.