

Revenue and Calc
Edit homeowner inquiries, conversion, package mix, installed prices, and launch timing. Monthly calculations allocate one project pool across exclusive contracts.


The Solar Panel Installation Financial Model is an Excel template for building 2026–2030 financial projections for a local residential rooftop solar and battery contractor. It turns homeowner inquiries, completed-project conversion, five installation packages, and contract prices into a monthly revenue forecast.
The illustrative case serves the Charlotte, North Carolina metro area with customer-funded turnkey projects, external installation crews, an owned survey van, and a small warehouse and office. It models contractor operations rather than electricity sales, customer lending, or ownership of leased solar systems.
The workbook links solar installation demand and pricing assumptions to monthly operating calculations, financial statements, funding schedules, and management reports.
Edit homeowner inquiries, conversion, package mix, installed prices, and launch timing. Monthly calculations allocate one project pool across exclusive contracts.
Build hardware, subcontracted crews, marketing, overhead, and internal staffing. External installers count as direct costs, not duplicate payroll.
Adjust working-capital days, Low/Base/High multipliers, and optional debt inputs. Compare scenario revenue, margins, and EBITDA.
Review the projected income statement, cash flow statement, and balance sheet separately from the illustrative operating EBITDA.
Use CAPEX, CapTable, Debt, Sources & Uses, Returns, and Valuation to examine investment, funding, break-even, payback, ROIC, and DCF.
Monthly qualified homeowner inquiries multiplied by the completed-project conversion rate determine one installation demand pool, which is split across five contract packages.
In 2026, 45 monthly inquiries at 16% conversion produce 7.2 expected completed projects per month. By 2030, 85 inquiries at 20% conversion imply 204 annual project equivalents.
Each project has one package; shares total 100%. There is no capacity cap, seasonality, or backlog schedule. The January 31, 2026 launch activates the full January month.
The Revenue Forecast ties homeowner inquiries and conversion rates to completed job equivalents, then applies package mix and full installed contract prices. Its yearly totals connect to the Calc monthly calculations and the projected operating results.
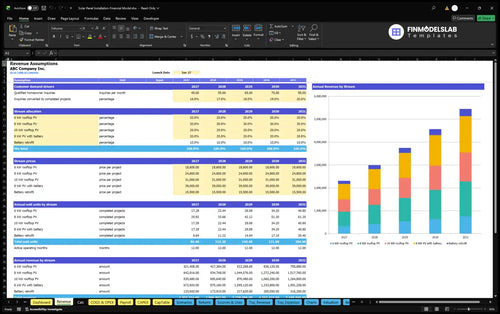
| Installation package | Project share | Price per job |
|---|---|---|
| 6 kW rooftop PV | 20% | $18,600 |
| 8 kW rooftop PV | 30% | $24,800 |
| 10 kW rooftop PV | 20% | $31,000 |
| 8 kW PV with battery | 20% | $39,000 |
| Battery retrofit | 10% | $15,500 |
All prices and shares are selected planning estimates, not observed local transaction averages.
45 inquiries/month × 16% conversion × 12 months × $26,710 weighted installed price = $2,307,744 annual revenue.
Change inquiry volume, conversion, package mix, or prices to test revenue. More battery-inclusive jobs increase the weighted contract price without counting a homeowner twice.
Operating expenses combine revenue-based direct job costs, revenue-based variable expenses, scheduled monthly fixed overhead, and annual-average internal payroll.
COGS equal 66% of revenue: 42% hardware, 21% external installation and electrical crews, and 3% engineering, permits, and inspections.
Variable expenses equal 10.5% of revenue: 6.5% marketing, 2% referrals, 1.5% callbacks, and 0.5% transaction fees. They move with sales.
The COGS and Operating Expenses forecast separates hardware and subcontractors from variable acquisition expenses and fixed overhead. Monthly calculations show how these assumptions affect gross and contribution margins.
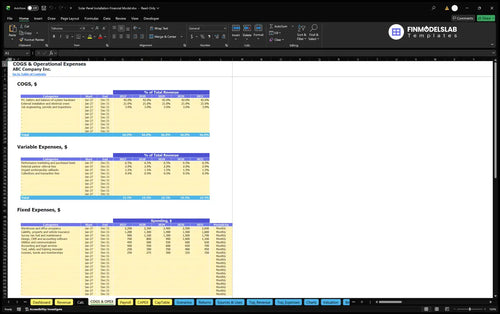
Fixed overhead covers occupancy, insurance, vehicle upkeep, software, professional services, and tools. Monthly rent rises from $2,200 in 2026 to $2,600 in 2030; total annual fixed costs increase from $77,400 to $109,800.
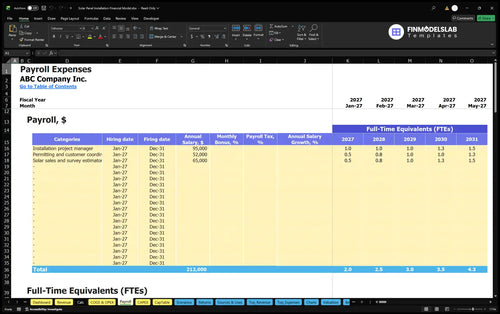
Internal payroll covers a project manager, permitting coordinator, and solar sales and survey estimator. Annual-average FTE grows with demand; subcontracted field crews stay in COGS.
The Payroll Forecast organizes internal FTE, base salaries, and monthly personnel expenses. Selected annual payroll grows from $153,500 in 2026 to $305,000 in 2030; employer taxes and benefits are excluded from this case.
Opening assets, prelaunch cash spending, working capital, and initial owner funding are separate from recurring operating expenses and projected EBITDA.
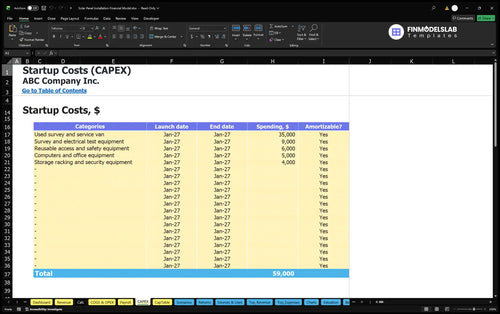
Startup assets include a $35,000 survey van, $9,000 test equipment, $6,000 safety and access equipment, $5,000 office equipment, plus storage racking and security.
Other opening cash covers deposits, formation, website setup, training, and preopening contractors. These items are separate from annual recurring costs.
The Capital Expenditure Plan schedules van, equipment, and other asset purchases. Its depreciation and book-value calculations support financial statements; purchase cash outlays remain distinct from EBITDA.
Working capital assumes 6 receivable days, 13 payable days, and 9 inventory days. The $599,789 owner funding estimate covers opening assets, prelaunch spending, working capital, and three months of recurring expenses.
The Sources and Uses of Funds report tracks funding and operating, investment, and financing payments. CapTable handles equity, and optional Dashboard debt controls drive loan schedules; external borrowing is not confirmed.
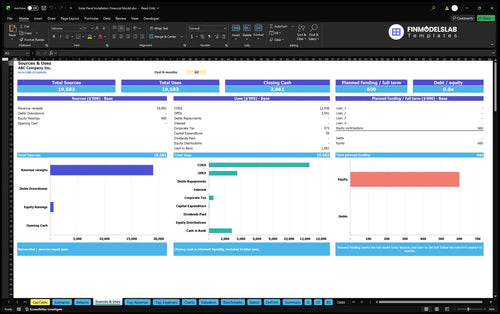
In the selected 2026–2030 contractor case, projected annual revenue, operating expenses, and EBITDA follow the specified demand, pricing, cost, and staffing inputs.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $2,307,744 | $1,996,324 | $311,420 |
| 2027 | $2,996,862 | $2,560,849 | $436,013 |
| 2028 | $3,750,084 | $3,174,414 | $575,670 |
| 2029 | $4,567,410 | $3,847,769 | $719,641 |
| 2030 | $5,448,840 | $4,583,163 | $865,677 |
Example forecasts, not historical results or industry averages. Whole-dollar display rounding may produce minor arithmetic differences.
Illustrative EBITDA grows from $311,420 in 2026 to $865,677 in 2030 as job volume rises. It does not establish net profit, taxes, debt capacity, or cash sufficiency.
The IS, CF, BS, Summary, Charts, and Ratios reports support further analysis. The table shows only the documented operating outputs for this case.
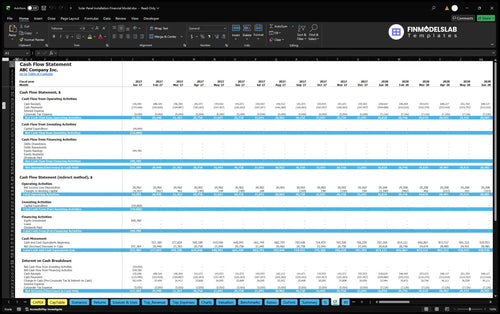
The Cash Flow Forecast tracks operating receipts and payments alongside investing and financing cash movements. It helps assess the timing of homeowner collections, supplier payments, capital purchases, and owner or lender funding that EBITDA alone cannot describe.
The workbook supports separate analyses of operating break-even, cash break-even, investment recovery, return on invested capital, and financing sensitivity.
Sales break-even tests operating cost coverage; cash break-even considers liquidity timing. Investment payback uses cumulative project cash flow, and annual ROIC compares returns with invested capital. None equals EBITDA margin.
The Returns analysis presents break-even, cumulative project cash flow, investment payback, and annual ROIC as distinct measures. For this solar contractor, it helps test whether installation volumes, pricing, and upfront investment can support a desired funding and return profile.
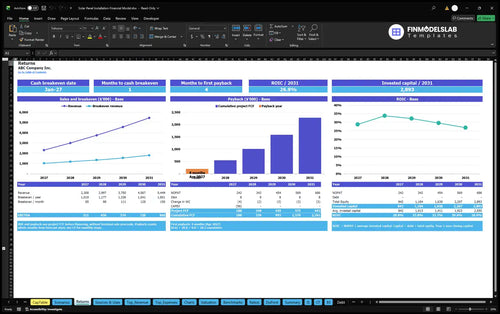
Low/Base/High scenarios test revenue and expense sensitivity. Valuation includes DCF tools, but the case provides no verified payback date, ROIC, IRR, or valuation amount.
Answers to common questions about the contractor revenue logic, editable assumptions, financial reporting, and illustrated results.
It multiplies qualified homeowner inquiries by the completed-project conversion rate, then applies the launch month and allocates the resulting projects across five exclusive packages.
Yes. Edit installed contract prices and project shares for 6 kW, 8 kW, 10 kW, PV-plus-battery, and battery retrofit packages.
No. External installation and electrical crews are included in direct costs; Payroll covers the internal manager, coordinator, and sales and survey estimator.
No. Revenue comes from homeowner-funded installation contracts; power generation sales, owned leases, PPAs, and customer financing are outside the case scope.
No. EBITDA is an operating measure; the income statement and cash flow statement separately analyze depreciation, financing, accounting profit, and cash movement.
Yes. The Dashboard supports optional debt facility inputs and CapTable tracks equity contributions, but the illustrated startup case confirms no external financing.
No. Its annual EBITDA is illustrative; examine the separate cash flow, break-even, payback, and ROIC reports under your own operating and funding assumptions.
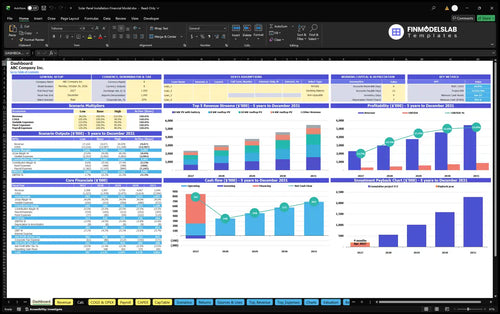
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
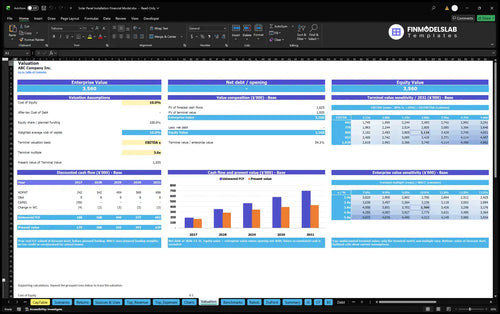
DCF valuation and sensitivity analysis.
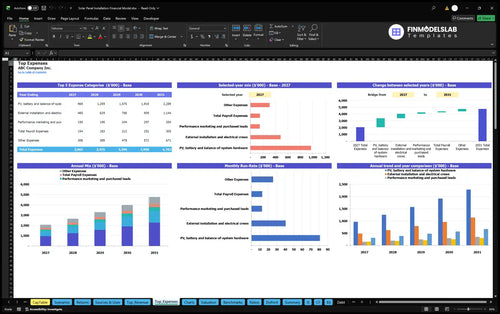
Largest costs and spending trends.
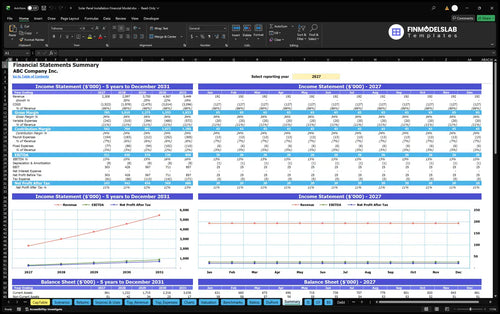
Annual and monthly financial performance.
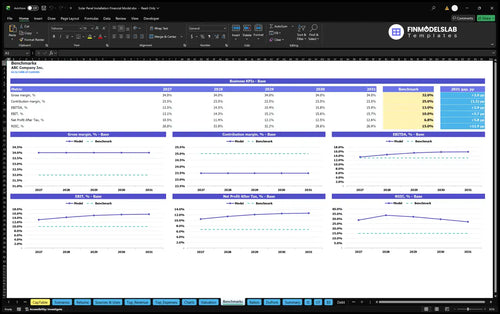
Compare margins and returns to benchmarks.

Building the solar install model by hand would’ve eaten up days. This template cut the setup down to a few hours, so I could move straight to pricing and bids.
I wasn’t sure what investors would expect, but the layout made it obvious. I booked a meeting the same day because the model was already organized the way I needed.

Pricing, equipment costs, and growth were all over the place before this. The assumption tabs pulled everything into one place, and I could finally test changes without breaking the model.