

Revenue and Calc
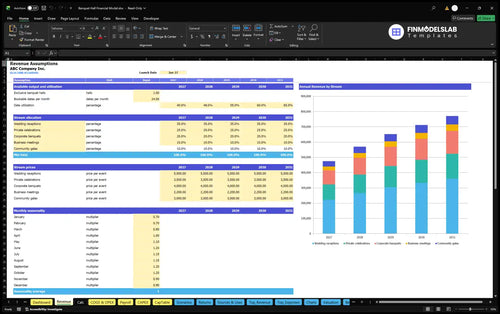
Set bookable dates, utilization, seasonality, five event categories, and package fees. Calc builds monthly revenue without double-counting bookings.


The Banquet Hall Financial Model is an Excel template for planning venue rental revenue, event-related costs, staffing, startup investment, and financial projections from 2026 through 2030. It converts available event dates, booking utilization, seasonal demand, and event-package prices into a monthly forecast.
The example is a leased, 6,500-square-foot Indianapolis-area banquet hall with 250 planned seats. Each available date can be booked by only one event; the venue provides tables, chairs, standard AV, setup, and ordinary cleaning—not catering or alcohol.
The workbook connects bookings to monthly calculations and financial statements.
Set bookable dates, utilization, seasonality, five event categories, and package fees. Calc builds monthly revenue without double-counting bookings.
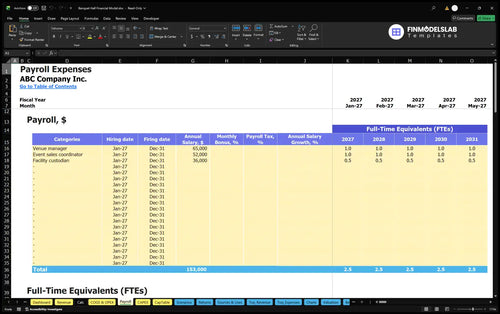
Separate event costs from building overhead and Payroll salaries for the manager, sales coordinator, and part-time custodian.
Plan leasehold improvements, equipment, equity contributions, and optional debt schedules without assuming this example includes borrowed funds.
Review Income Statement, Cash Flow, Balance Sheet, Summary, and model reconciliation checks.
Compare Low, Base, and High scenarios, plus break-even, payback, ROIC, valuation sensitivity, and KPI reports.
A single exclusive hall generates revenue by booking available dates, allocating each sold date to one event category, and applying the category’s venue-package fee.
The Base case assumes 24 bookable dates monthly and 40% utilization in 2026, rising to 48%, 55%, 60%, and 65% by 2030. Monthly seasonality factors repeat each year and sum to 12.
Wedding receptions represent 35% of bookings at $5,500 each; private celebrations 25% at $3,500; corporate banquets 20% at $4,000; business meetings 10% at $2,200; and community galas 10% at $3,000. The weighted package fee is $4,120 per modeled booking.
The Revenue Forecast connects available event dates, utilization, seasonal patterns, category allocation, and package fees to annual venue rental sales. Its monthly calculation uses one shared pool of sellable dates, rather than separately assuming full capacity for each event category.
1 hall × 24 dates/month × 12 seasonality-adjusted months × 40% utilization × $4,120 weighted package fee = $474,624.
Operating expenses distinguish revenue-linked servicing and booking charges from recurring premises costs and salaries paid through the Payroll schedule.
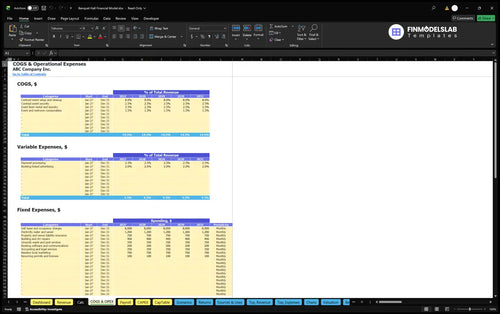
Direct COGS total 14.5% of revenue: setup and cleanup 8%, security 2.5%, linen 2.5%, and consumables 1.5%. Other variable expenses are processing at 2.5% and booking-linked advertising at 2%.
Fixed overhead totals $144,000 annually, including rent, utilities, insurance, repairs, grounds services, software, professional fees, marketing, and permits. Lease and occupancy cost $8,000 per month.
The COGS and Operating Expenses forecast separates direct event costs, variable booking charges, and fixed overhead. Adjusting rates and bills changes operating margins without counting payroll twice.
| Cost group | Basis | 2026 | 2030 |
|---|---|---|---|
| Direct COGS | 14.5% of revenue | $68,820 | $111,833 |
| Variable expenses | 4.5% of revenue | $21,358 | $34,707 |
| Fixed overhead | Monthly budgets | $144,000 | $144,000 |
| Payroll | Role salaries | $135,000 | $135,000 |
Whole-dollar figures are rounded from the model projections; staff salaries are not included in the other cost groups.
The Payroll Forecast budgets one venue manager at $65,000, one event sales coordinator at $52,000, and a 0.5-FTE facility custodian at a $36,000 full-time annual base. Together these positions generate $135,000 in annual base payroll under the illustrated staffing plan.
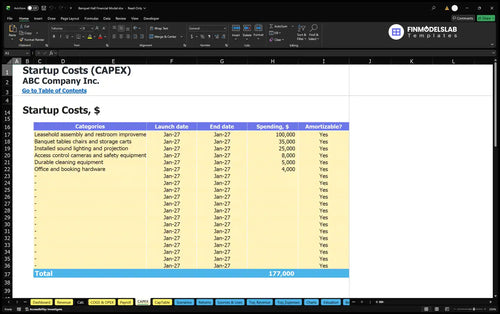
The startup budget identifies hall fit-out, durable equipment, preopening cash expenditures, initial working capital, and owner funding outside ordinary operating expenses.
Startup assets total $177,000, including $100,000 for leasehold improvements, $35,000 for furnishings, $25,000 for installed AV, $8,000 for access and safety equipment, plus cleaning and booking hardware.
Opening cash of $55,250 covers deposits, permits, setup, marketing, and training. These opening payments are separate from the illustrative annual operating expense forecast.
The Capital Expenditure Plan schedules hall improvements and equipment purchases, with depreciation and book-value calculations. These investments remain separate from event servicing and recurring venue expenses.
Initial owner funding is approximately $324,837, covering startup assets, opening cash, about $293 in net working capital, and an approximately $92,295 reserve. The reserve represents three months of first-year recurring cash outflows, not proof that future cash balances will remain positive.
Working capital uses 0 receivable days, 2 payable days, and 3 inventory days. The documented funding includes no committed external debt.
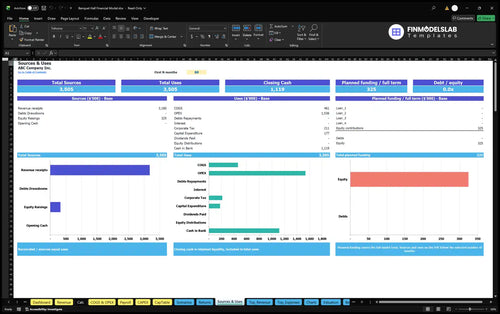
The Sources and Uses of Funds report tracks owner equity, optional debt, investment outflows, operating payments, and retained cash. Equity contributions are funding, not earned revenue or EBITDA.
The following Base-case projections translate rising event-date utilization into revenue and deduct direct costs, variable expenses, fixed overhead, and payroll to reach EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $474,624 | $369,179 | $105,445 |
| 2027 | $569,549 | $387,214 | $182,335 |
| 2028 | $652,608 | $402,996 | $249,612 |
| 2029 | $711,936 | $414,268 | $297,668 |
| 2030 | $771,264 | $425,540 | $345,724 |
Source calculations use unrounded values. Display rounding can create a $1 difference between revenue, operating expenses, and EBITDA.
At 40% utilization, 2026 projects $474,624 in revenue and $105,445 in EBITDA after $369,179 of operating expenses. At 65% utilization, 2030 projects $771,264 of revenue and $345,724 of EBITDA with unchanged package prices and staffing.
EBITDA is an operating measure before depreciation, financing costs, and taxes. It is neither net profit nor cash generated, and the example does not establish actual demand, venue permissions, financing availability, or future returns.
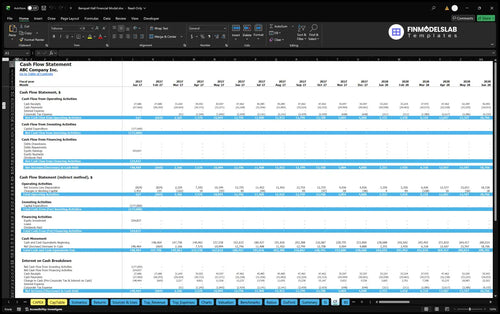
The Cash Flow Forecast tracks operating, investing, and financing movements. Compare it with EBITDA to examine liquidity timing, opening investment, and capital requirements rather than mistaking operating earnings for cash on hand.
The Returns and scenario reports help evaluate operating coverage, capital recovery, and return measures without treating an EBITDA forecast as a verified investment outcome.
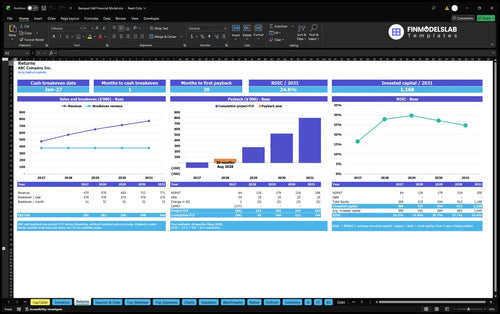
The Returns report separates sales break-even from cash break-even. Payback measures recovery of invested funds using project cash flows; annual ROIC evaluates modeled returns relative to invested capital.
Low, Base, and High scenario controls vary revenue, direct costs, other variable expenses, fixed overhead, and payroll. Compare their EBITDA and margin outcomes, then review cash flow, debt assumptions, and valuation sensitivity before interpreting investment risk.
The Break-Even, Payback and ROIC analysis supports review of revenue coverage, project cash-flow payback, and return on invested capital as separate questions. No specific payback period or ROIC result is established by the supplied banquet hall operating scenario.
Answers to common questions about the template, operating case, cash planning, and report interpretation.
Yes. Edit available dates, annual utilization, recurring seasonality, category allocations, and event-package prices to rebuild monthly and annual venue revenue.
No. The example sells exclusive venue packages only; customers arrange catering and beverage service directly with licensed providers.
No. The documented case allocates each sold date once across five event categories and assumes no simultaneous subdivision.
No. The example budgets salaried staff separately through Payroll and excludes their base compensation from direct, variable, and fixed cost categories.
The workbook includes Cash Flow, Income Statement, and Balance Sheet reports, but the supplied annual example establishes operating revenue, expenses, and EBITDA—not a verified cash balance.
No. The illustrated opening funding is owner-provided; Debt controls are available for optional financing scenarios.
No. Payback depends on project cash flows and invested capital; EBITDA alone does not establish a payback date or return percentage.
No. The leased venue is hypothetical, and capacity, assembly permissions, and vendor permissions require independent site-specific confirmation.
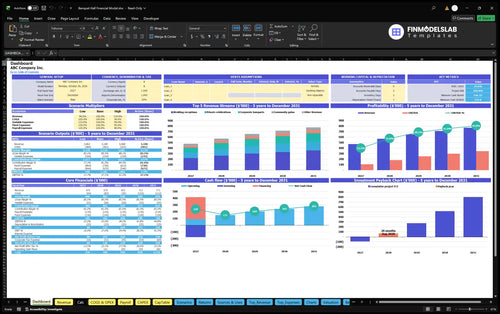
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
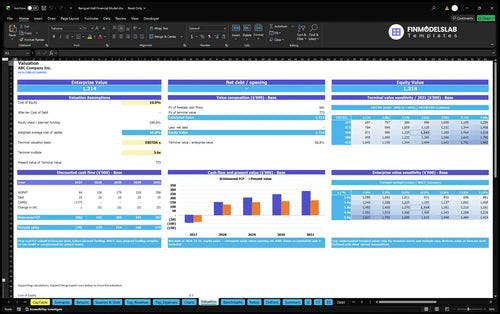
DCF valuation and sensitivity analysis.
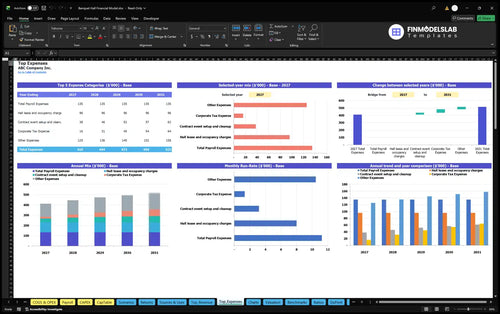
Largest costs and spending trends.
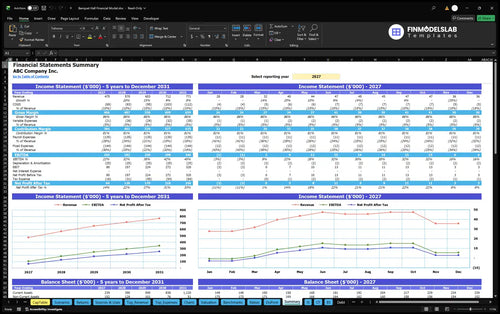
Annual and monthly financial performance.
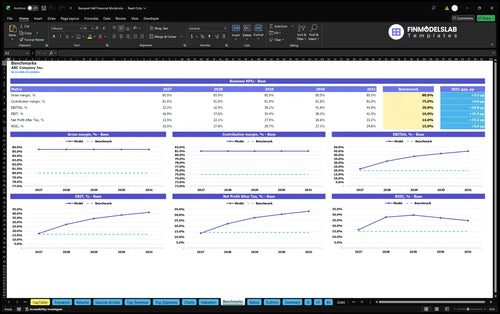
Compare margins and returns to benchmarks.

I’m not strong in Excel, so advanced modeling usually slowed me down. This template made the tabs and formulas easier to follow, and I saved about 6 hours I would have spent guessing my way through the setup.
Switching between low, base, and high cases was usually a mess for me. Here, the assumptions were organized clearly, and I could compare all three in one sitting instead of spending half a day rebuilding the file.

I had trouble seeing when the runway would tighten, but this model made the shortfalls much clearer. It helped me spot a funding gap early and prepare for lender questions with fewer last-minute revisions.