

Revenue and Calc
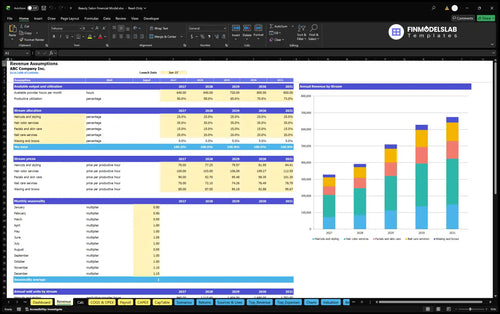
Set provider hours, utilization, hourly prices, service-hour shares and seasonality. Calc allocates one sold-hours pool across the five services each month.


The Beauty Salon Financial Model is an Excel planning template for a salon offering hair, color, facials, nails and waxing. It converts provider capacity, utilization, hourly pricing and service mix into monthly sales and a five-year operating forecast.
The example models an owner-managed salon in a secondary Texas suburban market, launched January 31, 2026 and forecasting 2026–2030 in nominal US dollars. Assumptions are editable estimates, not historical salon results or guaranteed outcomes.
Edit operating drivers once, then review the supporting calculations and connected management reports.
Set provider hours, utilization, hourly prices, service-hour shares and seasonality. Calc allocates one sold-hours pool across the five services each month.
Plan consumables, laundry, transaction fees and overhead separately from provider and reception FTE, base salaries and monthly payroll.
Schedule opening equipment, equity contributions and optional borrowing while separating investing and financing from recurring operations.
Explore income statement, cash flow, balance sheet, scenarios, break-even, payback, valuation, dashboard and checks without inventing report results.
The beauty salon revenue forecast multiplies utilized provider capacity by a weighted realized service rate, with monthly seasonality applied to activity.
The 2026 case assumes 640 available provider hours monthly and 50% utilization, producing 320 sold hours before seasonality. By 2030 the plan increases to 800 available monthly hours and 73% utilization.
Hour allocation is 25% haircuts, 35% color, 15% facials, 20% nails and 5% waxing. Together they equal 100%, so a provider hour cannot generate duplicate service sales.
The Revenue Forecast shows provider hours, utilization, service mix and realized hourly prices. Calc applies launch timing and monthly seasonality before consolidating the five sales streams.
| Service | Sold hours | Price per hour |
|---|---|---|
| Haircuts and styling | 25% | $75 |
| Hair color services | 35% | $100 |
| Facials and skin care | 15% | $90 |
| Nail care services | 20% | $70 |
| Waxing and brows | 5% | $85 |
Percentages allocate the same productive-hours pool; prices are estimated realized rates, not market benchmarks.
640 available hours/month × 50% utilization × 12.0 combined monthly seasonal factors × $85.50 weighted hourly price = $328,320 projected 2026 revenue.
The model calculates sales-linked salon expenses independently of monthly overhead and salaried provider and reception staffing.
COGS comprise consumables at 12% of revenue, laundry at 2% and supply freight at 0.5%. Variable expenses include payment processing at 2.8%, sales-based advertising at 2%, waste disposal at 0.2% and 0% credit losses.
Fixed expenses cover occupancy, utilities, software, insurance, administration, marketing, cleaning, maintenance and licensing. Estimated monthly salon rent rises from $3,600 in 2026 to $4,052 in 2030.
The COGS and Operating Expenses Forecast separates revenue-based service costs from scheduled overhead. It feeds monthly cost and margin calculations without mixing salaries into COGS.
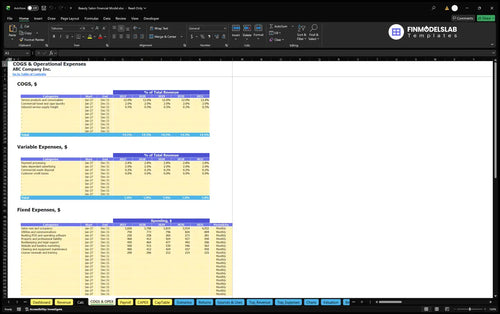
In 2026, the case budgets $47,606 COGS, $16,416 variable expenses and $78,600 fixed expenses, excluding payroll. Salaries are accounted for only in the payroll category.
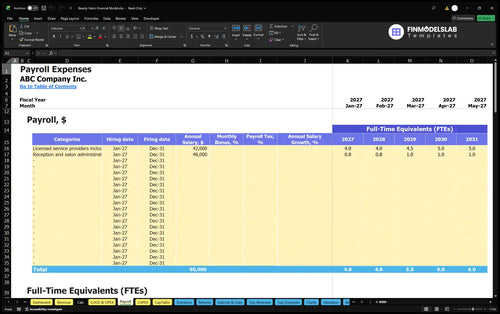
Annual 2026 payroll is $204,000: four licensed-provider FTE, including the owner, at $42,000 each, plus 0.75 reception FTE at $48,000 per full-time role. By 2030 staffing reaches five providers and one receptionist.
The Payroll Forecast tracks service-provider and reception FTE, salary assumptions and monthly personnel costs. Estimated base payroll increases from $204,000 in 2026 to $258,000 in 2030.
Separate initial salon setup, working-capital settings and owner contributions from recurring operating performance.
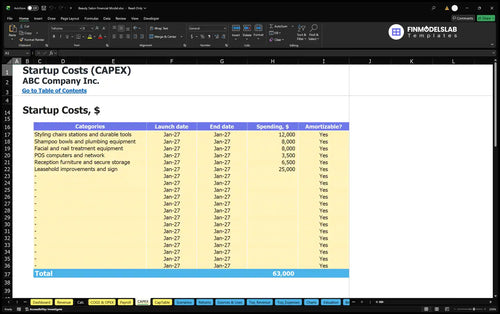
Four itemized opening assets total $31,500: styling stations $12,000, shampoo equipment $8,000, facial and nail equipment $8,000, and POS/network equipment $3,500. Reception furniture, storage, leasehold improvements and signage are additional assets.
Other opening cash costs cover permits, refundable rent deposit, website, launch marketing and preopening training. The CAPEX schedule separates asset investment and depreciation from ongoing operating costs.
The Capital Expenditure Plan schedules equipment and other asset purchases and calculates depreciation and net book value. These startup expenditures differ from supplies consumed during client services.
The case specifies $170,775 initial owner funding, estimated from setup items, physical working capital, opening cash and a three-month recurring-cost reserve. No new borrowing is assumed, but the Dashboard permits optional debt modeling.
Working-capital inputs are zero receivable days, 12 payable days and 25 inventory days. They affect modeled cash timing but do not establish whether future cash balances are sufficient.
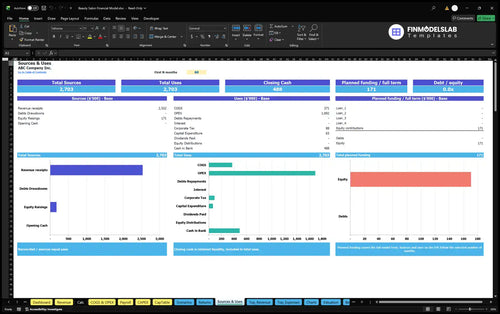
The Sources and Uses of Funds report compares equity and optional debt sources with operating, investing and financing payments. It distinguishes owner contributions from customer receipts and EBITDA.
The selected planning case shows a first-year operating EBITDA loss followed by positive annual operating EBITDA from 2027.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $328,320 | $346,622 | -$18,302 |
| 2027 | $392,277 | $361,452 | $30,825 |
| 2028 | $509,411 | $419,722 | $89,689 |
| 2029 | $627,826 | $466,315 | $161,512 |
| 2030 | $674,390 | $477,971 | $196,419 |
Estimated scenario results, rounded to whole dollars. Rounded line items may differ slightly from recalculated differences.
Projected revenue rises from $328,320 in 2026 to $674,390 in 2030 as provider utilization, capacity and service prices increase. Operating expenses rise from $346,622 to $477,971.
EBITDA deducts COGS, variable expenses, fixed expenses and payroll from sales. It is not net income, bank cash or owner take-home pay; depreciation, interest, taxes and cash movements differ.
The Projected Income Statement presents sales, costs, margins, payroll and EBITDA before depreciation, interest, taxes and accounting profit. Only the operating results through EBITDA have numeric evidence in this example.
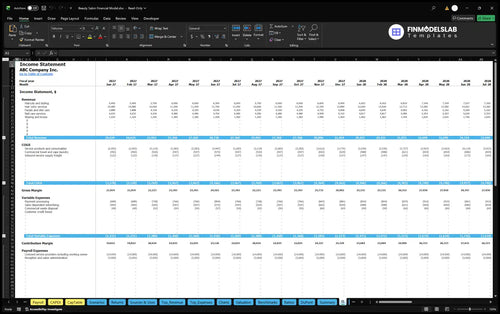
Use Cash Flow and Balance Sheet reports to assess collections, inventory, supplier obligations, investment and financing. This example supplies no ending cash or balance-sheet figures.
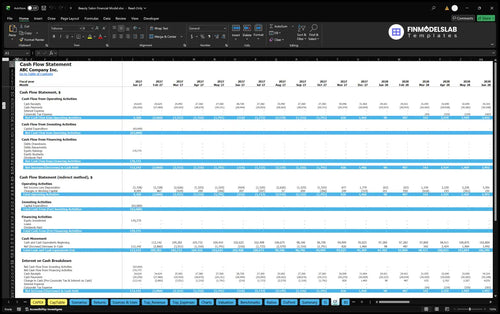
The Cash Flow Forecast separates operating receipts and payments from equipment investment and financing flows. Its opening-to-closing cash reconciliation supports liquidity planning, which is not equivalent to EBITDA.
Returns and scenario reports provide different decision views; their results depend on the assumptions entered.
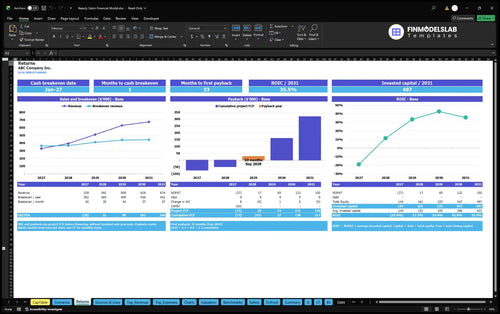
Returns analyzes sales break-even, cash break-even, investment payback and annual ROIC. Covering operating costs is not the same as recovering startup investment or retaining positive cash.
The Break-Even, Payback and ROIC report compares sales with operating break-even and analyzes project cash flow, cumulative payback and annual invested-capital returns. The salon example provides no specific payback or ROIC result.
The Dashboard offers Low, Base and High multipliers for revenue, COGS, variable expenses, fixed expenses and payroll. Compare their effects on sales and EBITDA rather than assuming all conditions will match the Base case.
Other workbook reports support discounted cash flow valuation, KPI benchmarks, financial charts and model checks. Their calculated values are not established by this operating brief.
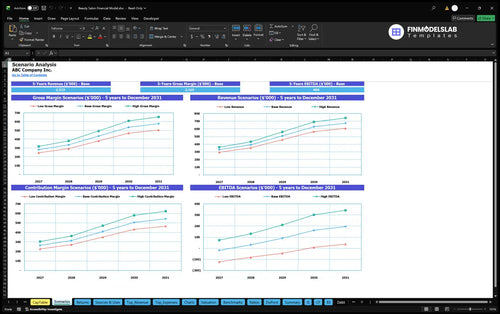
The Financial Scenario Analysis compares Low, Base and High revenue, gross margin, contribution margin and EBITDA. It reveals the effects of changed assumptions without guaranteeing future salon performance.
Answers about editable assumptions, included reports and the limits of the illustrative operating case.
Yes. You can edit provider hours, utilization, monthly seasonality, service mix and realized hourly prices.
Each service has its own hourly rate and allocated share, but all five draw from the same sold-hours pool.
Yes. The 2026 case includes four licensed-provider FTE, including the owner, plus 0.75 reception FTE. Employer taxes and benefits are excluded from the example.
Yes. Monthly income statement, cash flow and balance sheet reports are included, although the brief provides operating forecast values only through EBITDA.
No. Initial funding is estimated at $170,775 from the owner; optional debt controls are available on the Dashboard.
No. EBITDA excludes depreciation, interest, taxes and investment or financing cash flows.
Yes. Returns supports operating break-even, cash break-even, payback and ROIC, but the supplied salon scenario gives no computed return figure.
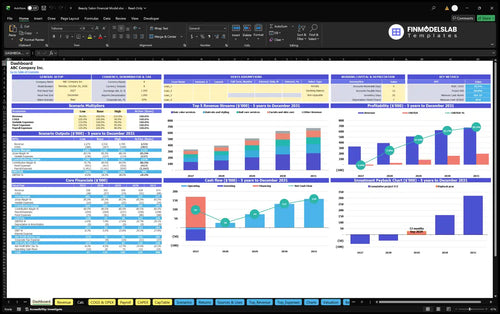
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
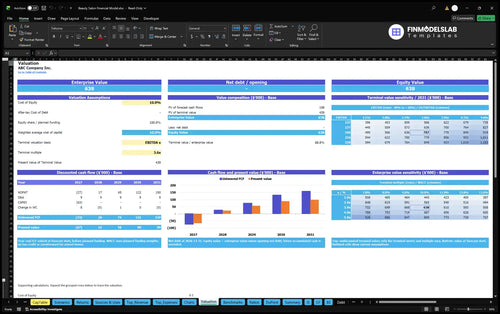
DCF valuation and sensitivity analysis.
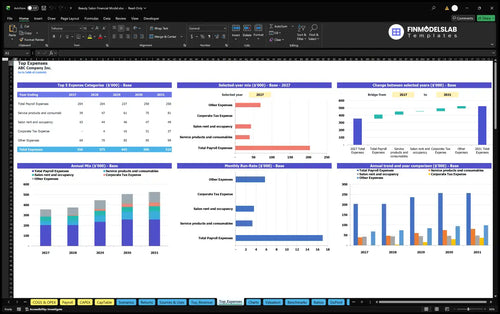
Largest costs and spending trends.
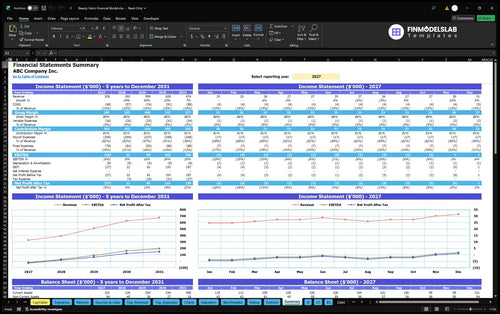
Annual and monthly financial performance.
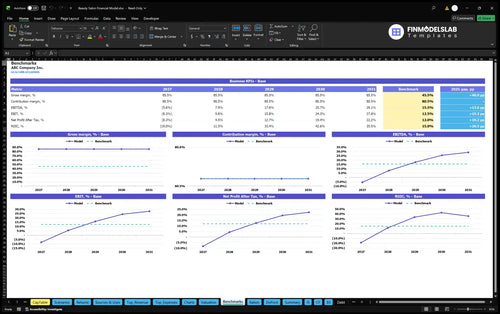
Compare margins and returns to benchmarks.

I stopped hunting through separate files for statements and charts. Everything sat in one place, which saved me hours before my lender call and made the deck much easier to follow.

Switching between low, base, and high cases used to take forever. This template let me compare them quickly, and I booked my planning meeting the same day.
I was nervous one broken formula could throw off the whole model. The built-in checks made the spreadsheet easier to trust, and I spent far less time double-checking cells.