

Revenue and Calc
Plan a single gross-order pool, seasonal demand, wholesale and direct format shares, and retailer ebook sales. Monthly calculations carry operating drivers into the projected revenue totals.


The Book Publishing Financial Model is an Excel template for planning an independent U.S. trade publisher across 2026–2030. It translates book-order demand, channel and format mix, realized prices, production costs, staff salaries, and opening investment into a monthly financial forecast and annual operating projections.
The case covers 8–18 new titles annually plus backlist, outsourced production and fulfillment, and wholesale, direct, and ebook sales. It assumes no author fees or advances; results are illustrative planning estimates.
The workbook connects publishing assumptions to monthly calculations, statements, funding schedules, and reports.
Plan a single gross-order pool, seasonal demand, wholesale and direct format shares, and retailer ebook sales. Monthly calculations carry operating drivers into the projected revenue totals.
Model printing, royalties, distribution, returns, fulfillment, marketing, editing, storage, and staff compensation without charging the same salary in multiple expense categories.
Enter initial equipment purchases, owner equity contributions, and optional financing facilities. The Dashboard provides debt controls, while dedicated schedules record investments, funding and repayments.
Review the Income Statement, Cash Flow Statement, and Balance Sheet for profitability, liquidity, working capital, and financial position.
Compare Low, Base, and High operating scenarios and inspect Returns, Sources & Uses, Valuation, Charts, Benchmarks, and detailed revenue or expense composition reports.
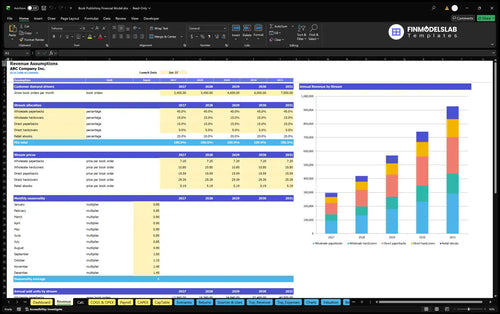
The revenue forecast starts with gross monthly book orders, allocates each order to one mutually exclusive channel or format, and applies its selected realized price.
In the selected Base illustration, gross monthly orders increase from 2,400 in 2026 to 7,500 in 2030. A repeating January–December demand profile reflects weaker months and stronger holiday orders; its 12 monthly factors sum to 12.
The wholesale paperback and hardcover shares are 45% and 15%; direct paperback and hardcover account for 15% and 5%. The remaining 20% belongs to retailer ebooks, so the channels partition demand rather than count the same order twice.
The Revenue Forecast connects gross book demand, seasonal timing, five channel-and-format shares, and realized selling prices to annual sales. Revenue inputs feed Calc, which constructs the month-by-month revenue forecast for the financial statements.
| Sales category | Demand share | Net unit price |
|---|---|---|
| Wholesale paperback | 45% | $7.20 |
| Wholesale hardcover | 15% | $10.80 |
| Direct paperback | 15% | $19.59 |
| Direct hardcover | 5% | $29.39 |
| Retailer ebooks | 20% | $5.19 |
Prices are estimated realized revenue per order after relevant discounts and expected returns; ebook share is the residual of the exclusive demand mix.
2,400 gross book orders per month × 12 months = 28,800 gross orders annually before the format and channel allocation.
Expected book returns reduce recognized sales while printing costs remain incurred. Because the stated net prices already incorporate relevant channel deductions, those same deductions are not added again as separate operating expenses.
The operating forecast separates revenue-linked direct and variable spending from monthly fixed costs and role-based salaries.
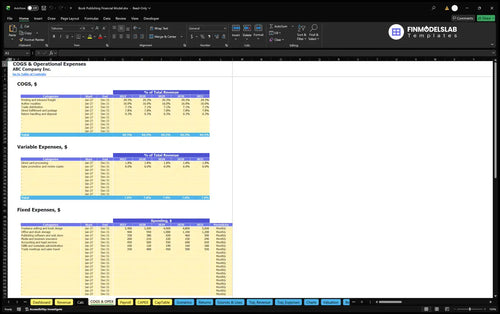
Selected COGS rates are 29.31% for printing and inbound freight, 16.01% for author royalties, 7.07% for trade distribution, 7.76% for direct fulfillment and postage, and 0.35% for return handling. Together, these estimated rates total 60.50% of revenue.
Variable operating expenses add 1.85% for direct card processing and 6% for promotion and review copies. Fixed expenses include freelance editing and design, office and storage, software, insurance, professional services, metadata administration, and sales travel.
The COGS and Operating Expenses forecast organizes production, royalty, distribution, fulfillment, promotional, and fixed expense assumptions. Editable rates and payment schedules flow into monthly costs and influence gross margin, contribution margin, and EBITDA.
The Payroll Forecast models the publisher and managing editor plus the sales and operations coordinator by annual-average FTE and fixed salary. In the example, one $72,000 managing-editor role and 0.5 coordinator FTE at $52,000 produce $98,000 of 2026 base payroll.
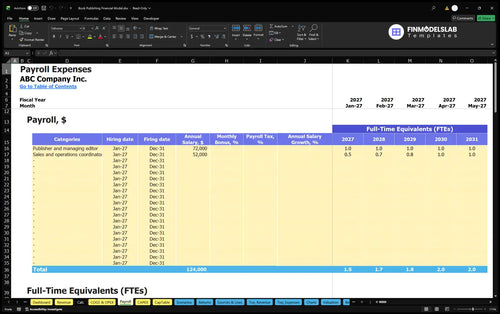
Coordinator staffing rises to one annual-average FTE by 2029, bringing illustrative base payroll to $124,000 in 2030. The source case excludes employer taxes, benefits, and personal taxes, even though standard workbook payroll controls can represent additional compensation components.
For 2026, the selected case records $179,546 COGS, $23,291 variable expenses, $57,000 fixed expenses, and $98,000 payroll. This produces approximately $357,837 of total operating expenses, before comparing the result with sales.
The model tracks publisher setup spending, equipment purchases, working capital assumptions, and owner funding separately from operating revenue and EBITDA.
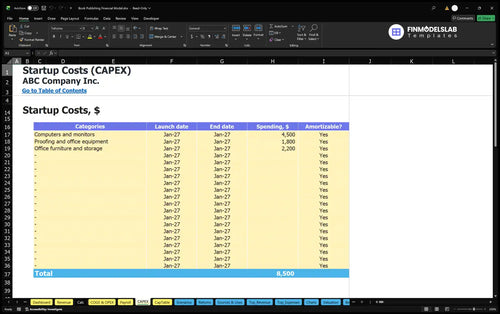
Selected startup equipment comprises $4,500 for computers and monitors, $1,800 for proofing and office equipment, and $2,200 for furniture and storage, for $8,500 in startup assets. Separate opening cash items cover formation, contracts, store setup, deposits, ISBN administration, branding, and launch marketing.
The Capital Expenditure Plan records equipment and other asset purchase dates, amounts, depreciation eligibility, and subsequent book values. It keeps acquisition spending distinct from the publishing operation’s ongoing costs and shows how assets feed financial reporting.
Working capital inputs are 48 accounts-receivable days, 15 accounts-payable days, and 29 inventory days. The example starts with an estimated $157,823 owner contribution, zero committed outside funding, and a funding calculation that includes launch working capital and a three-month expense reserve.
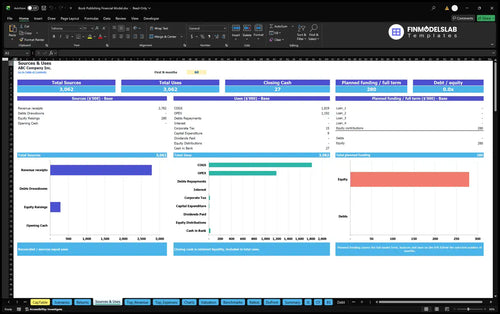
The Sources and Uses of Funds report connects equity, optional debt, customer receipts, operating payments, asset investment, and retained cash. For a publisher with wholesale receivables and physical inventory, it helps trace how funding is allocated rather than treating owner contributions as sales.
The example publisher moves from an operating EBITDA loss in 2026 to positive EBITDA in 2029, assuming the documented increases in orders and selected costs.
| Year | Revenue | Operating expenses | EBITDA |
|---|---|---|---|
| 2026 | $296,772 | $357,837 | -$61,065 |
| 2027 | $420,427 | $462,272 | -$41,845 |
| 2028 | $568,813 | $583,731 | -$14,918 |
| 2029 | $741,930 | $725,292 | $16,637 |
| 2030 | $927,412 | $864,905 | $62,507 |
Illustrative nominal U.S. dollar estimates rounded to whole dollars; minor displayed differences can result from rounding.
Revenue expands as planned gross orders rise and the selected channel prices and mix remain in effect. EBITDA improves from a $61,065 operating loss in 2026 to $62,507 positive EBITDA in 2030, after the stated COGS, variable costs, fixed expenses, and payroll.
This table reports operating EBITDA, not net profit, cash flow, or investment return. The wider workbook contains additional financial statement functions, but the documented case values support only the operating forecast through EBITDA.
The Cash Flow Forecast tracks customer collections, operating payments, capital purchases, equity contributions, and any debt flows through a monthly cash reconciliation. It helps assess cash timing, especially when book sales create receivables or stock purchases precede receipts.
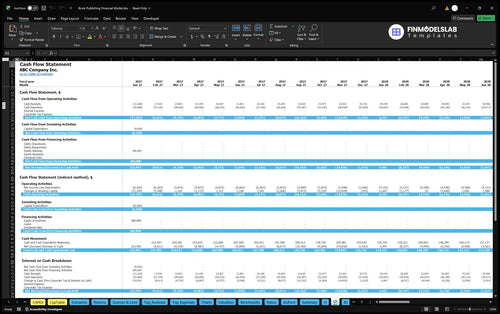
Use the Income Statement to inspect profitability categories, the Balance Sheet to review working capital and financing positions, and the Cash Flow Statement to test monthly liquidity. Do not infer cash sufficiency or an accounting profit figure from the EBITDA row alone.
The standard workbook includes distinct tools for operating break-even, funding needs, investment recovery, and sensitivity to changes in assumptions.
The Returns report distinguishes sales break-even, cash break-even timing, investment payback, and annual return on invested capital. These measures answer different questions about operating coverage, cash recovery, and investment efficiency; no specific payback or ROIC result is supplied in this example.
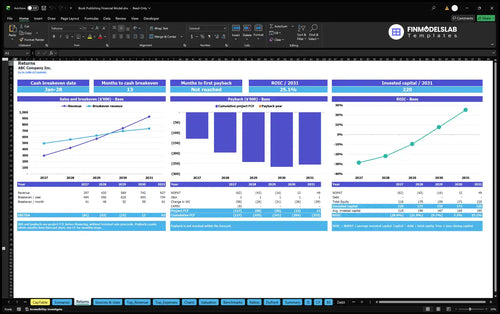
A positive EBITDA year does not itself establish when cumulative project cash flow turns positive. Review the Returns calculations alongside Cash Flow and Sources & Uses to separate operating viability from the amount and timing of cash investors may recover.
The Dashboard offers Low, Base, and High controls for revenue, COGS, variable costs, fixed expenses, and payroll. Changing these multipliers can highlight exposure to weaker book orders, larger print expense, or higher staffing costs.
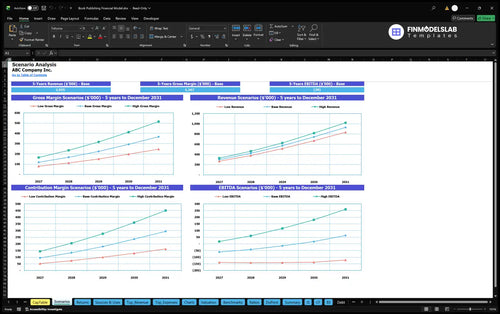
The Financial Scenario Analysis compares Low, Base, and High revenue, gross margin, contribution margin, and EBITDA. It supports testing how changes in demand and cost assumptions alter the publishing model’s operating outlook without claiming a specific outcome for an untested scenario.
Valuation and sensitivity, KPI benchmarks, financial ratios, and financial charts are also declared workbook reports. They provide additional ways to inspect results after inputs are reviewed, but the accompanying operating example supplies no verified valuation, benchmark gap, borrowing terms, or return values.
These answers clarify the assumptions, editing controls, and limits of the example projections.
It models an independent U.S. trade publisher selling wholesale and direct print books plus retailer ebooks, with outsourced production and fulfillment.
Yes. Revenue inputs cover monthly order demand, seasonal factors, format and channel shares, and realized prices.
The supplied illustration assumes no author advances or fees; it includes royalties as a revenue-linked direct cost.
Yes. Expected returns reduce realized revenue, while printing costs remain and return handling is treated as a direct cost.
Payroll is planned by role, salary and annual-average FTE; the illustrated salary amounts are excluded from the other operating cost categories.
No. EBITDA omits working capital, asset purchases, and financing cash flows; review the Cash Flow Statement for liquidity.
The workbook includes equity and debt schedules, Sources & Uses, break-even, cash payback, ROIC, and valuation functions; no specific return is established by this case.
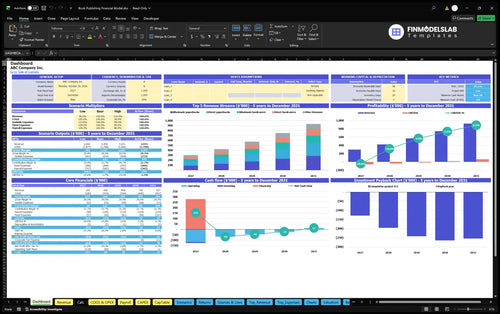
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
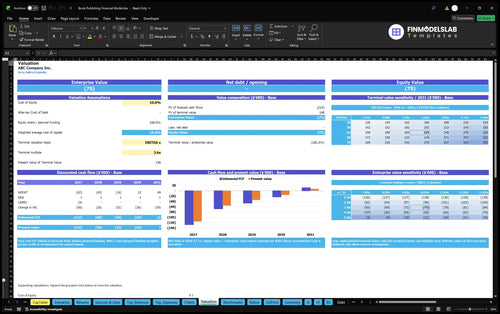
DCF valuation and sensitivity analysis.
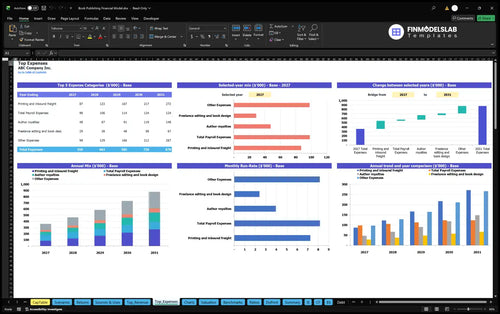
Largest costs and spending trends.
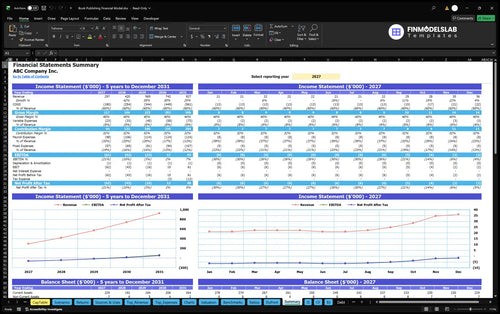
Annual and monthly financial performance.
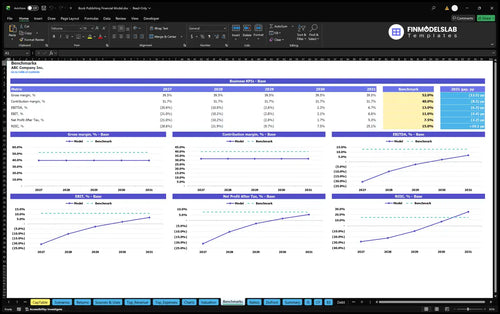
Compare margins and returns to benchmarks.

This template pulled our statements and charts into one place, so I stopped jumping between files. It saved me about 4 hours a week when I needed to share clean numbers with our team.

I’m not an Excel modeler, and this was still straightforward to use. The input tabs made the assumptions clear, and I booked our planning meeting the same day instead of spending hours decoding formulas.
The cash-flow forecast showed our shortfall months before it became a problem, which gave us time to adjust spending. That clarity made it much easier to plan the next 12 months with confidence.