

Revenue and Calc
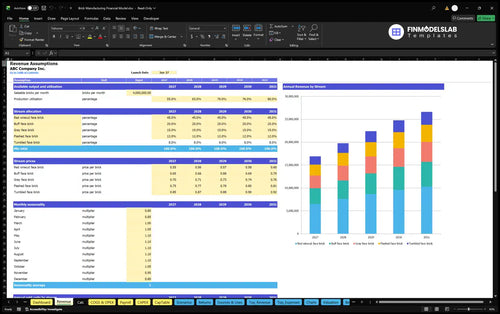
Set kiln and extrusion capacity, utilization, seasonality, product-finish shares and unit selling prices. The monthly Calc schedule assigns shipments across five brick finishes and consolidates revenue.


The Brick Manufacturing Financial Model is an Excel financial planning template for a medium-size facing-brick plant. It connects saleable kiln capacity, production utilization, finish allocation and net ex-works prices to monthly revenue, operating expenses and a five-year forecast for 2026–2030.
The illustrative business leases an industrial shell and yard in South Carolina, buys prepared clay and sells modular facing bricks to regional distributors and construction customers. The modeled plant does not operate a quarry, install masonry or earn reseller revenue.
The workbook combines the specific brick production assumptions with connected operating, financing and reporting schedules.
Set kiln and extrusion capacity, utilization, seasonality, product-finish shares and unit selling prices. The monthly Calc schedule assigns shipments across five brick finishes and consolidates revenue.
Model prepared clay, energy, packaging, consumables, sales costs, plant overhead and salaries separately. Payroll schedules staff roles and compensation without counting salary inside direct operating costs.
Plan installed manufacturing equipment, opening contributions and optional financing facilities. Debt schedules support repayment and interest assumptions entered on the Dashboard.
Review projected income statements, cash flows, balance sheets and reconciliations alongside scenarios, management charts, Sources & Uses, valuation and investment-return analyses.
Revenue is calculated from one shared saleable production pool, allocated across five facing-brick finishes at separate net selling prices.
The plant has 4,000,000 saleable bricks of monthly nameplate capacity. Annual utilization assumptions rise from 55% in 2026 to 80% in 2030, while a repeating monthly seasonal factor adjusts throughput without creating additional capacity.
Shipped bricks are allocated once: 45% red wirecut, 20% buff, 15% gray, 12% flashed and 8% tumbled. Each finish contributes its shipped units multiplied by its annual ex-works wholesale price; outbound freight is arranged by the customer.
The Revenue Forecast organizes production utilization, seasonal shipment factors, finish allocations and selling prices. Its monthly calculations support an annual view of shipped bricks and net ex-works wholesale sales by finish.
26,400,000 shipped bricks × $0.6405 weighted net price per brick = $16,909,200 annual revenue.
The 2026 example uses the full-year seasonal factors, which total 12 monthly capacity equivalents, and the opening mix of selling prices. All streams begin on the January 31, 2026 launch date; the launch month is treated as a full operating month in this case.
Direct production inputs, revenue-linked selling expenses, monthly plant overhead and role-based payroll are modeled as distinct operating cost groups.
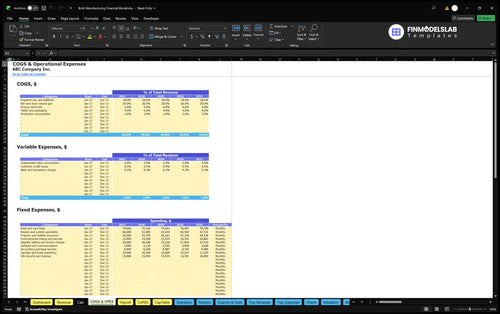
COGS assumptions total 49% of revenue: prepared clay and additives 18%, kiln and dryer natural gas 20%, electricity 4%, packaging 4% and production consumables 3%. Independent commissions, credit losses and transaction charges add 2.8% of revenue as variable operating expenses.
The COGS and Operating Expenses forecast separates percentage-based production and selling costs from recurring fixed plant costs. Lease, maintenance, insurance, environmental testing, standby utilities and other site expenses flow into the operating forecast independently of payroll.
| Expense category | 2026 | 2030 |
|---|---|---|
| COGS | $8,285,508 | $13,044,832 |
| Variable OPEX | $473,458 | $745,419 |
| Fixed OPEX | $2,736,000 | $3,079,392 |
| Payroll | $2,552,000 | $2,552,000 |
These values are illustrative assumptions and outputs; individually rounded categories may not add to the exact underlying totals.
The Payroll Forecast tracks the 45 annual-average full-time-equivalent roles and their salaries, including 24 production operators, four kiln attendants and four maintenance technicians. Fixed base pay is calculated separately from the direct and fixed expense assumptions.
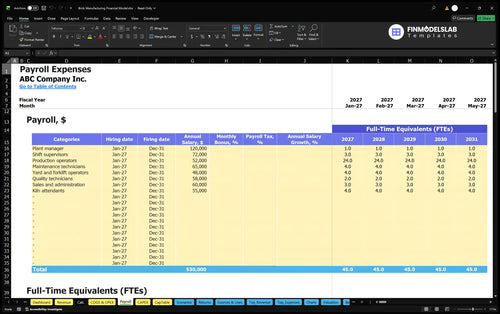
For example, the plant and yard lease is $70,000 per paid month in 2026, or $840,000 for 12 months. Salaries total $2,552,000 annually in the selected case; employer taxes, benefits and personal taxes are outside the documented cost scope.
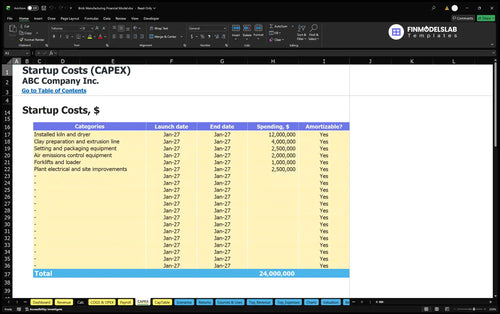
The startup budget separates installed brick-making assets, preopening cash payments, working-capital inputs and contributed owner capital from recurring operations.
Major estimated startup assets include a $12,000,000 installed kiln and dryer, a $4,000,000 clay preparation and extrusion line, $2,500,000 of setting and packaging equipment, and $2,000,000 of air emissions control equipment. Forklifts, a loader and site electrical improvements are additional asset categories.
The Capital Expenditure Plan records manufacturing asset purchases, expenditure dates and depreciation controls. It distinguishes capital investment from the recurring clay, fuel, electricity and payroll costs used to evaluate operating EBITDA.
The working-capital assumptions are 24 receivable days, 13 payable days and 27 inventory days. Separate opening cash items cover the lease deposit, preopening permits and engineering, commissioning labor, training, samples and market launch activities.
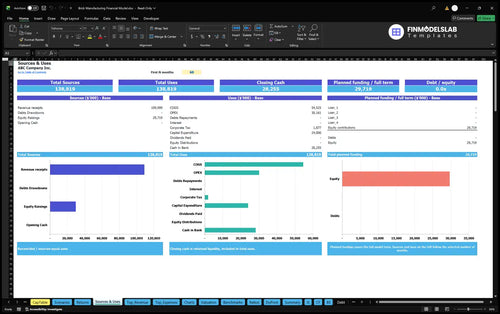
The Sources and Uses of Funds report groups cash sources and cash allocation, including contributions, borrowing, operating uses and asset purchases. It helps review how the estimated owner funding supports plant setup and forecast cash requirements.
The 2026–2030 example shows how the selected production utilization, pricing and operating cost assumptions translate into annual operating EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $16,909,200 | $14,046,966 | $2,862,234 |
| 2027 | $19,756,094 | $15,603,737 | $4,152,358 |
| 2028 | $22,390,200 | $17,052,746 | $5,337,454 |
| 2029 | $24,795,930 | $18,385,993 | $6,409,937 |
| 2030 | $26,622,106 | $19,421,643 | $7,200,463 |
Illustrative financial projections, not historical plant results or industry averages. Rounded display amounts can differ slightly from unrounded calculations.
In the selected model, EBITDA rises from $2,862,234 in 2026 to $7,200,463 in 2030 as modeled utilization and realized prices change. EBITDA is revenue less the listed operating expenses before depreciation, interest and taxes; it is not net profit.
The Cash Flow Forecast brings together cash receipts, operating payments, capital expenditure and financing cash movements. Use it to review liquidity and potential funding gaps separately from the revenue and EBITDA calculations.
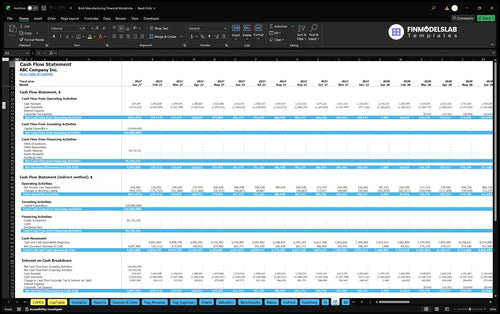
The workbook also supplies projected income statements and balance sheets, but the documented numerical example is limited to operating results through EBITDA. Changing debt, asset lives, working capital and tax settings can affect those other reports without altering the source EBITDA illustration.
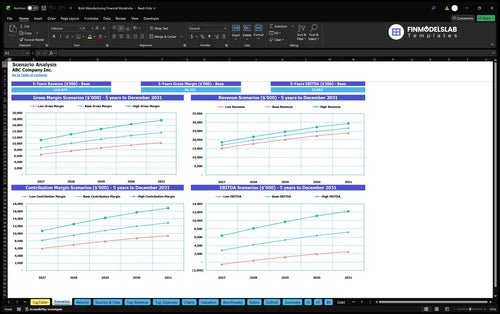
The Financial Scenario Analysis compares Low, Base and High cases for revenue, gross margin, contribution margin and EBITDA. Dashboard multipliers can stress-test changes to selling activity, COGS, variable costs, fixed costs and payroll.
The declared Returns and valuation reports provide distinct ways to examine operating coverage, cash recovery and the financial case for the plant investment.
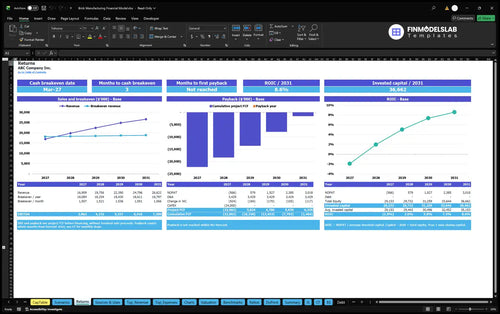
Sales break-even compares revenue against the modeled costs of operation; cash break-even considers when cumulative cash generation reaches the relevant threshold. Investment payback follows recovery of project cash invested, while annual return on invested capital relates returns to invested capital rather than sales.
The Returns analysis presents break-even measures, project and cumulative cash flows, investment payback and annual ROIC. It supports an investment discussion without treating the illustrated EBITDA figures as proof of payback timing or cash sufficiency.
The Valuation worksheet separately estimates discounted cash-flow value using unlevered free cash flow, cost-of-capital assumptions and a terminal multiple. Scenario and valuation sensitivities are report functions, not documented numerical conclusions for this illustrative brick plant.
Use the workbook to organize a proposed plant operating plan and compare assumptions before evaluating capital commitments.
The template is suited to examining planned shifts in capacity utilization, kiln energy intensity, face-brick mix, wholesale selling prices and staffing. Model Checks, expense composition reports, KPI Benchmarks and financial ratios help review the consequences of changing assumptions.
It is a planning model based on estimated inputs, not evidence of verified industry performance, approved financing, an operating permit or a tested funding requirement. Adapt the assumptions to the actual plant design, distribution agreements and financing proposal.
These answers explain the workbook’s main inputs, calculations and reporting boundaries.
Yes. Adjust monthly saleable capacity, annual utilization and monthly seasonal factors to change the quantity of bricks allocated across finishes.
The documented case uses five finish categories with editable shares and annual net ex-works prices; each brick is allocated to one finish only.
Yes. Kiln gas, electricity, clay, consumables, packaging, fixed plant costs and the role-based Payroll schedule are modeled separately.
Yes. The workbook includes cash-flow, income-statement and balance-sheet reports, although the supplied illustrative numeric case establishes operating results only through EBITDA.
No. The $29,719,335 figure is an estimated scenario funding input, not a verified requirement or confirmation that cash will be sufficient.
No. EBITDA excludes investment and financing cash flows. Use the Returns and Cash Flow reports to evaluate payback and liquidity separately.
Yes. The Dashboard includes Low, Base and High scenario multipliers, with comparative revenue, margin and EBITDA outputs.
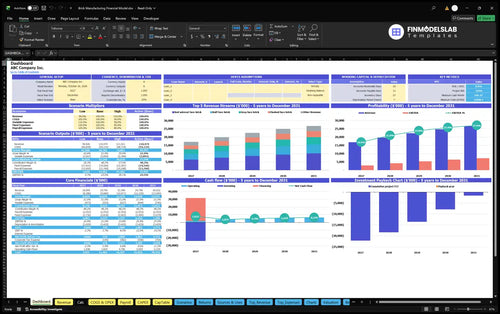
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
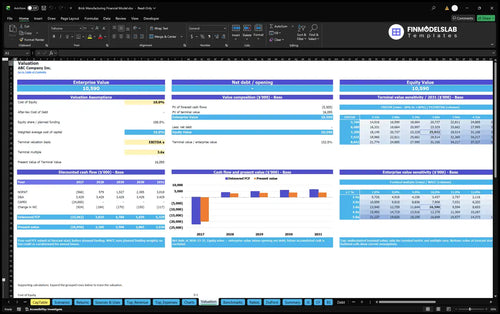
DCF valuation and sensitivity analysis.
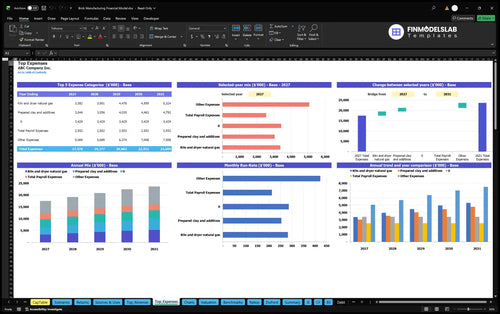
Largest costs and spending trends.
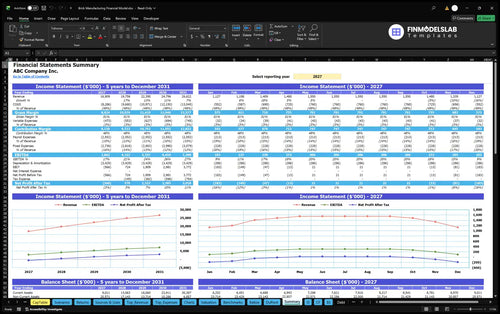
Annual and monthly financial performance.
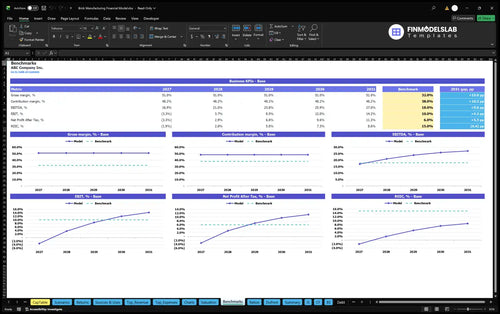
Compare margins and returns to benchmarks.

This template put pricing, input costs, and growth in one place, so I stopped hunting through scattered tabs. I saved a full afternoon just cleaning up assumptions and could explain the numbers without second-guessing them.

I finally knew what to show lenders and investors without guessing the format. The model gave me a clean structure in one pass, and I booked a meeting the same day I finished the forecast.
Switching between low, base, and high cases used to be a chore, but this made it straightforward. I cut scenario setup from hours to under an hour and could compare each case without rebuilding the sheet.