

Revenue and Calc
Edit partner hours, utilization, six service shares, and prices; Calc applies launch timing and aggregates monthly revenue.


The Cleaning Service Financial Model is an Excel template linking subcontracted cleaning capacity, utilization, service mix, and hourly prices to monthly revenue and five-year financial projections.
The illustrative case covers an independent Raleigh, North Carolina cleaning service launching January 31, 2026, with six service lines and a small administrative team; its assumptions are not industry averages.
The workbook combines service-level operating assumptions with financial statements, management reporting, funding schedules, and model checks.
Edit partner hours, utilization, six service shares, and prices; Calc applies launch timing and aggregates monthly revenue.
Set subcontracted cleaning costs, variable charges, fixed overhead, and owner-manager and dispatcher payroll to calculate operating expenses and EBITDA.
Schedule equipment purchases, owner contributions, and optional financing, with depreciation and repayment calculations where applicable.
Review Income Statement, Cash Flow, and Balance Sheet reports separately to assess earnings, liquidity, and financial position.
Use Dashboard, Scenarios, Returns, Sources & Uses, Valuation, Benchmarks, and Checks to evaluate decisions without assuming specific investment outcomes.
Sales are calculated from partner labor capacity, the share of hours booked, the mix of six cleaning services, and their year-specific hourly prices.
For 2026, 640 available partner hours per month at 65% utilization produce 416 sold hours, allocated once across six residential and commercial cleaning categories.
Recurring home cleaning uses 40% of sold hours; offices 20%, deep cleaning 15%, move services 10%, rental turnover 10%, and post-renovation cleaning 5%. Shares total 100%, preventing duplicated capacity.
The Revenue Forecast uses available service labor hours, booked utilization, service mix, and prices to project earned sales by cleaning category. It supports changing the capacity plan or price assumptions without treating administrative FTE as sellable cleaning staff.
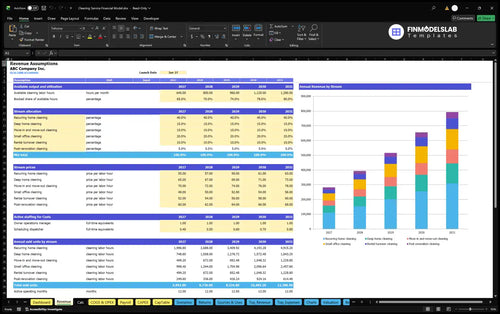
640 available hours × 65% booked × $56.55 blended hourly price ≈ $23,525 in monthly sales.
In this case, 12 full active months generate $282,298 in 2026 revenue. Annual available capacity rises to 1,280 hours per month in 2030, while booked utilization reaches 80%; service prices also increase by their documented annual schedules.
The January 31, 2026 launch receives a full month of revenue. Prelaunch months earn nothing; no separate seasonality adjustment applies.
The cleaning service forecast treats outsourced delivery labor as direct cost, rather than duplicating it in administrative payroll.
Direct costs comprise 55% subcontractor labor, 4% supplies, and 1.5% rework. Variable expenses include 2.44% payment processing and 4% local marketing, all as sales percentages.
Fixed overhead includes storage, insurance, software, communications, accounting, maintenance, supplies, and inspections. Workspace costs are $300 monthly in 2026 and $380 in 2030.
The COGS and Operating Expenses forecast separates subcontracted labor, variable charges, and fixed overhead, showing how cleaning revenue contributes to gross margin and overhead coverage.
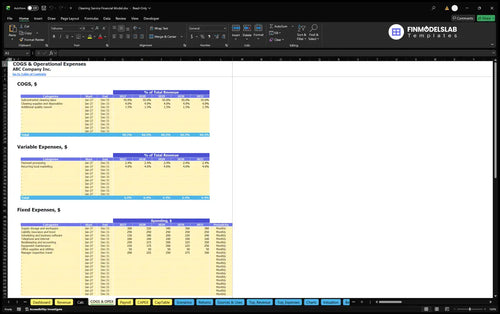
The 2026 example includes $170,790 COGS, $18,180 variable costs, and $17,400 fixed costs; fixed monthly amounts are multiplied by paid months.
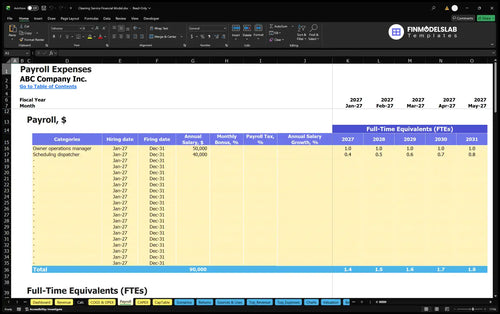
The Payroll Forecast covers one owner-manager FTE and 0.4 dispatcher FTE in 2026, at respective annual base pay rates of $50,000 and $40,000 per FTE. Cleaners remain in COGS.
Opening investment is modeled separately from annual operating expenses, with distinct capital purchases, launch cash items, and working-capital assumptions.
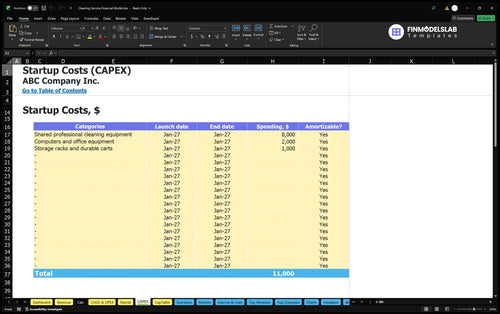
Startup assets include $8,000 cleaning equipment, $2,000 computers and office equipment, and $1,000 racks and carts. Formation, launch marketing, deposit, and contract/website costs are separate cash items.
The Capital Expenditure Plan schedules durable cleaning and office equipment and related depreciation. These startup purchases differ from the recurring direct and operating expenses used in EBITDA.
Working-capital controls use five receivable days, two inventory days, and zero payable days, affecting cash timing rather than earned sales or EBITDA.
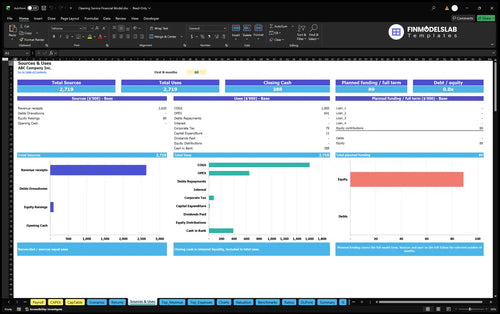
The Sources and Uses of Funds report reconciles funding and cash allocation. The example specifies $88,860 initial owner funding, no committed outside financing, and a reserve equal to three months of recurring outflows.
The base example projects increasing cleaning-hour capacity and booked utilization from 2026 through 2030, alongside corresponding operating expenses.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $282,298 | $272,370 | $9,928 |
| 2027 | $393,456 | $352,279 | $41,177 |
| 2028 | $516,177 | $439,809 | $76,368 |
| 2029 | $655,724 | $538,602 | $117,122 |
| 2030 | $793,190 | $636,002 | $157,189 |
Illustrative modeled case, not actual sales or an industry benchmark. Whole-dollar rounding may create small differences.
COGS, variable costs, overhead, and administrative payroll produce EBITDA of $9,928 in 2026 and $157,189 in 2030 as modeled service hours and utilization increase.
EBITDA excludes depreciation, interest, and business income tax. Neither actual cash generation nor net profit can be inferred from these case figures.
The Cash Flow Forecast separates operating, investing, and financing cash movements, including customer collection timing, asset purchases, equity, and debt if entered. It evaluates liquidity independently of projected EBITDA.
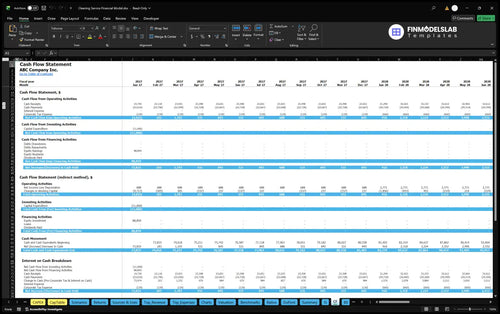
The Income Statement shows profit and loss; the Balance Sheet tracks assets, working capital, debt, and equity. Summary and Charts compare trends.
The workbook contains separate tools for operational break-even, investment recovery, annual return on capital, and the sensitivity of operating performance.
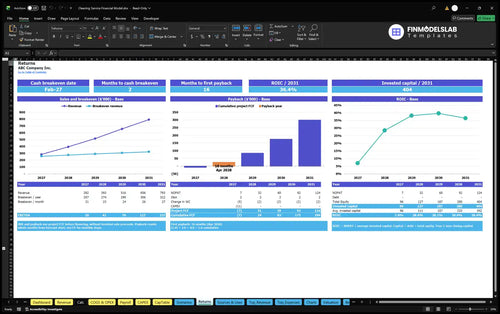
Sales break-even measures required operating revenue; cash break-even looks at cash recovery timing. Investment payback tracks recovered invested funds, while annual ROIC relates returns to invested capital.
None equals EBITDA. The case provides no confirmed break-even date, payback month, ROIC, or IRR result.
The Returns analysis combines sales break-even, cash break-even, investment payback, and annual ROIC to evaluate operating coverage, funding recovery, and modeled returns under selected assumptions.
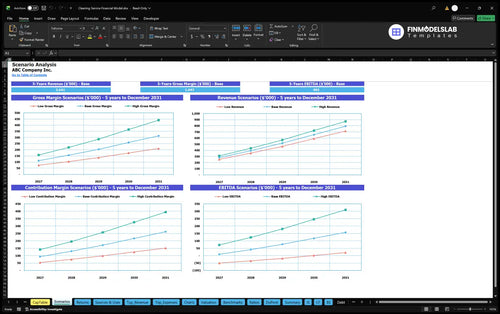
Dashboard Low, Base, and High multipliers adjust revenue, direct and variable costs, overhead, and payroll, enabling EBITDA and margin comparisons.
The Financial Scenario Analysis compares Low, Base, and High revenue, gross margin, contribution margin, and EBITDA to test shifts in sales and operating cost assumptions.
Use the model to test cleaning capacity, staffing, equipment, and financing decisions; Valuation and Benchmarks support additional input-driven analysis.
Quick answers about the Excel model, assumptions, forecast outputs, and practical uses.
Yes. Edit the six hourly service prices and the shares of booked labor hours; the Revenue and Calc schedules recalculate the resulting sales forecast.
No. Sales volume is driven by available subcontracted cleaning labor hours and booked utilization; the owner-manager and dispatcher are administrative payroll costs.
No. Delivery labor is modeled in direct COGS at 55% of sales, while the owner-manager and part-time dispatcher appear in the payroll schedule.
No. The Raleigh example is an illustrative operating scenario based on estimated assumptions and should be adapted to your own service operation.
No. EBITDA is an operating earnings measure; the Cash Flow, Income Statement, and Balance Sheet present other perspectives using their respective modeled inputs.
Yes. The Dashboard includes Low, Base, and High scenario multipliers for revenue and major cost groups, with comparisons in the scenario reports.
No. The Returns sheet contains payback and break-even analyses, but no numerical payback period is established in the documented example.
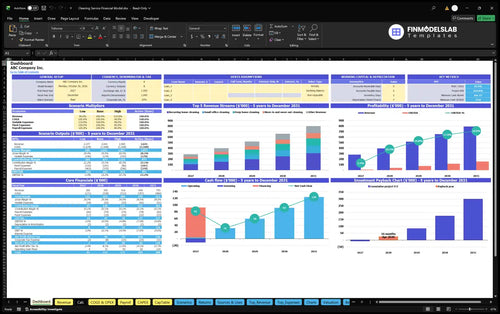
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
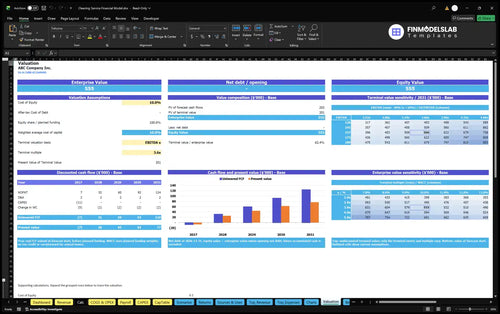
DCF valuation and sensitivity analysis.
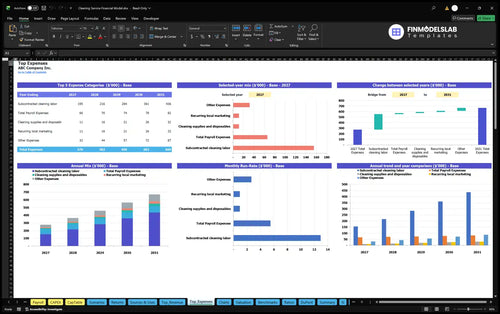
Largest costs and spending trends.
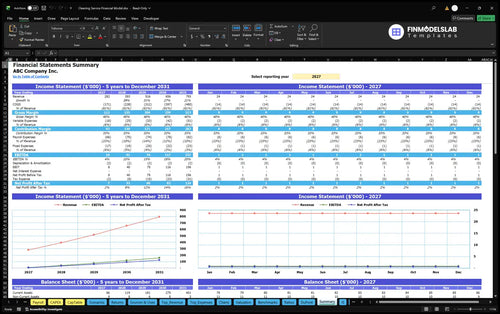
Annual and monthly financial performance.
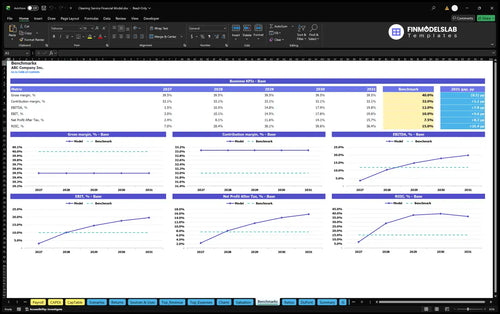
Compare margins and returns to benchmarks.

I stopped juggling low, base, and high cases in separate sheets. This template pulled them into one model, and I saved about 4 hours on each forecast update.

The statements and charts were all in one place instead of scattered across files. That made it much easier to prep a lender update and cut our monthly reporting time by half.
I used to worry that one broken cell would throw off the whole model. With this template, the checks gave me a clearer setup and saved me from a late-night rebuild.