

Revenue & Calc
Set launch timing, open days, daily drink purchases, drink-category mix, and prices; the monthly calculation schedule translates those assumptions into volume and sales by category.


The Coffee Shop Financial Model is an Excel planning template that builds five-year financial projections for a counter-service coffee shop from daily drink demand, menu prices, beverage mix, operating costs, staffing, and startup investment. Monthly operating calculations feed the workbook’s financial statements and management reports.
The included example models an independent, beverage-only shop in a previously fitted, leased 1,200-square-foot U.S. location, opening in January 2026. It does not assume a drive-through, delivery, prepared food, alcohol, wholesale sales, or retail coffee beans.
The template connects editable operating assumptions to monthly calculations, projected statements, and decision-focused reports.
Set launch timing, open days, daily drink purchases, drink-category mix, and prices; the monthly calculation schedule translates those assumptions into volume and sales by category.
Plan beverage ingredients, disposable cups, payment processing, occupancy, other overhead, barista FTE, and a working store manager without mixing direct costs with salaries.
Separate store equipment and improvements from preopening uses of cash, owner equity funding, and any financing facilities entered through Dashboard controls.
Review the Income Statement, Cash Flow Statement, Balance Sheet, linked supporting schedules, and reconciliation or input-error checks.
Use the Dashboard, Scenarios, Summary, Returns, Sources & Uses, Charts, and other documented reports to compare operating outcomes and examine funding needs.
Monthly sales equal open days multiplied by average daily drink purchases, allocated across five beverage categories and multiplied by their selling prices.
The example assumes 30 open days each month and daily drink purchases increasing from 180 in 2026 to 280 in 2030. One drink represents one transaction, and the selling prices exclude sales tax and tips.
The mix is 25% brewed coffee, 35% hot espresso drinks, 20% iced espresso drinks, 12% cold brew, and 8% tea and cocoa. Prices vary by drink and forecast year; for example, brewed coffee is $3.25 in 2026 and $3.65 in 2030.
The Revenue Forecast organizes daily drink demand, monthly open days, drink-category shares, and selling prices into the five-year sales plan. The Calc sheet applies these assumptions by month so changes flow into projected revenue.
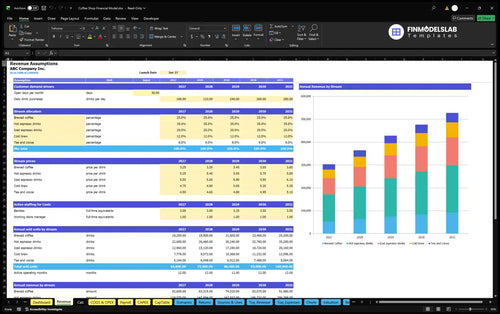
180 drinks/day × 30 open days/month × 12 months × $4.68 weighted average drink price = $303,264 annual revenue.
The model is driven by customer drink demand, not a fixed number of baristas or a theoretical machine-capacity utilization rate. Staffing is an independent cost input, enabling a direct assessment of whether projected beverage sales support the chosen labor plan.
The operating forecast calculates drink-level direct costs, payment fees, recurring fixed expenses, and employees’ base pay as distinct cost groups.
The COGS and Operating Expense Forecast separates ingredients, disposables, processing fees, and recurring overhead. The example assigns 21% of revenue to ingredients and ordinary spoilage, 4% to cups and lids, and 5.25% to card processing.
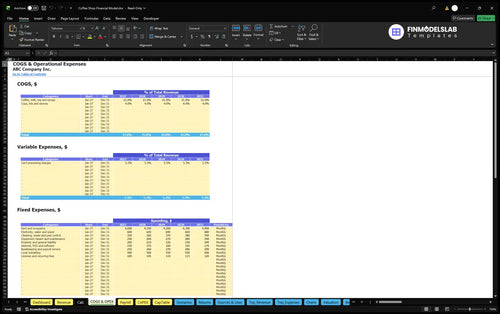
Direct beverage COGS total 25% of revenue in the selected case; paper cups and packaging are not charged again in other expense groups. The example also includes utilities, cleaning, insurance, software, bookkeeping, maintenance, local marketing, and licenses.
Monthly rent and occupancy start at $4,000 in 2026 and rise to $4,400 in 2030. Unlike percentage-based drink costs and processing fees, fixed costs do not automatically decrease when drink purchases are weaker than expected.
The Payroll Forecast plans salaries and FTE by staff role. The selected example includes 3.0 annual-average barista FTE in 2026, rising to 3.5 in 2030, at a $35,000 annual base per FTE, plus one $65,000 working manager.
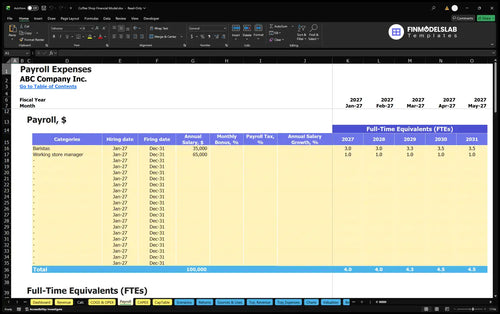
Capital purchases and preopening cash needs are modeled separately from recurring operating expenses and owner contributions.
The Capital Expenditure Plan schedules equipment and leasehold purchases and tracks depreciation where applicable. The example includes a $16,000 espresso system, $9,000 refrigeration and ice equipment, and $45,000 of light improvements to an already fitted store.
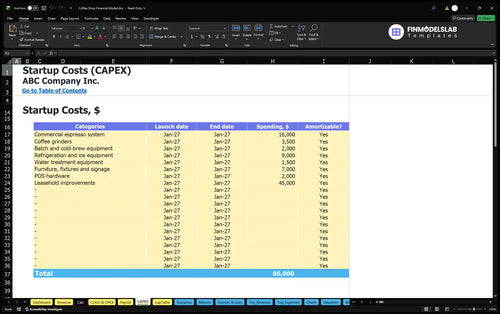
Other capital items include grinders, brewing equipment, water treatment, furniture and signage, and POS hardware. Deposits, permits, launch marketing, professional setup, and preopening payroll or rent are separate startup cash needs rather than additional beverage COGS.
The selected plan includes $197,523 of initial owner funding, a planning input that incorporates a three-month reserve policy. It is not a claim about the amount every coffee shop must raise or the terms of any commercial loan.
The Sources and Uses of Funds report reconciles modeled cash sources with operating, investing, and financing uses over a selected reporting period. It helps distinguish initial owner equity from equipment spending, working cash, and payments associated with financing.
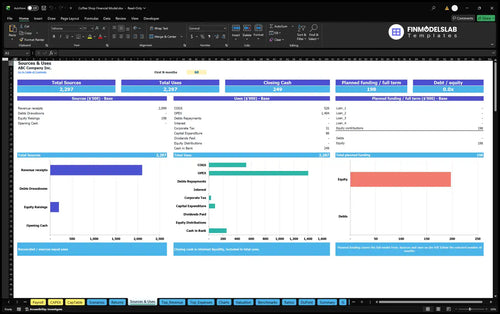
Working capital uses 0 accounts-receivable days, since drinks are paid for at purchase, alongside 8 accounts-payable days and 12 inventory days. These settings link sales receipts, supplier payment timing, and beverage inventory to the balance sheet and cash forecast.
Under the selected estimated inputs, the example progresses from an opening-year EBITDA loss to positive operating EBITDA in 2027.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $303,264 | $338,537 | −$35,273 |
| 2027 | $364,203 | $359,011 | $5,192 |
| 2028 | $428,112 | $389,734 | $38,378 |
| 2029 | $476,658 | $415,209 | $61,449 |
| 2030 | $527,184 | $433,133 | $94,051 |
Illustrative model outputs rounded to whole dollars; not historical results or industry averages.
Revenue grows as assumed daily drink purchases increase from 180 to 280 and individual category prices move upward. The 2026 EBITDA loss of $35,273 becomes positive EBITDA of $5,192 in 2027 in this particular model case.
EBITDA is revenue less the operating expenses shown here, before depreciation, interest, and taxes. It is not net profit or cash flow, and these illustrative numbers do not establish investment payback, a valuation, or guaranteed trading performance.
The Cash Flow Forecast tracks operating receipts and payments as well as investing and financing movements, then reconciles opening and closing cash. That view is important when startup purchases and reserve funding affect liquidity differently from operating EBITDA.
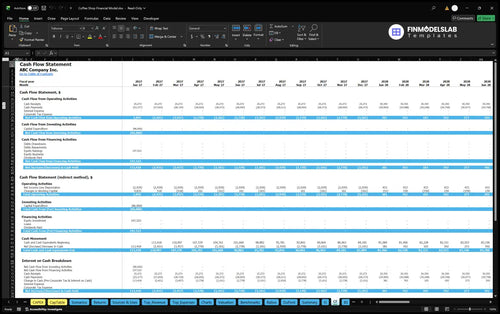
The Income Statement presents accounting profitability, while the Balance Sheet tracks cash, inventory, payables, financing balances, and equity. The Summary report joins selected statement views so the sales ramp, cost base, financial position, and liquidity can be reviewed together.
The workbook provides separate tools for operating break-even, cash break-even, investment recovery, and returns on invested capital.
The Returns report evaluates break-even revenue, cumulative project cash flows, investment payback, and annual return on invested capital. Each measure answers a different question: covering operating costs, covering cash needs, recovering investment, or earning on deployed capital.
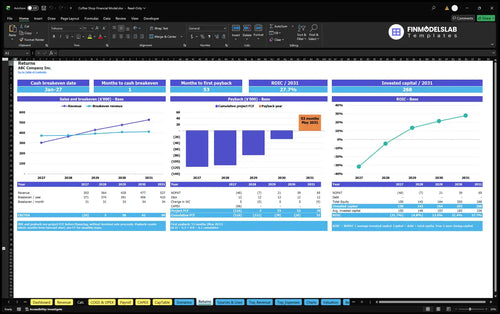
A positive EBITDA year does not automatically indicate cash break-even or a recovered initial investment. Use the separate Returns calculations with the Cash Flow and CAPEX schedules, and do not infer a payback month or ROIC figure from the example EBITDA table.
The Financial Scenario Analysis compares Low, Base, and High assumptions for revenue, direct costs, variable expenses, fixed expenses, and payroll. It provides side-by-side changes in projected gross margin, contribution margin, and EBITDA for coffee shop operating sensitivity.
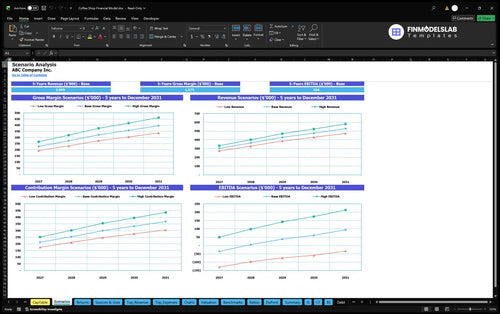
Test slower drink purchases, higher bean and milk costs, or increased rent against the selected staffing plan. The Dashboard controls also support financing assumptions, including facility amount, start date, interest-only period, rate, term, and repayment structure where debt is modeled.
These answers clarify the model’s editable assumptions, reporting scope, and key financial distinctions.
It multiplies open days by daily drink purchases, distributes volume across five beverage categories, and applies each category’s selling price.
Yes. Edit the five category shares and annual selling prices on the Revenue inputs to update monthly and annual sales projections.
No. The selected planning case covers a beverage-only, counter-service shop without prepared food, delivery, wholesale, alcohol, retail beans, or a drive-through.
No. Base salaries for baristas and the store manager are planned on Payroll, separate from fixed expenses such as occupancy and utilities.
Yes. The workbook includes Cash Flow, Balance Sheet, Sources & Uses, CAPEX, CapTable, and debt schedules; their results depend on the entered assumptions.
No. EBITDA measures operating results before depreciation, interest, and tax; payback considers cumulative project cash flows and initial investment.
No. The 2026–2030 example contains selected estimated assumptions and illustrative model outputs, not verified industry averages, audited results, or guaranteed performance.
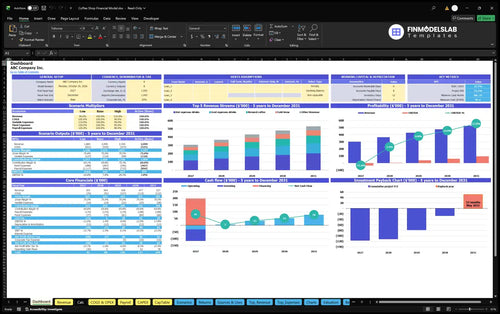
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
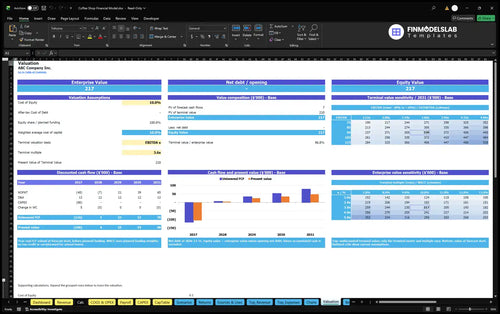
DCF valuation and sensitivity analysis.
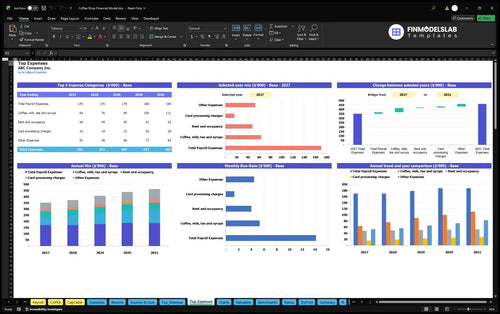
Largest costs and spending trends.
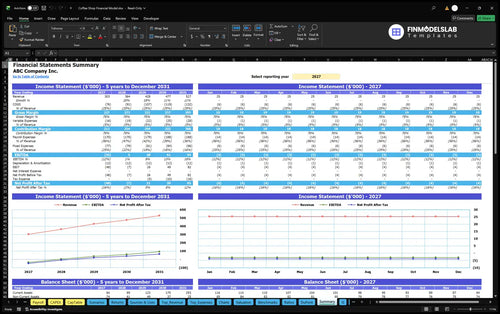
Annual and monthly financial performance.
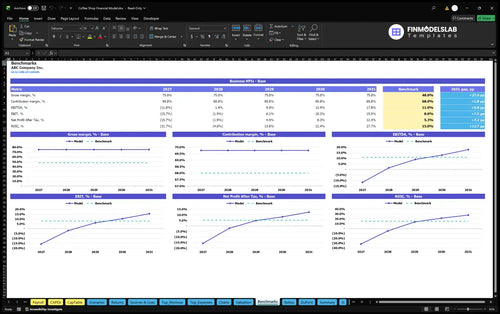
Compare margins and returns to benchmarks.

I could finally compare low, base, and high cases without rebuilding the sheet every time. It saved me hours and made the numbers easier to explain in one meeting.
I was stuck staring at a blank spreadsheet, and this gave me a clean place to begin. I had the first full draft done the same day instead of spending a week trying to set it up.
Building the forecast by hand was eating up too much time. This template cut my prep work down by days and let me focus on the actual coffee shop plan.