

Revenue and Calc
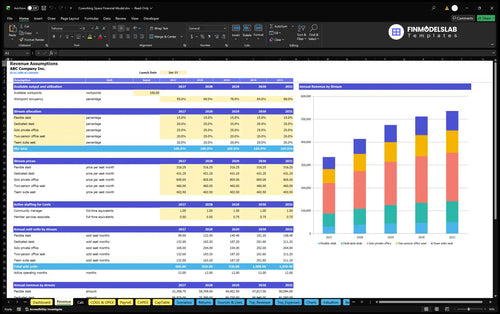
Set annual occupancy, membership shares, prices, and launch timing on Revenue. Calc translates those drivers into monthly seat activity and revenue without selling the same workpoint twice.


The Coworking Space Financial Model is an Excel planning template for a single independent, 100-workpoint coworking location in Columbus, Ohio. It turns membership capacity, occupancy, membership mix, and monthly realized prices into a 2026–2030 revenue forecast and connects those sales to staffing and operating expenses.
The documented illustration uses a 9,000-square-foot leased office with five exclusive workpoint products. Meeting rooms and coffee are included in memberships; separate event, virtual-office, meeting-room rental, and food retail revenue are not assumed.
Linked operating schedules, financial statements, and decision reports help you move from workspace assumptions to an integrated financial plan.
Set annual occupancy, membership shares, prices, and launch timing on Revenue. Calc translates those drivers into monthly seat activity and revenue without selling the same workpoint twice.
Plan member supplies, payment and acquisition charges, office lease expenses, and role-based staffing. Separate schedules explain where gross, contribution, and EBITDA margins come from.
Record office fit-out and equipment spending, owner contributions, and optional financing facilities. Dashboard debt controls feed repayment schedules; the selected case assumes owner funding, not committed borrowing.
Access linked monthly income statement, cash flow, and balance sheet reports. They have distinct purposes: accounting performance, cash movement, and the financial position of the site.
Review key outputs and change Low, Base, and High multipliers for revenue and expense categories on Dashboard. Compare operating outcomes without treating a selected scenario as a market forecast.
Review break-even, investment payback, annual ROIC, valuation sensitivity, charts, benchmarks, and model reconciliations. Results depend on the assumptions entered and should be checked before any financing decision.
Annual membership sales equal occupied workpoint-months allocated by product mix and multiplied by the realized monthly price for each product.
The planning case has 100 workpoints and yearly occupancy assumptions of 55%, 68%, 78%, 84%, and 88% from 2026 through 2030. Product shares add to 100%: flexible desks 15%, dedicated desks 20%, solo private offices 25%, two-person office seats 20%, and team suites 20%.
Monthly net prices in the selected optimistic case are $316.25, $431.25, $805, $460, and $402.50 per occupied workpoint, respectively. These are estimated planning inputs, not verified local transaction prices.
The Revenue Forecast sets workpoint capacity, occupancy, membership allocation, and monthly price assumptions. Those drivers flow to the monthly Calc schedule, so higher occupancy raises sold seat-months without creating additional desks.
100 workpoints × 55% occupancy × 12 months × $507.4375 weighted realized monthly price ≈ $334,909 annual revenue.
Four mutually exclusive cost groups drive the documented operating forecast: direct costs, variable costs, fixed costs, and payroll.
COGS covers member coffee and printing supplies at 2.17% of revenue. Variable expenses include payment processing at 1.5% and member acquisition commissions at 1.5%. These revenue-linked items increase when prices rise even if physical occupancy is unchanged.
The COGS and Operating Expenses schedule organizes direct, variable, and fixed operating charges. For this coworking site, fixed costs include rent, utilities, cleaning, internet, software, insurance, repairs, marketing, administration, and security.
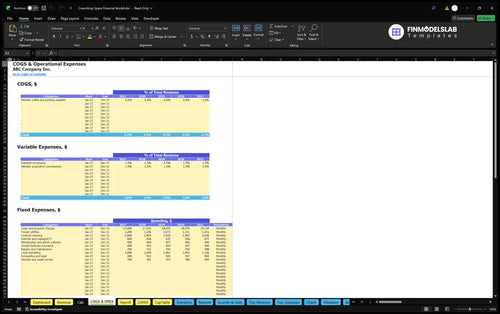
Lease and property charges begin at $17,000 per month in 2026 and rise to an estimated $19,134 per month by 2030. The annual fixed-cost category increases from $286,800 to $322,796; salaries stay outside this fixed-expense category.
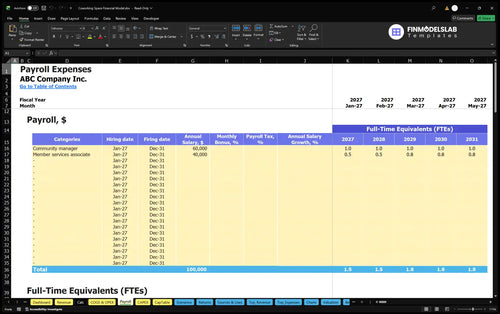
The Payroll Forecast calculates compensation by staff role and FTE. The case includes one community manager at a $60,000 annual base salary and member services coverage growing from 0.5 to 0.75 FTE at a $40,000 full-time base.
Office preparation and opening cash needs are modeled separately from recurring operating expenses and EBITDA.
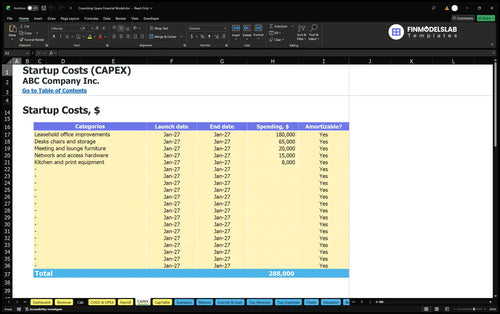
The site plans $288,000 in startup assets, including $180,000 in leasehold improvements, $65,000 in desks and storage, $20,000 in meeting and lounge furniture, and $15,000 in network and access hardware. Kitchen and printing equipment complete the asset budget.
The CAPEX schedule records capital expenditure items, purchase dates, and depreciable treatment. It helps separate initial coworking fit-out and furniture investments from monthly operating costs and links eligible purchases to the depreciation schedule.
A further $82,000 covers preopening cash items such as a refundable lease deposit, formation and legal setup, early marketing, and preopening rent and staff payments. Opening supplies are $279.26, with a three-month operating reserve of $96,032.
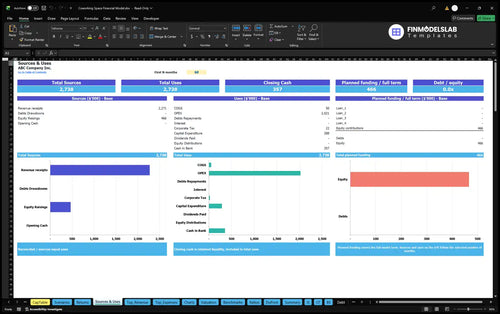
The Sources and Uses of Funds report reconciles funding receipts against operating, investment, and financing cash uses. The planning case specifies $466,311 of initial owner funding, without assuming a committed lender facility or a completed peak-funding test.
The selected optimistic-price illustration shows a 2026 ramp loss followed by positive operating EBITDA from 2027.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $334,909 | $384,128 | -$49,219 |
| 2027 | $414,069 | $396,828 | $17,241 |
| 2028 | $474,962 | $418,840 | $56,121 |
| 2029 | $511,497 | $429,859 | $81,638 |
| 2030 | $535,854 | $440,521 | $95,333 |
Illustrative model projections, rounded to whole dollars; rounding can create small differences in displayed subtotals.
By 2030, the price-uplift case projects $535,854 in revenue and $95,333 in EBITDA, a 17.79% EBITDA margin. The frozen-price baseline instead shows $465,960 in revenue and $27,536 in EBITDA, a 5.91% EBITDA margin.
The 15% price uplift improves year-five revenue by $69,894 while operating expenses increase by approximately $2,097 because certain costs are sales-linked. The illustration does not establish realized customer demand, after-tax income, or available financing.
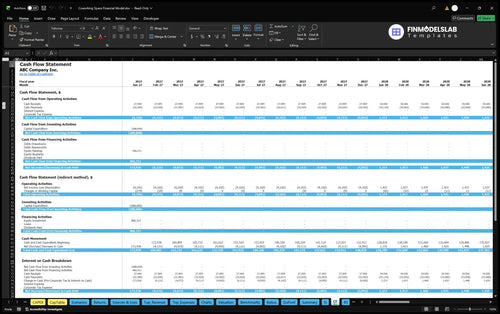
The Cash Flow Forecast tracks monthly receipts, operating payments, investment, and financing flows with an opening-to-closing cash reconciliation. Use it separately from EBITDA when testing whether early losses, fit-out spending, or member collections create liquidity pressure.
The workbook provides investment and scenario analysis, but the supplied case does not establish a payback date, ROIC result, or valuation.
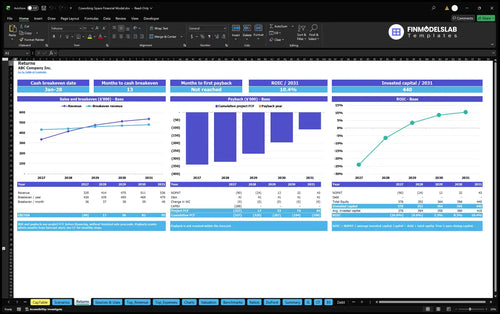
Sales break-even compares revenue with the costs that must be covered. Cash break-even measures when net cash movement reaches the chosen threshold; investment payback asks when cumulative project cash flow recovers invested capital. Annual ROIC measures returns relative to invested capital.
The Returns analysis brings together sales break-even, cash break-even, investment payback, and annual ROIC measures. Their calculations use different cash or earnings definitions, so a positive EBITDA year alone cannot establish that the fit-out investment has been repaid.
Scenario Controls on Dashboard allow Low, Base, and High multipliers for revenue, COGS, variable expenses, fixed expenses, and payroll. These are workbook controls; the documented 15% price exercise is a specific user-defined planning case rather than proof that members will accept higher fees.
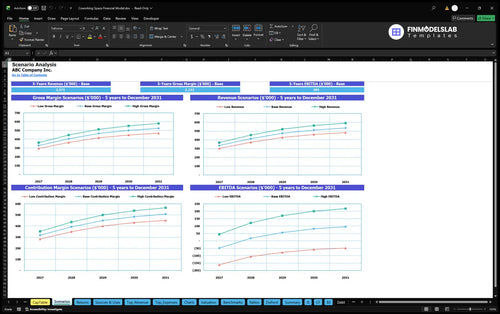
The Financial Scenario Analysis compares Low, Base, and High outcomes for revenue, gross margin, contribution margin, and EBITDA. It shows the sensitivity of the coworking plan to assumptions without presenting hypothetical cases as observed market performance.
These answers clarify the model’s capacity logic, editable assumptions, and the boundaries of the illustrated results.
Yes. Revenue inputs include five realized monthly prices and the allocation of occupied workpoints across flexible desks, dedicated desks, solo offices, two-person office seats, and team suites.
No. The documented case uses one 100-workpoint inventory and a single occupancy driver; the five product allocations are mutually exclusive.
No. Meeting rooms and coffee are included in membership access; independent meeting-room rentals, events, virtual offices, and retail sales are outside this case.
All five estimated realized prices rise 15% while occupancy, capacity, mix, and staffing stay unchanged. This is a planning assumption, not evidence of member acceptance.
No. EBITDA excludes important cash movements. Review Cash Flow and Returns separately for liquidity, cash break-even, payback, and ROIC calculations.
No. Initial owner funding is estimated at $466,311. Debt inputs and repayment schedules exist in the workbook, but no external financing commitment is assumed.
No. The 2026–2030 figures are illustrative forecasts built from estimated operating inputs and a user-defined pricing scenario, not historical results or published industry averages.
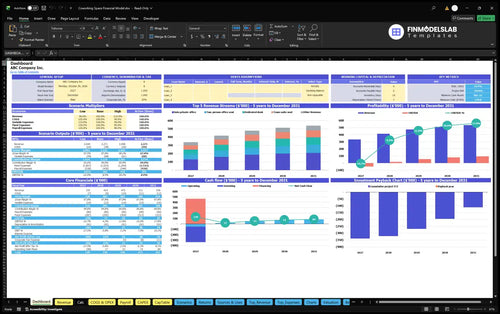
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
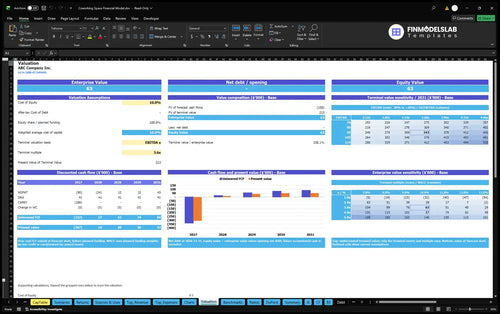
DCF valuation and sensitivity analysis.
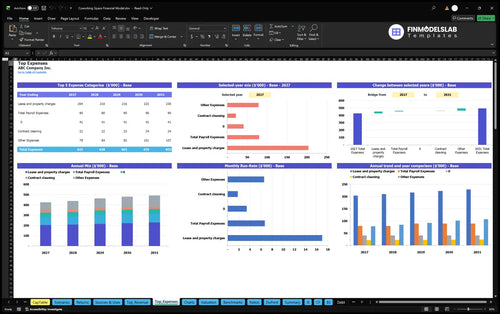
Largest costs and spending trends.
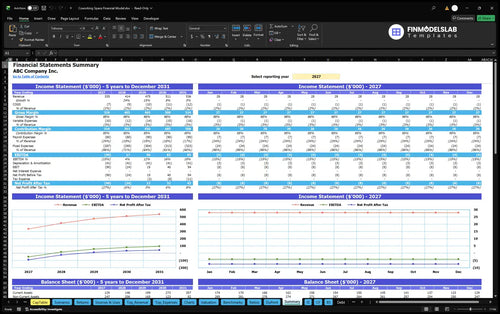
Annual and monthly financial performance.
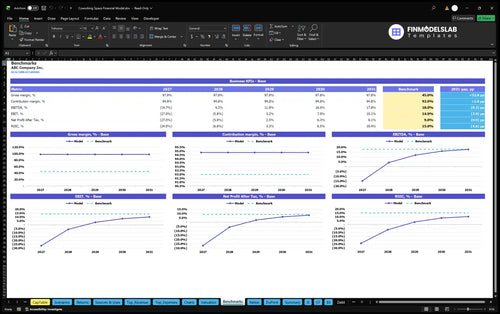
Compare margins and returns to benchmarks.

I finally knew what investors expected to see, so I could stop guessing and build the model with the right structure. It made my pitch prep much clearer and helped me walk into meetings with confidence.
What would’ve taken me days to build by hand was already laid out, so I finished the forecast in an afternoon. That saved me at least 12 hours and let me move on to the deck.
I’m not deep in Excel, but this template kept the formulas out of my way and the inputs easy to follow. I was able to finish the model without hiring help.