

Revenue & Calc
Translate groomer hours, utilization, service mix, and hourly prices into monthly grooming and bathing revenue.


The Dog Grooming Financial Model is an Excel financial planning template for estimating salon bookings, grooming revenue, staffing costs, startup investment, and financial performance. It converts available groomer hours, booking utilization, service mix, and hourly prices into a monthly operating forecast and connected financial reports.
Its illustrative case models an independent three-station dog grooming salon in a leased 1,000-square-foot unit in Raleigh, North Carolina, from 2026 through 2030. The scope excludes boarding, daycare, veterinary services, retail resale, and employee tips as business revenue.
Connected operating inputs, calculations, financing schedules, and financial reports let you review the grooming salon as one integrated business case.
Translate groomer hours, utilization, service mix, and hourly prices into monthly grooming and bathing revenue.
Plan consumables, outsourced laundry, selling fees, fixed salon overhead, and salaries without double counting.
Schedule equipment investment and equity funding, with optional financing facilities.
Review income, cash flows, balance sheet, and linked working-capital schedules.
Compare Low, Base, and High outcomes, break-even, investment payback, valuation, and benchmarks.
The revenue forecast is capacity constrained: available groomer hours multiplied by booked utilization determine total sold service hours.
Three salaried groomers provide 462 hours per active month. Booked utilization rises from 60% in 2026 to 70%, 77%, 82%, and 85% across 2030; the modeled launch date is January 31, 2026.
Sold hours are allocated once: small-dog full groom 25%, medium-dog 30%, large-dog 20%, bath and brush 15%, and bath and deshed 10%. Each allocation earns its own hourly price.
462 available groomer hours × 60% booked utilization = 277.2 sold service hours per month.
The Revenue Forecast connects groomer capacity, utilization, service mix, and prices to monthly Calc schedules and annual revenue. Change bookings or pricing to evaluate sales growth without assuming additional staffed hours.
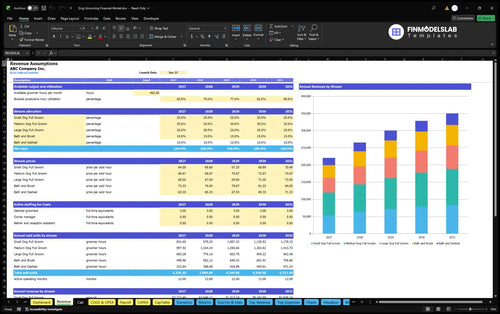
The 2026 hourly prices are $64 for small-dog grooming, approximately $66.67 for medium dogs, $65 for large dogs, $73.33 for bath and brush, and $63.33 for bath and deshed. The source forecast is approximately $18,388 monthly.
Changing hours, utilization, mix, or prices adjusts revenue without duplicating capacity. Boarding, daycare, retail, veterinary work, and employee tips are excluded.
The expense forecast distinguishes costs linked to revenue, monthly salon overhead, and fixed salaries for the defined staffing plan.
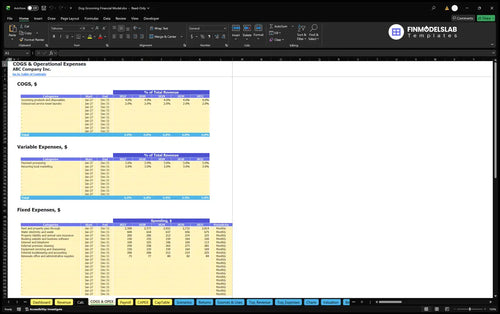
COGS covers grooming supplies (4% of sales) and outsourced towel laundry (2%), while variable expenses cover payment processing (3%) and local marketing (3%). Together these revenue-linked costs equal 12% of sales before fixed overhead and payroll.
Fixed overhead includes rent, utilities, insurance, software, telephone, cleaning, maintenance, bookkeeping, and administration. Illustrative 2026 rent and property pass-through is $2,500 monthly.
The COGS and Operating Expenses forecast translates revenue-based supplies, laundry, processing, and marketing, plus scheduled fixed overhead, into monthly expenses. It preserves the distinction between direct costs, variable selling expenses, and premises costs.
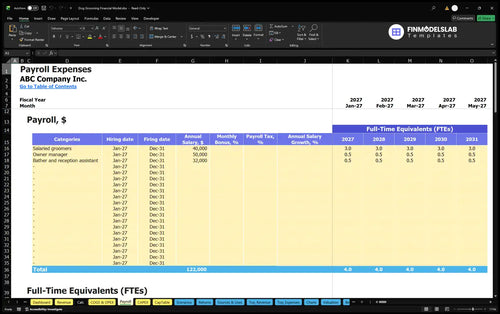
Payroll separately includes three groomers at $40,000 annual base each, a 0.5 FTE owner-manager at $50,000 per full-time role, and a 0.5 FTE bather/reception assistant at $32,000 per full-time role. Combined base pay is $161,000 yearly.
This staffing plan totals four FTE, with only three groomers. Salaries do not reappear in COGS or overhead; the case excludes employer payroll burden, benefits, and personal taxes.
The Payroll Forecast schedules personnel expenses by role, FTE, and salary assumptions. Test groomer staffing or support hours to see how personnel spending influences monthly income and financial reports.
Startup assets, preopening cash requirements, inventory working capital, and owner contributions are distinct from annual operating expenses.
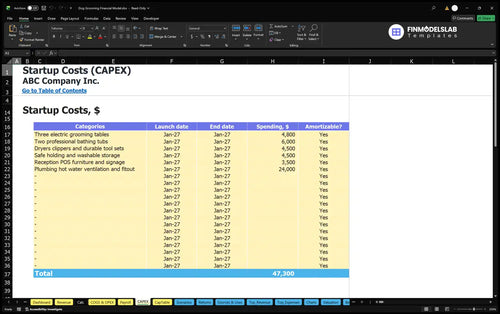
Startup assets include grooming tables ($4,800), two bathing tubs ($6,000), dryers and durable tools ($4,500), and storage ($4,500), alongside reception furniture, signage, plumbing, and fitout.
Separate opening cash covers lease deposits, inspections, permits, legal setup, launch marketing, preopening rent and payroll, and utility deposits. These differ from annual operating expenses.
The Capital Expenditure Plan schedules purchases of tables, tubs, tools, and fitout and tracks depreciation. These investments are identified apart from recurring grooming supplies and staff salaries in the operating forecast.
Working-capital controls use zero receivable days, zero payable days, and 20 inventory days. Estimated initial owner funding is $126,570, covering assets, preopening cash, opening working capital, and a reserve equal to three months of recurring cash costs.
That reserve does not prove peak cash sufficiency. No external financing is confirmed; debt controls allow separate hypothetical borrowing cases.
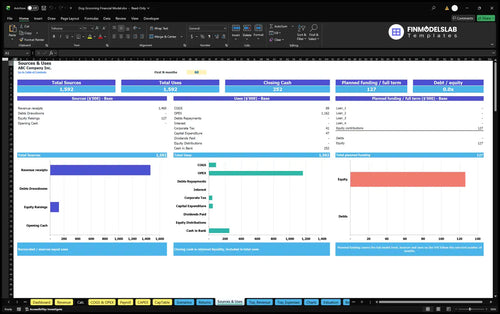
Sources and Uses of Funds reconciles planned funding with operating, investing, and financing allocations. It helps distinguish owner equity, optional debt, business receipts, and cash consumed by a salon launch.
The documented base-case projection combines service revenue with COGS, variable expenses, fixed costs, and payroll to calculate annual EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $220,651 | $238,178 | -$17,527 |
| 2027 | $265,188 | $245,044 | $20,144 |
| 2028 | $300,245 | $250,817 | $49,428 |
| 2029 | $328,833 | $255,861 | $72,972 |
| 2030 | $350,288 | $260,098 | $90,190 |
Forecasts are illustrative, not historical results or industry averages. Dollar values are rounded; totals may differ slightly.
Projected 2026 EBITDA is negative $17,527 at 60% utilization. At 70% utilization in 2027, $265,188 in revenue supports $20,144 EBITDA. By 2030, 85% utilization supports $350,288 revenue and $90,190 EBITDA.
EBITDA excludes depreciation, interest, and taxes and is not net profit or cash. While the Income Statement provides additional lines, the source case supplies no numeric net profit, valuation, or ending cash figures.
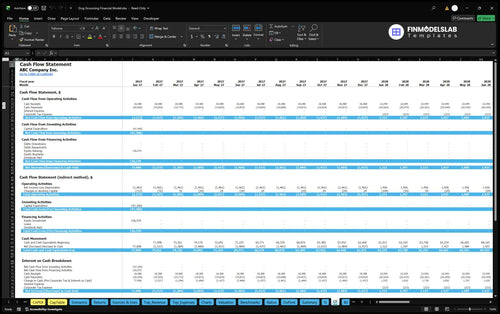
The Cash Flow Forecast links operating cash receipts and payments with capital spending, equity, and optional debt. Its cash reconciliation helps evaluate liquidity separately from projected EBITDA.
Scenario controls and the Returns report help evaluate different booking outcomes without equating operating profit with investment recovery.
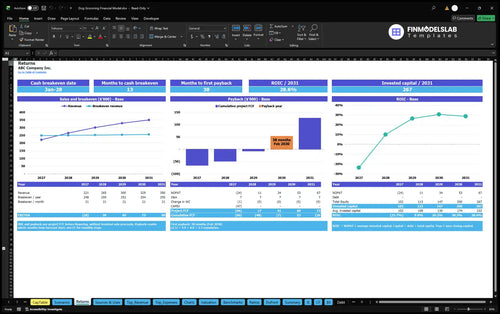
The Returns report distinguishes sales break-even from cash break-even. Investment payback examines cumulative project cash flow against invested funds; annual ROIC measures a separate relationship between returns and capital.
The supplied operating case establishes no payback month, cash break-even date, or numerical ROIC. Read those outputs in the workbook for the chosen assumptions.
The Returns report evaluates operating break-even requirements, cumulative project free cash flow, investment payback, and ROIC. These measures address different questions about covering costs and recovering invested capital.
Dashboard Low, Base, and High controls adjust revenue, COGS, variable expenses, fixed expenses, and payroll. Compare weaker bookings or lower realized prices against the base case to expose fixed-salary risk.
Quick answers about the service-hour revenue logic, editable assumptions, and distinctions among earnings, funding, and cash returns.
Available groomer hours times booked utilization produces sold hours; service mix and hourly prices turn them into revenue.
Yes. Change capacity, yearly utilization, service mix, and realized hourly prices.
No. Only five grooming and bathing services are modeled, excluding boarding, daycare, retail, veterinary work, and tips.
No. Salaries for groomers, owner-manager, and assistant appear separately in Payroll.
No. Cash flow also captures investment and financing movements; EBITDA is not net profit.
No. It is illustrative owner funding under an opening-cost and reserve policy, not a confirmed borrowing need.
Yes. Low, Base, and High controls vary revenue and major operating cost groups.
Yes. Returns supports break-even, payback, and ROIC; no numerical outcomes are established in the case brief.
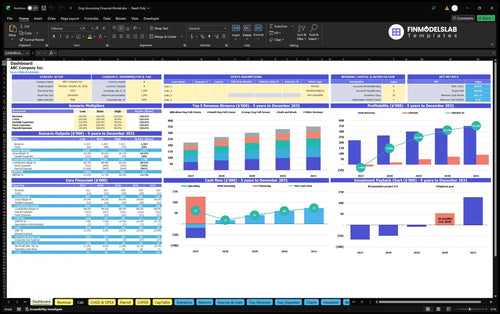
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
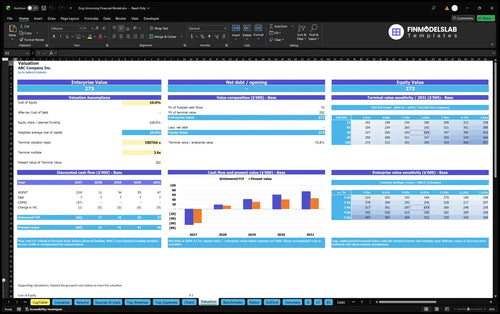
DCF valuation and sensitivity analysis.
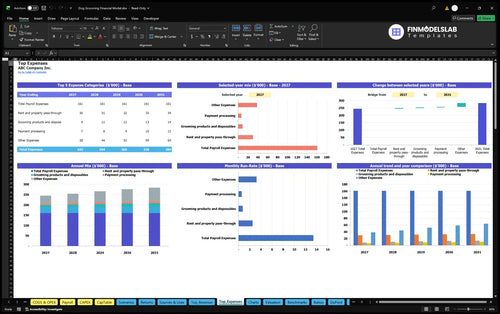
Largest costs and spending trends.
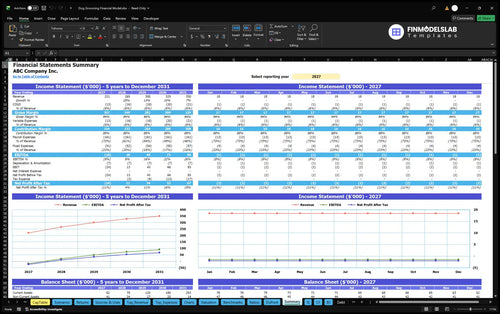
Annual and monthly financial performance.
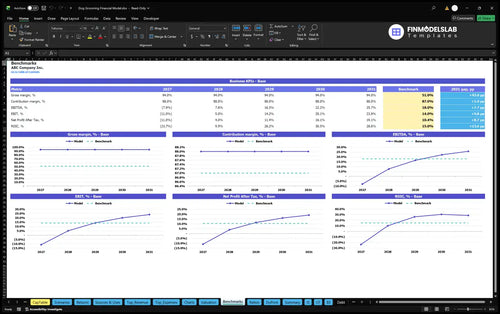
Compare margins and returns to benchmarks.

I had pricing, costs, and growth ideas all over the place, and this template brought them into one clean setup. It saved me hours of back-and-forth and made it much easier to explain the numbers to my partner.
The break-even and margin sections made the profitability picture clear without me digging through formulas. I could spot the weak spots fast, and that helped me get a cleaner forecast ready for my lender meeting.

My statements and charts were split across different sheets before, which made reporting messy. This template pulled everything into one place, and I had a shareable monthly summary ready in less than a day.