

Revenue & Calc
Set offered monthly visits, utilization, discipline shares, and annual visit prices. Monthly calculations apply launch timing and consolidate the five service streams.


The Home Health Care Agency Financial Model is an Excel template for a small, licensed, private-pay skilled home health agency in Columbus, Ohio. It connects visit capacity, utilization, service mix, realized prices, clinical purchasing, and management staffing to financial projections for 2026–2030.
The illustrated agency uses one administrative office and outside licensed providers for five home-visit services. Medicare, Medicaid, bundled reimbursement, overnight shifts, and medicine or equipment resale are outside this fee-for-service case.
Editable operating assumptions connect the agency’s visit plan with costs, financial statements, scenario comparisons, and funding reports.
Set offered monthly visits, utilization, discipline shares, and annual visit prices. Monthly calculations apply launch timing and consolidate the five service streams.
Plan purchased clinical services, consumables, overhead, and management FTE separately. This structure keeps outside clinical labor distinct from supervisory and administrative salaries.
Select Low, Base, or High multipliers for revenue and four cost groups on Dashboard. Scenarios compares the resulting revenue, margins, and EBITDA.
IS, CF, and BS present profitability, cash movement, and financial position. Checks reviews reconciliations and inputs; the supplied example establishes operating results through EBITDA only.
One shared visit-slot pool becomes completed visits through utilization, then each discipline earns its allocated visits multiplied by its realized price.
Offered capacity increases from 600 monthly visit slots in 2026 to 900 in 2030, while utilization rises from 55% to 80%. These inputs produce 330 and 720 completed visits per month, respectively, without seasonality or a separate demand or staffing limiter.
Completed visits are allocated once: 40% nursing, 25% physical therapy, 15% occupational therapy, 10% speech therapy, and 10% aides. The corresponding 2026 visit prices of $175, $195, $185, $200, and $95 produce a weighted realized price of $176.
The Revenue Forecast shows visit capacity, utilization, service mix, prices, and projected revenue. Adjust these estimated inputs to evaluate how referral-driven utilization, offered slots, or discipline pricing changes the agency’s sales forecast.
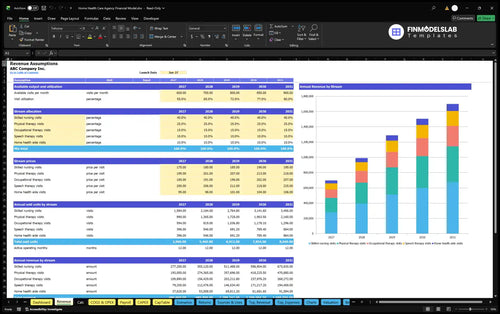
600 monthly slots × 55% utilization × 12 months × $176 weighted visit price = $696,960.
The January 31, 2026 launch counts January as a full operating month; earlier months earn no revenue. Skilled visits take approximately one hour and aide visits two hours, so offered slots should be reviewed against provider availability outside the model’s capacity calculation.
Revenue-based costs scale with visits and prices, while fixed overhead and management FTE determine the remaining operating earnings.
The COGS & Operating Expense Forecast separates direct, variable, and fixed costs. Purchased clinical visits consume 60% of revenue and consumables 2%; fixed expenses rise from $75,600 in 2026 to $90,000 in 2030, including rent, insurance, secure records, compliance, and professional services.
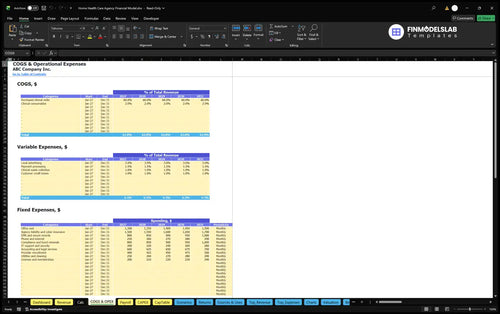
Variable expenses total 6.5% of revenue: advertising 3%, payment processing 1.5%, clinical waste collection 1%, and customer credit losses 1%. After 62% COGS and these variable expenses, 31.5% remains to cover fixed costs and payroll before EBITDA.
| Role | 2026 FTE | 2030 FTE | Annual base per FTE |
|---|---|---|---|
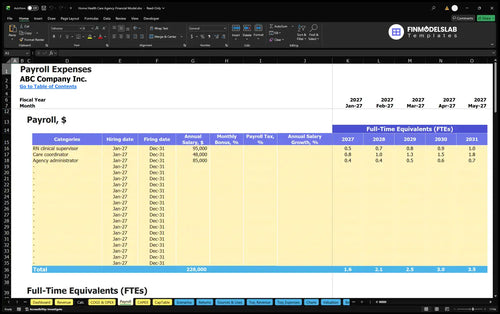
| RN clinical supervisor | 0.50 | 1.00 | $95,000 |
| Care coordinator | 0.75 | 1.75 | $48,000 |
| Agency administrator | 0.35 | 0.70 | $85,000 |
FTE represents annual-average staffing, not individual headcount; base pay per FTE is fixed throughout the forecast.
The Payroll Forecast calculates role costs from staffing and compensation inputs. Annual management payroll increases from $113,250 to $238,500; purchased clinical labor stays in COGS, and this case excludes employer taxes and benefits.
Estimated initial owner funding is $217,426, combining startup assets, distinct prelaunch cash items, opening working capital, and a recurring-cost reserve.
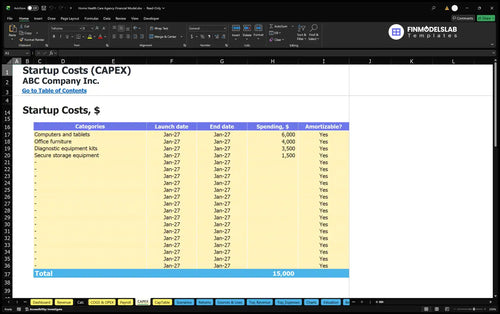
The Capital Expenditure Plan schedules asset purchases and depreciation. Listed startup assets total $15,000: computers and tablets $6,000, office furniture $4,000, diagnostic kits $3,500, and secure storage $1,500.
Separate prelaunch payments cover licensing, formation and clinical policies, the office deposit, website, credentialing, and preopening management. Owner cash also includes physical opening net working capital and three months of recurring cash outflow, with no committed external financing.
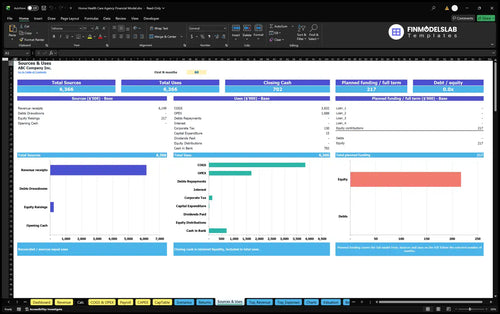
Sources and Uses of Funds reconciles funding sources and cash allocation over selected forecast months. Use it with CapTable’s owner contributions and Dashboard’s Debt Controls to review funding inputs; owner equity is separate from revenue and annual operating expenses.
The supplied estimated case projects higher annual revenue and EBITDA across all five forecast years.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $696,960 | $666,268 | $30,692 |
| 2027 | $989,898 | $901,030 | $88,868 |
| 2028 | $1,288,742 | $1,139,339 | $149,404 |
| 2029 | $1,506,005 | $1,321,763 | $184,241 |
| 2030 | $1,699,056 | $1,492,353 | $206,703 |
Illustrative projections, not historical results or industry averages; amounts are independently rounded to whole dollars, so displayed differences may vary by $1.
Operating expenses include COGS, variable expenses, fixed overhead, and payroll. EBITDA margin is approximately 4.4% in 2026 and 12.2% in 2030; EBITDA dollars increase every year, while the margin dips slightly in 2030 as staffing and overhead grow.
The Cash Flow Forecast shows operating, investing, and financing cash movements with an opening-to-closing cash reconciliation. Review the 7 receivable days, 1 payable day, and 1 inventory day inputs alongside startup spending and funding; these controls do not establish tested cash sufficiency.
The Returns report separates operating cost coverage, cash break-even timing, investment recovery, and annual return on invested capital.
The Return on Invested Capital Analysis combines sales break-even, cash break-even, investment payback, and annual ROIC. Use these measures to evaluate whether the visit plan covers operating costs and how the investment performs after relevant cash-flow and capital inputs are reviewed.
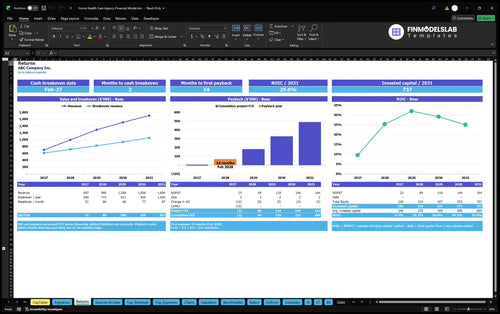
Sales break-even assesses revenue needed to cover operating costs; cash break-even examines cash-flow timing. Investment payback evaluates recovery of invested funds, while annual ROIC measures performance relative to invested capital; the supplied EBITDA figures establish none of these return outcomes.
This template fits an agency planning ordinary skilled and aide visits through purchased clinical services and a small management team.
Use the model to compare visit availability, pricing, overhead, and management hiring before committing funds. Estimated inputs require local review; published references in the companion do not independently verify the selected prices, staffing, capacity, or funding.
These answers clarify the editable inputs, operating scope, and financial interpretation.
You can edit offered monthly visit slots, annual utilization, discipline shares, realized visit prices, and launch timing to build the agency’s revenue forecast.
This case models private-pay, fee-for-service visits and excludes Medicare, Medicaid, and bundled reimbursement.
No separate staffing limiter is documented; utilization applies to offered visit slots, so users must check clinical availability independently.
Purchased clinical visits are charged through COGS; Payroll separately covers the RN clinical supervisor, care coordinator, and agency administrator.
The declared workbook includes Income Statement, Cash Flow, Balance Sheet, and Low, Base, and High scenario reports; the supplied case provides numerical results only through EBITDA.
Positive EBITDA alone establishes neither investment payback nor cash sufficiency; review the Cash Flow and Returns reports using the relevant investment, working-capital, and financing inputs.
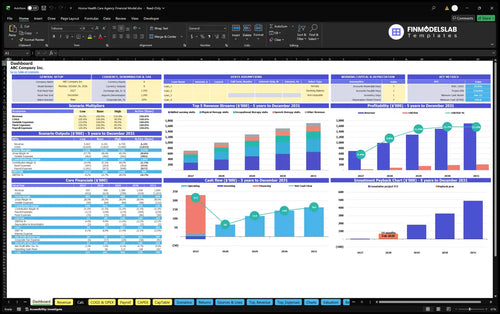
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
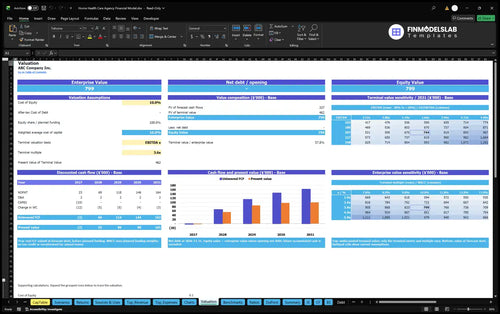
DCF valuation and sensitivity analysis.
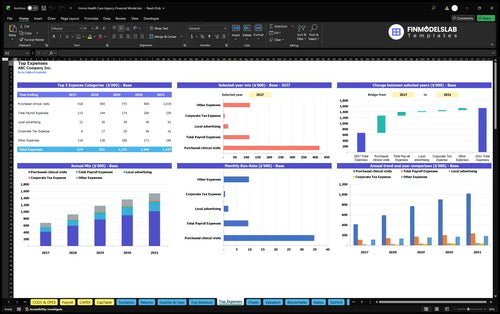
Largest costs and spending trends.
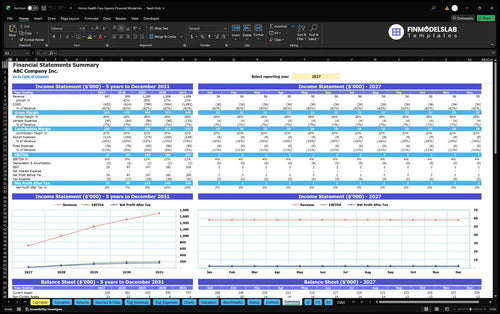
Annual and monthly financial performance.
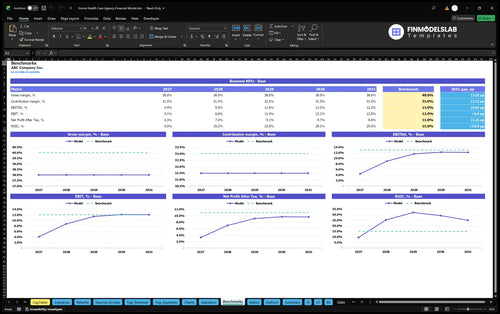
Compare margins and returns to benchmarks.

I could keep pricing, staffing costs, and growth assumptions in one place instead of chasing them across tabs. It saved me a few hours and made the plan easier to explain.

I was nervous about formula errors, but this template made the structure easy to follow and quick to check. That gave me a cleaner model before my lender call.
The profit view and break-even section made it much easier to spot where the business turns profitable. I had a clearer answer for my meeting and didn’t need to rebuild the math.