

Revenue & calculations
Revenue inputs define paid members, program shares, tuition and launch timing, while the monthly Calc schedule converts them into program-level and total revenue.


This Martial Arts School Financial Model is an Excel template for an owner-operated 2,500-square-foot studio in the Dallas-Fort Worth suburbs. It converts paid memberships, primary-program mix, tuition, staffing, direct costs, operating expenses, startup spending and funding inputs into monthly and annual financial projections.
The illustrated case uses five mutually exclusive recurring programs—Little Dragons, Kids Martial Arts, Teen Martial Arts, Adult Grappling and Adult Striking—so each student is counted once. Cross-training is included, and the operating forecast is documented through EBITDA rather than presented as observed industry performance.
The workbook links operating assumptions to detailed schedules, financial statements, management reports and model checks.
Revenue inputs define paid members, program shares, tuition and launch timing, while the monthly Calc schedule converts them into program-level and total revenue.
COGS & OPEX separates direct, variable and fixed costs, and Payroll models annual-average FTE, salaries, hiring dates, bonuses and related personnel calculations.
CAPEX schedules studio assets and depreciation, CapTable records equity contributions, Debt supports optional facilities, and Sources & Uses reconciles cash sources with operating and investment needs.
Income Statement, Cash Flow, Balance Sheet, Dashboard, Scenarios, Returns, Valuation, Ratios and other reports summarize the modeled results without replacing the underlying operating schedules.
Edit the operating assumptions, review the resulting statements and use the model to test how membership growth, pricing, staffing and cost structure affect the business.
Change average paid memberships and program mix, then review revenue, margins and break-even outputs to see how operating scale changes results.
Adjust instructor and front-desk FTE or compensation, then compare Payroll expense and EBITDA before committing to a hiring plan.
Separate startup assets, preopening cash items and owner funding, then use Cash Flow and Sources & Uses to review how startup funding differs from operating earnings.
Revenue equals average paid memberships multiplied by each exclusive primary-program share and that program’s monthly tuition.
The demand-based case starts with 110 average paid members per month in 2026 and rises to 225 in 2030. Little Dragons is 20% of members at $125 per month, Kids Martial Arts 35% at $135, Teens 15% at $150, and Adult Grappling 20% at $160.
Adult Striking is the residual 10% share at $150 per month. Because each student has one primary paid membership, the model avoids duplicating revenue when cross-training is included.
The Revenue Forecast shows the membership drivers, program mix, tuition assumptions and resulting revenue by stream. It lets you trace the model from paid member volume and realized monthly prices to the annual sales forecast.
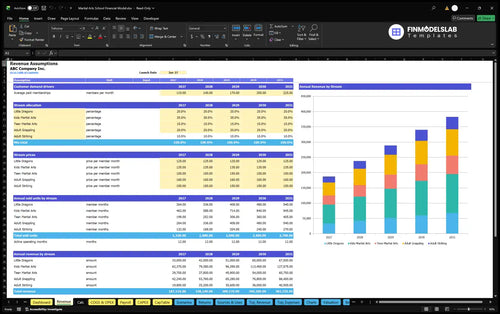
110 average paid members × weighted monthly tuition by exclusive program mix × 12 months = $187,110 annual revenue.
The model separates direct consumables, revenue-linked operating costs, fixed monthly overhead and fixed-base payroll so each payment component is counted once.
The COGS & Operating Expense Forecast separates included belts and welcome uniforms, training and hygiene consumables, payment processing, student acquisition and fixed studio overhead. These inputs feed gross margin, contribution margin and operating expense calculations.
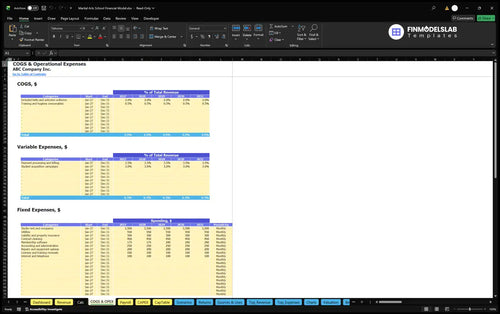
Estimated COGS uses 2% of revenue for included belts and welcome uniforms plus 0.5% for training and hygiene consumables. Variable operating expenses use 3.5% for payment processing and billing plus 3% for student acquisition campaigns.
Fixed coverage includes rent and occupancy, utilities, insurance, cleaning, software, administration, repairs, licenses, internet and telephone. The example studio rent input is $3,500 per month for 12 paid months.
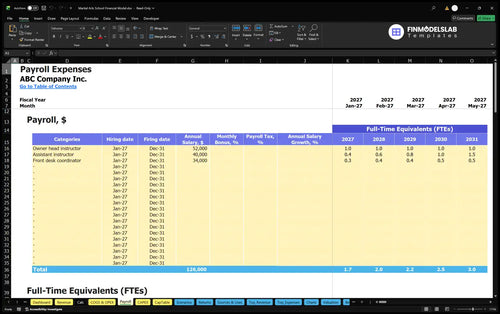
The Payroll Forecast shows annual-average FTE and fixed base pay by role. The case includes a $52,000 owner head instructor, assistant instructor FTE rising from 0.4 to 1.5, and front-desk FTE rising from 0.25 to 0.5.
Startup assets, preopening cash items and owner funding are modeled separately from annual operating expenses and EBITDA.
The Capital Expenditure Plan records durable studio assets and their timing, including the mat floor and wall pads, training equipment, studio fit-out, computers, security and office equipment. CAPEX is distinct from recurring operating expenses.
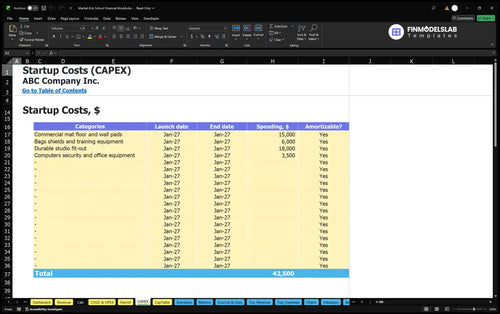
The documented startup assets total $42,500: $15,000 for commercial mat flooring and wall pads, $6,000 for bags, shields and training equipment, $18,000 for durable fit-out, and $3,500 for computers, security and office equipment.
Separate preopening cash items include the lease deposit, setup costs, launch marketing, preopening occupancy and utilities, and one month of training and setup pay. Initial owner funding is $107,519, which includes startup assets, other preopening cash, opening stock and a three-month recurring reserve.
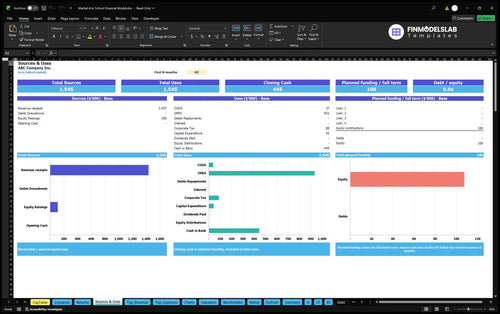
The Sources and Uses of Funds report reconciles equity, debt and internally generated cash sources against operating payments, investment, financing payments and retained cash. In this case, the stated opening funding basis is owner funding with no committed outside financing.
The illustrated case grows revenue from $187,110 in 2026 to $382,725 in 2030 while operating expenses rise more slowly, increasing EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $187,110 | $160,840 | $26,270 |
| 2027 | $238,140 | $176,833 | $61,307 |
| 2028 | $289,170 | $191,905 | $97,265 |
| 2029 | $340,200 | $207,898 | $132,302 |
| 2030 | $382,725 | $231,725 | $151,000 |
Illustrative projections are rounded to whole dollars; underlying model calculations retain the original precision.
The forecast illustrates the effect of higher paid membership volume and a relatively stable program mix while staffing expands in steps. It is a planning scenario, not a historical result or a promise of future performance.
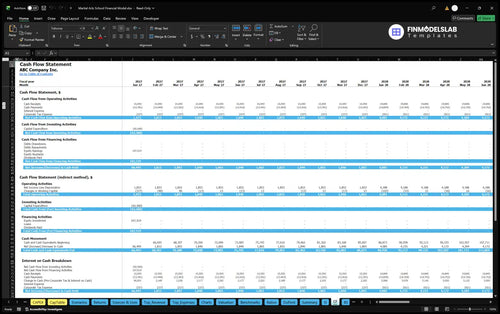
The Cash Flow Forecast shows monthly operating, investing and financing cash movements, including the opening-to-closing cash reconciliation. Use it to examine liquidity and funding requirements rather than treating EBITDA as cash.
The workbook includes separate tools for scenario analysis, sales break-even, cash break-even, investment payback and annual return on invested capital.
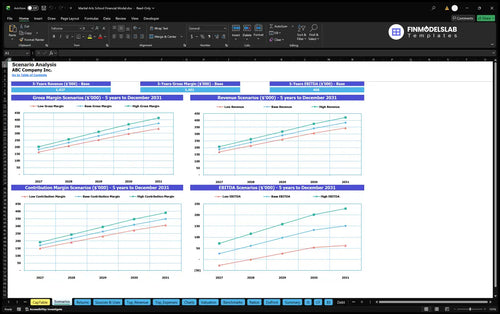
The Financial Scenario Analysis compares Low, Base and High cases using configurable multipliers for revenue, COGS, variable operating expenses, fixed operating expenses and payroll. This shows how operating assumptions change margins and EBITDA across the forecast.
Sales break-even focuses on revenue needed to cover modeled costs, while cash break-even asks when cash generation becomes positive. Investment payback tracks cumulative project cash flow, and annual ROIC compares modeled operating return with invested capital.
These measures answer different questions and should not be inferred from EBITDA alone. The model also provides valuation, ratios and benchmark-comparison reports for broader analysis, but no unseen return, valuation or borrowing result is assumed here.
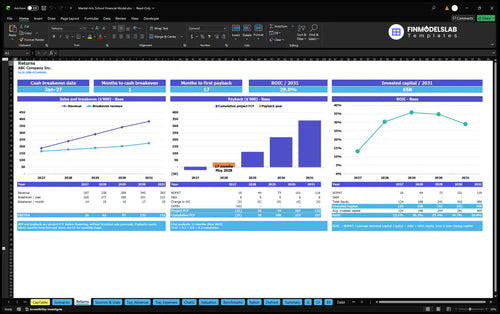
The Return on Invested Capital Analysis brings together break-even, project cash flow, investment payback and annual ROIC calculations. It is designed to evaluate recovery of invested funds and operating returns without conflating those measures with accounting profit or EBITDA.
The template is designed for an independent owner-operated school with recurring memberships, one primary paid program per student and a leased studio footprint similar to the documented case.
It is especially useful when you want to test membership growth, tuition, program mix, instructor staffing, acquisition spending, startup equipment and owner funding in one connected model.
The documented scope excludes childcare, transportation, tournament promotion, franchise royalties and separate retail or private-lesson businesses. Those activities would require additional revenue and cost logic rather than being assumed in the existing forecast.
These answers summarize the model scope, editable inputs and key financial outputs.
Yes. Revenue inputs let you edit paid memberships, exclusive program shares and monthly tuition, which then flow through the monthly revenue calculations and financial reports.
No. Each student has one primary paid membership, while normal cross-training is included without creating a second member or second revenue stream.
Owner, assistant instructor and front-desk compensation are modeled through Payroll using FTE and fixed base pay assumptions, separate from COGS and other operating expenses.
Yes. CAPEX includes mats and wall pads, training equipment, durable fit-out, and computer, security and office equipment, separate from recurring operating expenses.
No. It is an estimated opening funding input covering startup assets, other preopening cash, opening stock and a three-month recurring reserve.
Yes. The workbook includes projected Income Statement, Cash Flow Statement and Balance Sheet reports, supported by operating schedules and model checks.
Yes. Scenario Controls compare Low, Base and High cases using separate multipliers for revenue, COGS, variable expenses, fixed expenses and payroll.
No. EBITDA measures operating earnings before depreciation, interest and tax; cash availability should be reviewed in the Cash Flow Statement and financing schedules.
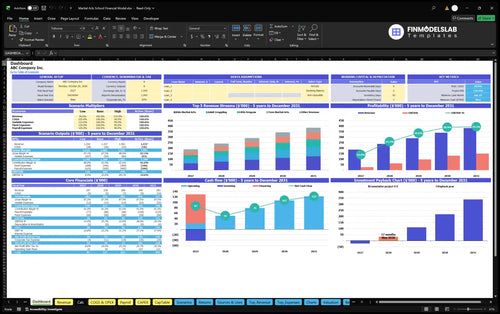
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
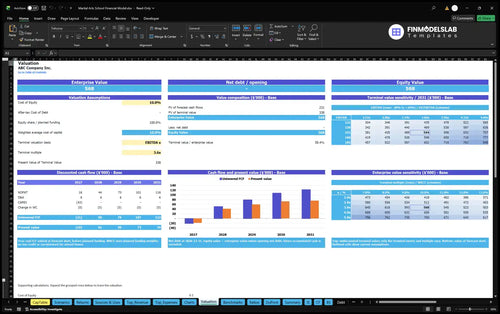
DCF valuation and sensitivity analysis.
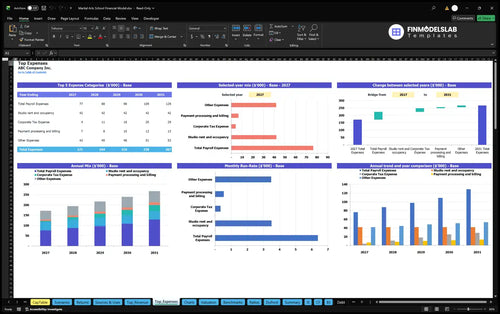
Largest costs and spending trends.
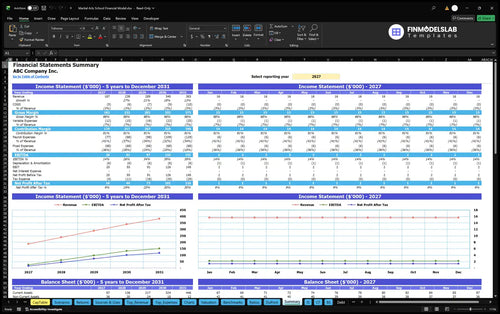
Annual and monthly financial performance.
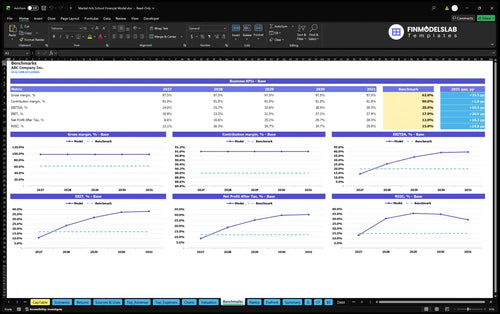
Compare margins and returns to benchmarks.

The built-in formulas kept one bad cell from throwing off the whole model, which saved me a full afternoon of checking. I could trust the numbers before sharing them with my lender.
I used to spend hours building forecasts by hand, but this template got me to a working model in under an hour. That gave me more time to focus on class pricing and staffing.

Starting from scratch always felt like a chore, and this template gave me a clean starting point right away. I had my first draft ready the same day instead of staring at a blank sheet.