
Clearer Reports Fast

This template pulled our scattered statements and charts into one place, so I stopped hunting through files before every update. It cut my prep time by about 4 hours a week and made the numbers easier to share.


This template pulled our scattered statements and charts into one place, so I stopped hunting through files before every update. It cut my prep time by about 4 hours a week and made the numbers easier to share.
Building the microlending model by hand was eating up my evenings, but this template gave me a clean starting point with the key formulas already in place. I finished our first forecast in one afternoon instead of a full week.
I was stuck at a blank spreadsheet, unsure how to structure the model or where the assumptions should go. This template gave me a clear layout to work from, and I had a usable draft ready before the day ended.
The financial model of micro-credits is a five-year paper combining the balances of loans, asset gains, financing costs, interest-free income, scenarios and financial statements.
Use the workbook to plan how property loans, sources of financing, non-interest income, operating costs, staff, capital expenditure and financing affect expected results.
Editable assumptions flow through monthly calculations to annual summaries, low/basic/high comparisons, financial statements and management reports for the selected planning case.
The model calculates the monthly operating income by offsetting interest on financing from credit and other interest on profits and assets and then adding assigned non-interest income.
The average credit balance and other balances on fair value assets with an annual profit per category included shall be reported.
Multiply each average profit and asset balance by annual profit, divided by twelve and the sum of the categories.
Application of annual funding rates to average interest balances, breakdown by twelve and sum of financing costs.
The allocation allowed annual non-interest income over months, using the assumptions of the model on schedule or seasonality.
Subtract interest costs from interest income and add monthly non-interest income to total bank income.
The asset sheet specifies the balances of loans and other commercial assets, annual profits and non-interest contributions that are used to calculate monthly income.
 ASSETS
The OPEX card separates the drivers of variable costs from fixed costs, so operating expenditure is consistent with assumptions regarding modeling and time.
 OPEX
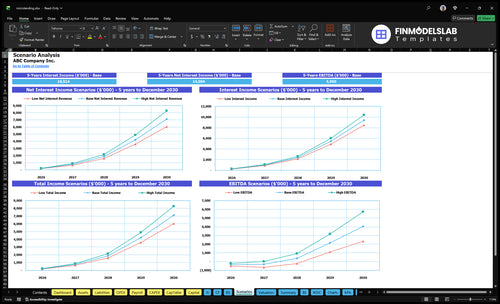
The Scenarios compared low, base and high cases with regard to net interest income, interest income, comprehensive income and EBITDA as compared to the forecast.
 SCENARIOS
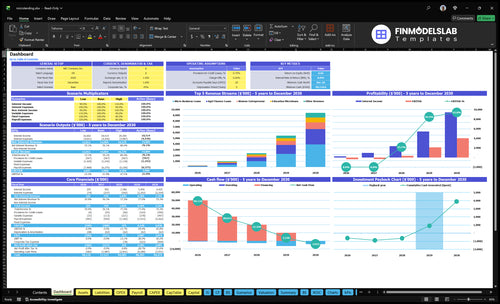
The data table presents selected assumptions, scenarios results, basic finances, revenue mix, profitability, cash flow and return in one management view.
 DASHBOARD
The model is designed to fit microcredit planning, while significant differences in revenue logic, timetables or reporting may require a custom structure.
The template is the starting point of planning, not a guarantee of performance.
The Lab financial models can build or adapt a model when you need different revenue logic, operational schedules or financial reporting.
ORDER A CUSTOM FINANCIAL MODELAfter check-out, you will receive a fully editable microcredit workbook with five-year projections, monthly details, scenario analysis and financial reports.
Download the fully editable model and change the assumptions to your own plan.
Review 60 months of forecast with monthly and annual financial details.
Compare low, base and high cases from the model scenario perspective.
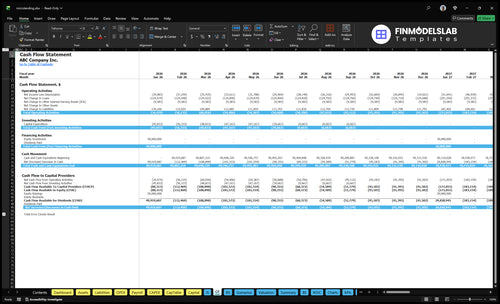
Use Income Account, Cash Flow Statement, Balance, Dashboard and Summary.
The basic answers are visible in their entirety, without clicking on the accordion.
It calculates monthly interest income by category ‘assets valuation’ and subtracts interest financing costs for the purpose of obtaining NII and adds the assigned non-interest income.
You can edit balances and earnings, finance balances and rates, interest-free income, assumptions about schedule and seasonality.
They compare alternative paths for net interest income, interest income, total income and EBITDA in the whole forecast.
In the Workbook There Is a Statement of Revenue, Statement of Cash Flow, Balance Sheet, Dashboard, Summary, Written and Additional Management Reports.
Yes. The Financial Models Laboratory can build or adjust revenue logic, operational schedules and reporting around different requirements.
This is a forecast based on assumptions for the edition, not a guarantee of financial results or business results.
You get a comprehensive and user-friendly microloan projection template designed to help you build a detailed financial forecast for your lending business.
Core inputs and core outputs
Three scenario analysis
Presentation ready
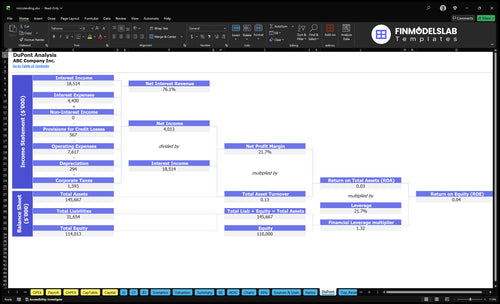
DuPont analysis
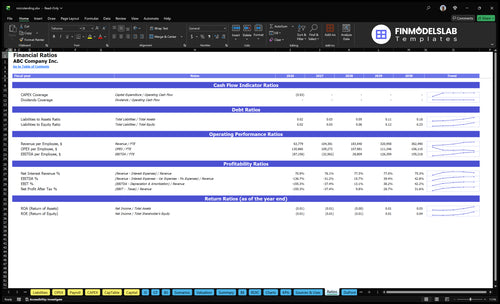
Researched revenue assumptions
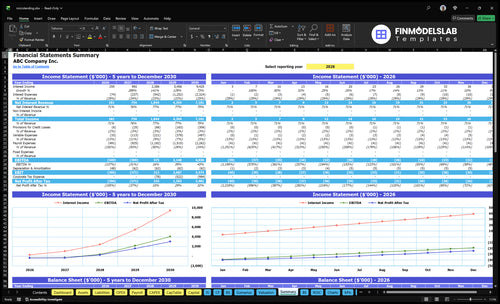
Lender-friendly financial outputs
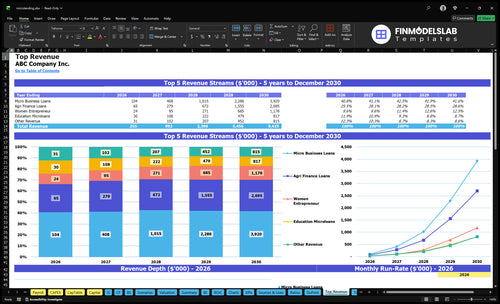
Revenue stream detailed view
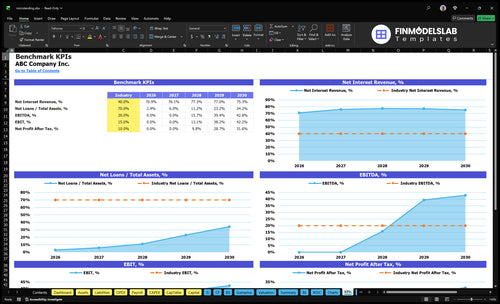
Performance metrics benchmark