

Revenue and Calc
Set traffic, conversion, transaction size, merchandise mix, and prices. Monthly calculations allocate sold items once and consolidate revenue.


The Pet Supply Store Financial Model is an Excel template for a 2,000-square-foot suburban pet retailer. It forecasts merchandise revenue, costs, staffing, and EBITDA for 2026–2030 from customer activity and category prices.
The example launches January 31, 2026, and includes that full month. It sells shelf-stable goods without animals, grooming, veterinary services, or shipping; all case inputs are estimates rather than observed local results.
The workbook connects editable retail assumptions to monthly calculations, financial statements, funding schedules, and decision reports.
Set traffic, conversion, transaction size, merchandise mix, and prices. Monthly calculations allocate sold items once and consolidate revenue.
Separate merchandise costs, fees, overhead, and role salaries to avoid double counting.
Edit working-capital days and Low, Base, and High multipliers to compare operating cases.
Plan fixtures, equity contributions, and optional financing apart from sales activity.
Inspect the Income Statement, Cash Flow, Balance Sheet, Returns, Sources & Uses, Valuation, and Checks.
Monthly merchandise sales equal converted visits multiplied by items purchased and the category-weighted selling price.
The example assumes 1,500 monthly store visits and 65% purchase conversion in 2026, rising to 2,500 visits and 72% conversion in 2030. Each completed purchase contains an estimated 2.2 items, with no additional routine replenishment seasonality applied.
Each sold item is assigned once: 50% pet food, 20% treats and chews, 10% toys, 10% collars, beds and accessories, and the residual 10% litter and hygiene. Category prices are editable for each forecast year.
The Revenue Forecast links store visits, conversion, items per purchase, product mix, and category selling prices to monthly and annual merchandise sales. Changing an input updates the relevant revenue line rather than multiplying the same customer basket across all categories.
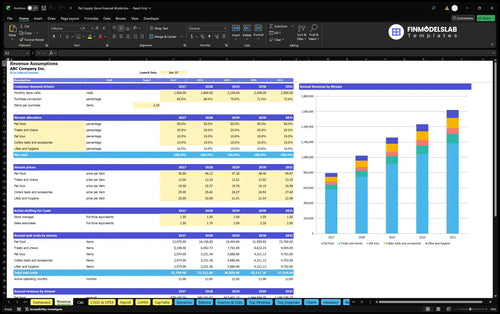
1,500 visits per month × 65% conversion × 2.2 items × $30.90 weighted price × 12 months = $795,366 revenue.
| Category | Item share | Price per item |
|---|---|---|
| Pet food | 50% | $45 |
| Treats and chews | 20% | $12 |
| Pet toys | 10% | $15 |
| Accessories and beds | 10% | $25 |
| Litter and hygiene | 10% | $20 |
The five category shares sum to 100% of items sold; prices are illustrative inputs.
Price assumptions progress through 2030, including pet food reaching $49.67 per item and treats reaching $13.25. Store traffic, conversion, and realized item pricing can therefore be tested as separate drivers of the annual sales increase.
The model separates revenue-linked merchandise costs and transaction expenses from monthly overhead and salaried staff.
Merchandise COGS totals 62.5% of revenue: 60% purchases, 1.5% inbound freight, and 1% shrink. Variable operating expenses add 5% for card processing, checkout supplies, and local marketing.
Fixed costs include rent and common-area charges, utilities, insurance, POS software, bookkeeping, cleaning, security, and renewals. Monthly rent rises from $5,000 in 2026 to about $5,628 in 2030.
The COGS and Operating Expenses report separates merchandise procurement, freight, shrink, transaction-related expenses, and monthly store overhead. It makes gross margin and operating cost sensitivity visible when revenue changes.
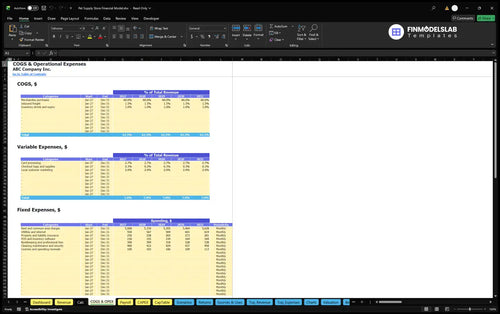
| Expense category | 2026 | 2030 |
|---|---|---|
| COGS | $497,104 | $1,013,037 |
| Variable expenses | $39,768 | $81,043 |
| Fixed expenses | $81,000 | $91,166 |
| Payroll | $109,000 | $145,000 |
Payroll is separate from COGS, variable expenses, and fixed expenses.
The Payroll Forecast calculates staffing and salary expense by role. This case has one store manager at $55,000 annual base pay and sales associates at $36,000 per full-time equivalent, with associate staffing increasing from 1.5 to 2.5 FTE.
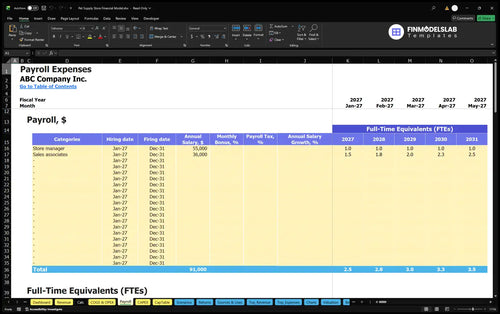
Base payroll is $109,000 in 2026 and $145,000 in 2030. Case figures exclude employer taxes, benefits, and personal taxes, although the workbook offers payroll controls.
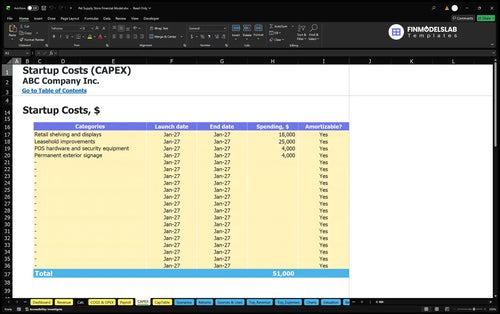
The store budgets opening assets, preopening cash, inventory needs, and initial equity separately from recurring EBITDA.
Startup assets total $51,000: shelving and displays ($18,000), leasehold improvements ($25,000), POS and security ($4,000), and signage ($4,000). CAPEX tracks their purchase timing and depreciation.
The Capital Expenditure Plan schedules fixtures, improvements, equipment, and signage by purchase date. It also tracks depreciation and net book value for financial reporting without treating these initial asset purchases as recurring operating expenses.
Working-capital settings are zero receivables days, 45 inventory days, and 15 payables days. Lease deposits, permits, opening marketing, training, and preopening occupancy are separate cash items.
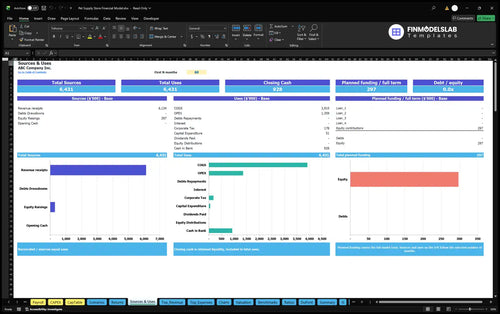
The Sources and Uses of Funds report organizes the money entering the business and the cash allocated to operating, investing, and financing purposes. It helps trace opening equity and planned spending without confusing contributed capital with sales.
In this estimated case, growth in visits, conversion, and prices increases revenue and EBITDA across the five forecast years.
| Year | Revenue | Operating expenses | EBITDA |
|---|---|---|---|
| 2026 | $795,366 | $726,872 | $68,494 |
| 2027 | $1,023,339 | $892,184 | $131,155 |
| 2028 | $1,259,941 | $1,063,393 | $196,548 |
| 2029 | $1,434,525 | $1,192,815 | $241,710 |
| 2030 | $1,620,860 | $1,330,246 | $290,613 |
Scenario results are illustrative, rounded to whole dollars; expenses include COGS, variable and fixed costs, and payroll.
Projected EBITDA rises from $68,494 in 2026, about 8.6% of revenue, to $290,613 in 2030, about 17.9%. These are operating earnings before depreciation, interest, and taxes, not net profit or cash available to owners.
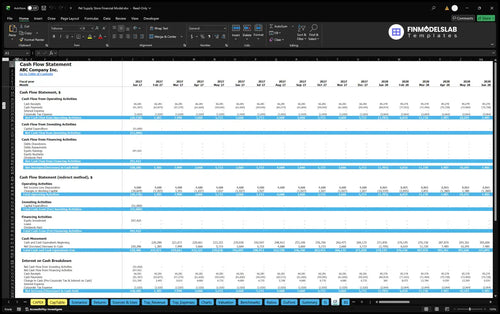
The Cash Flow Forecast presents cash receipts, operating payments, investing activity, and financing movements in monthly periods. Use it to investigate liquidity effects from inventory timing, store fit-out, and equity funding that are not captured by EBITDA alone.
The Returns and scenario reports support distinct questions about sales coverage, cash recovery, operating returns, and downside exposure.
Sales break-even tests revenue needed to cover operating costs; cash break-even tests project cash-flow timing. Payback tracks cumulative project cash flow, while annual ROIC relates operating return to invested capital. None is interchangeable with EBITDA.
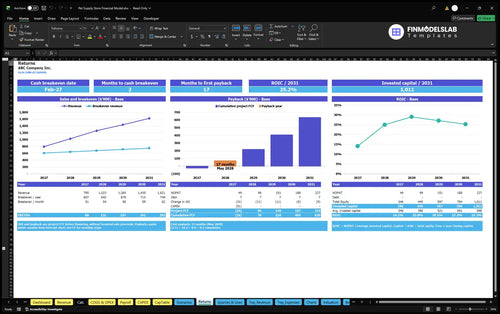
The Returns report compares revenue with sales break-even requirements and tracks project free cash flow, investment payback, and return on invested capital. It separates the timing of cash recovery from the annual accounting profitability shown in the operating forecast.
Low, Base, and High Dashboard multipliers adjust revenue, COGS, variable costs, fixed costs, and payroll to show how demand or spending changes EBITDA. These are scenarios, not observed results.
The template suits planning an independent merchandise-focused pet store before finalizing its location, staffing, and opening investment.
Use it to test whether expected neighborhood traffic, purchase conversion, product mix, salaries, inventory days, and rent can support the desired operating margin. The baseline excludes live animals, grooming, clinical services, and shipping, so those activities would need different economics.
Additional workbook views include Valuation, Ratios, Benchmarks, Top_Revenue, Top_Expenses, and model Checks. Benchmark fields are comparative controls, not proof that the estimated store inputs match a local industry average.
These answers clarify the assumptions, scope, and interpretation of the model before you use it.
Yes. Revenue inputs include monthly visits, purchase conversion, items per sale, category allocations, and annual prices that flow into monthly sales calculations.
No. It calculates one item pool from converted purchases and distributes those items across five nonoverlapping merchandise categories.
The Payroll sheet uses role-level base salaries and annual FTE plans; the example starts with one store manager and 1.5 sales associate FTE.
Yes. CAPEX handles startup assets, while inventory, receivable, and payable day inputs inform working capital; Sources & Uses covers funding and allocation.
No. The example ends at EBITDA; the workbook contains separate financial statements for net profit and cash movement calculations.
Yes. Dashboard scenario controls and the Scenarios sheet compare Low, Base, and High assumptions for revenue, costs, margins, and EBITDA.
No. The documented example covers in-store sales of shelf-stable merchandise only, with no grooming, veterinary services, live animals, or shipping.
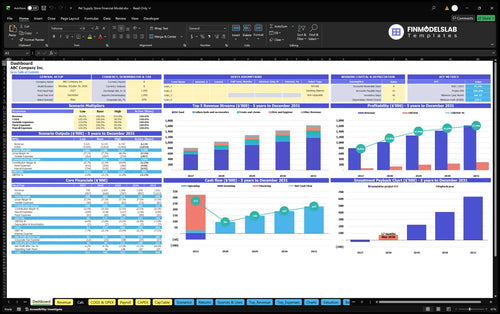
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
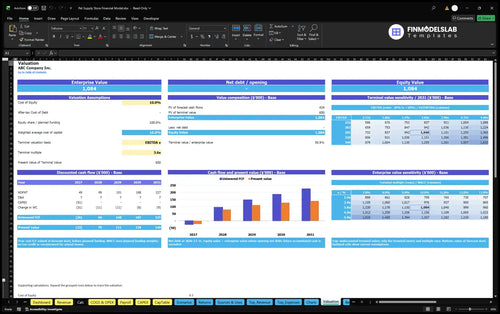
DCF valuation and sensitivity analysis.
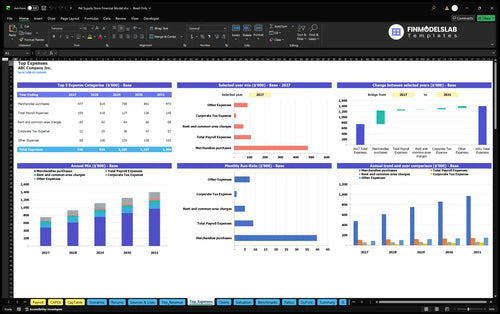
Largest costs and spending trends.
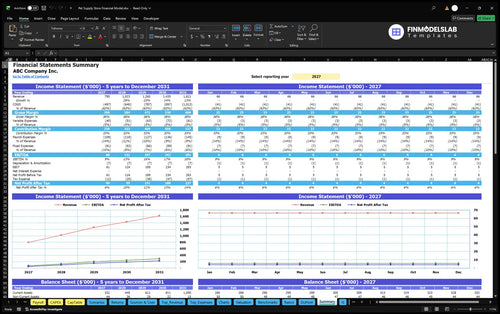
Annual and monthly financial performance.
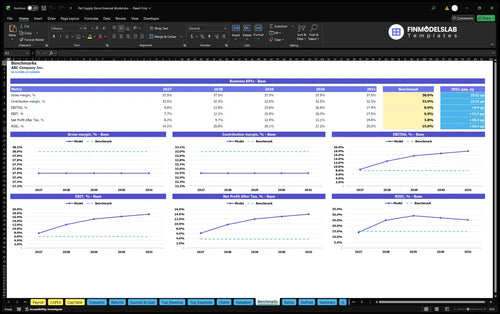
Compare margins and returns to benchmarks.

Building our pet store forecast by hand was eating up whole afternoons. This template cut that work down to about an hour, and I could move on to pricing and inventory planning.

Starting from a blank sheet felt like too much, and I kept stalling out. With this model, I had a clear place to begin and got a draft ready the same day.
I used to waste time juggling low, base, and high cases in separate files. Here, the scenarios were already set up, so I could compare them in minutes and book a lender call sooner.