

Order Drivers and Monthly Sales
Revenue provides order demand, service days, basket prices and mix. Calc allocates the resulting paid-order pool to monthly sales.


The Pizza Restaurant Financial Model is an editable Excel template that converts paid orders, menu-basket prices, staffing, operating costs and opening investments into a five-year restaurant forecast. It connects the operating assumptions to monthly calculations and financial reporting for 2026 through 2030.
The illustrative business is an independent, 1,600-square-foot neighborhood pizzeria in suburban Columbus, Ohio. It serves counter customers and pickup orders, including prepaid party bundles, without alcohol, delivery vehicles, marketplace commissions or franchise fees.
The workbook connects pizza order assumptions to operating statements, funding schedules and decision-oriented financial reports.
Revenue provides order demand, service days, basket prices and mix. Calc allocates the resulting paid-order pool to monthly sales.
COGS & OPEX separates direct, variable and fixed costs. Payroll calculates salaries and staffing by role.
CAPEX schedules opening assets; CapTable and Debt capture contributions and financing. Sources & Uses and Cash Flow trace funding.
Dashboard and financial reports support analysis; Checks identifies input or reconciliation issues. Supplied numeric projections stop at EBITDA.
One demand-based pool of paid orders is split across five mutually exclusive meal baskets and priced once.
The 2026 case assumes 75 daily paid orders across 26 monthly service days. Daily demand rises to 90, 105, 115 and 125 through 2030, without a separate capacity limiter.
Five baskets contain the pizza, sides and nonalcoholic drinks purchased together: classic whole-pizza orders ($18; 25%), specialty whole-pizza orders ($24; 35%), personal meals ($13; 20%), family bundles ($42; 17%) and prepaid party pickup bundles ($110; 3%).
The Revenue Forecast shows how daily paid-order demand, monthly service days, basket mix and net prices determine sales by category. Its annual totals link to monthly calculations rather than five independent customer-demand forecasts.
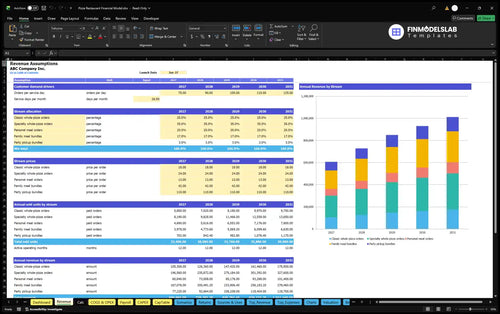
75 daily orders × 26 service days × 12 months × $25.94 weighted net basket price = $606,996 annual revenue.
Basket shares total 100%, assigning each paid order once. January 2026 is modeled in full despite the January 31 launch-date setting; sales tax and tips are excluded.
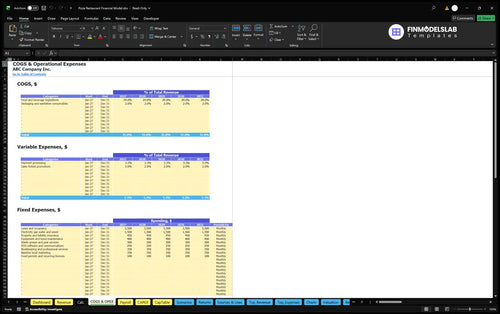
The operating plan separates percentage-based direct costs and selling costs from fixed monthly expenses and staff salaries.
Food and beverage ingredients use 29% of sales and packaging and sanitation consumables use 2%, for combined cost of goods sold of 31%. Payment processing is another 3.3% of sales; sales-linked promotions add 2% in variable operating expenses.
Fixed expenses total $86,400 annually, including $3,500 monthly occupancy, utilities, insurance, maintenance, services, software, bookkeeping, marketing and permits.
The COGS and Operating Expenses report separates direct food costs, variable selling costs and recurring overhead. Changing those assumptions changes gross margin, contribution margin and the operating expense burden without treating payroll as a second ingredient cost.
| Expense category | 2026 | 2030 |
|---|---|---|
| COGS | $188,169 | $313,615 |
| Variable expenses | $32,171 | $53,618 |
| Fixed expenses | $86,400 | $86,400 |
| Payroll | $226,500 | $304,000 |
| Total expenses | $533,240 | $757,633 |
Each amount is rounded from the underlying planning assumptions; payroll is counted only once.
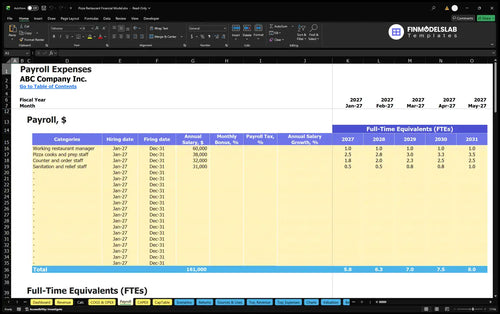
Payroll starts with one working owner-manager at a $60,000 annual base, plus 2.5 cook/prep FTE, 1.75 counter FTE and 0.5 sanitation/relief FTE. By 2030 those three employee groups grow to 3.5, 2.5 and 1.0 FTE, respectively.
The Payroll Forecast tracks annual-average FTE, salary rates and staffing by restaurant role. With fixed per-FTE base pay, its calculated payroll grows from $226,500 in 2026 to $304,000 in 2030, independently of the percentage-based food and transaction costs.
Initial equipment, preopening payments, working capital and owner contributions are planned separately from EBITDA.
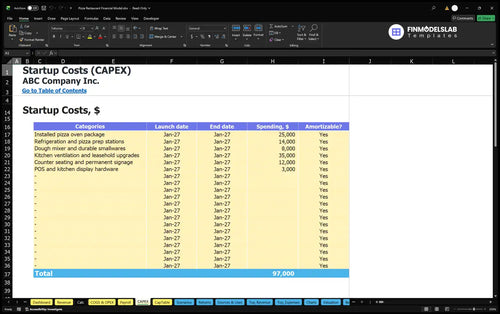
Opening assets include a $25,000 oven, $14,000 refrigeration and prep stations, $8,000 mixer and smallwares, and $35,000 ventilation and leasehold improvements, plus seating, signage and POS hardware.
The Capital Expenditure Plan organizes the timing and cost of installed equipment and leasehold assets. Its depreciation schedule is a separate financial-statement calculation; the case’s annual operating figures are documented only through EBITDA, before depreciation.
Preopening cash covers deposits, inspections, services, marketing, training and wages, separate from recurring expenses. Estimated initial owner funding is $272,356, without committed external financing.
The Sources and Uses of Funds report organizes the sources of capital and the planned allocation of cash. It can help trace the owner’s contribution to opening investments, prelaunch spending, working capital and retained cash without confusing funding with revenue.
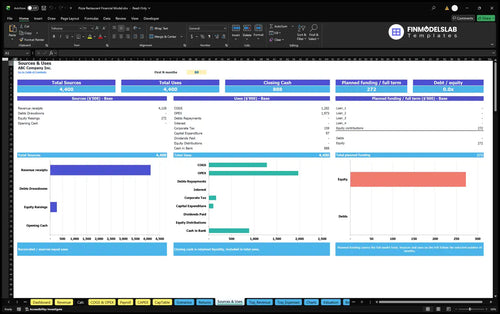
Working capital assumes zero receivable days, seven payable days and ten inventory days. Estimated funding covers opening assets, cash needs, working capital and three months of recurring outflows; cash sufficiency is unproven.
The documented case projects growing paid orders, higher revenue and EBITDA after direct, variable, fixed and staff costs.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $606,996 | $533,240 | $73,756 |
| 2027 | $728,395 | $594,807 | $133,588 |
| 2028 | $849,794 | $664,125 | $185,669 |
| 2029 | $930,727 | $711,004 | $219,723 |
| 2030 | $1,011,660 | $757,633 | $254,027 |
Illustrative projections, not actual restaurant results or industry averages. Displayed whole-dollar rounding can produce minor differences.
Annual revenue rises from $606,996 in 2026 to $1,011,660 in 2030 as daily orders increase while the selected basket prices and mix remain constant. EBITDA improves from $73,756 to $254,027, but those operating earnings do not establish net profit or available cash.
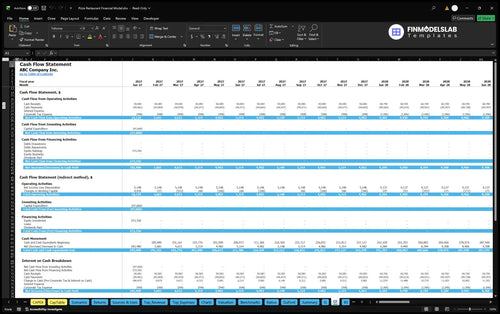
The Cash Flow Forecast distinguishes operating cash receipts and payments from purchases, capital contributions and financing transactions. It offers a separate liquidity view because projected restaurant EBITDA cannot establish closing cash, borrowing needs or the investment payback date.
Income Statement, Balance Sheet, Summary and Checks are included, but the supplied operating figures stop at EBITDA. No net-income or closing-cash projections are supplied.
Break-even analysis and investment metrics address different decisions than the annual EBITDA totals.
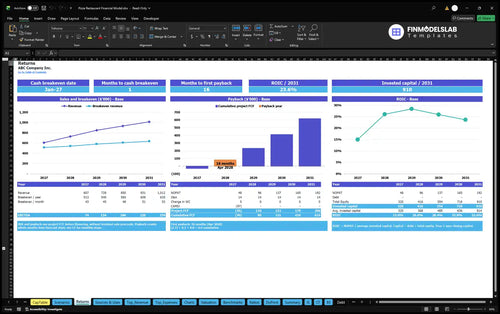
The Returns sheet covers sales break-even requirements, cash break-even timing, investment payback and annual return on invested capital. Sales break-even compares operating sales with costs; cash break-even examines cash timing; payback tracks investment recovery; ROIC measures returns against invested capital.
The Returns report brings together operating break-even, project cash flows, investment payback and ROIC. Those calculations require their underlying cash and invested-capital inputs; the illustrative EBITDA amounts alone do not demonstrate a payback period or return percentage.
Dashboard controls compare Low, Base and High sales and cost assumptions. Debt controls support optional financing, but the case assumes no approved loan or borrowing.
The model supports operating and funding decisions for an independent counter-service pizza restaurant with pickup sales.
Owners can test order targets, basket mix, ingredient costs and staffing. Expense, funding and cash schedules can inform lender discussions without implying bank approval.
Replace example rent, wages, permits, supplier prices and startup costs with site-specific inputs. Delivery, alcohol and other formats require different assumptions.
These answers clarify the selected example assumptions and the financial analyses available in the workbook.
Yes. Edit the five mutually exclusive basket prices, shares, daily order demand and service days in Revenue to recalculate monthly sales.
No. This documented case covers counter service and pickup with nonalcoholic baskets; it does not assume delivery marketplace fees, a delivery fleet or alcohol revenue.
No. The documented planning rule activates the full selected launch month, so the illustrative January 2026 month is included.
No. Owner-manager and employee base salaries are allocated to Payroll, separate from ingredient COGS, sales-linked variable costs and fixed operating expenses.
No. The $254,027 projected EBITDA precedes depreciation, financing costs, taxes and other items needed to calculate net profit.
No. The $272,356 initial owner funding amount is an estimated planning input, not proof of cash sufficiency; review cash flows and funding needs under alternative assumptions.
Yes. The workbook includes Low, Base and High comparisons, break-even, payback, ROIC and valuation reports, but the supplied example does not establish their numerical results.
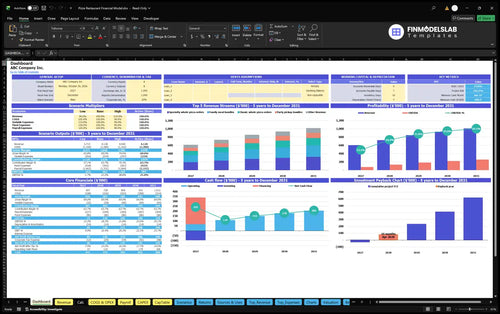
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
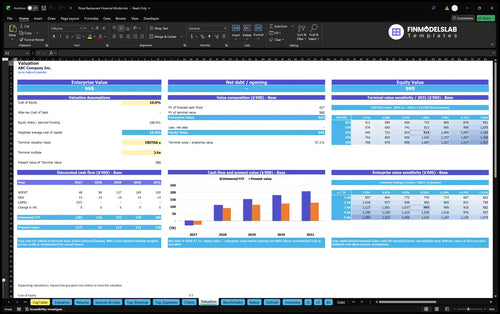
DCF valuation and sensitivity analysis.
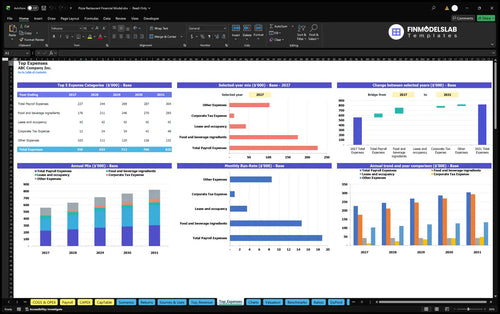
Largest costs and spending trends.
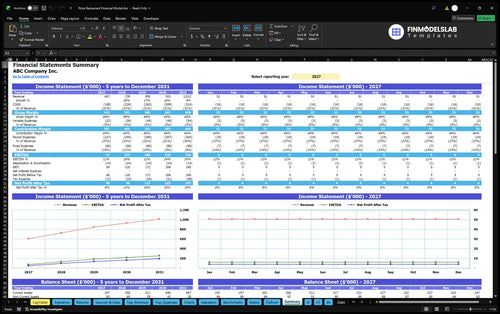
Annual and monthly financial performance.
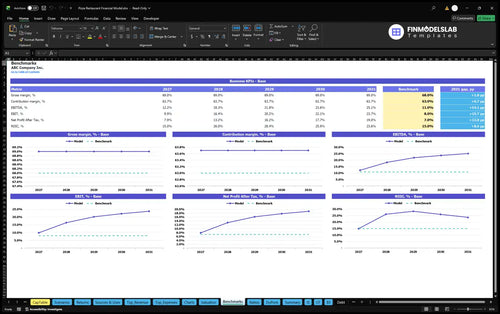
Compare margins and returns to benchmarks.

This template made low, base, and high cases easy to compare without rebuilding the model three times. I had the scenarios lined up in under an hour, which made planning with my partner much smoother.

Building the pizza shop financials by hand would have eaten up my whole week, but this file got me to a clean first draft fast. I saved at least 10 hours and could focus on the menu and opening plan instead.
I wasn’t sure what investors wanted to see, but this model gave me the right structure and outputs right away. It helped me prepare a cleaner deck and book a lender meeting with less back-and-forth.