

Revenue and Calc
Edit utilization, grade mix, and prices to calculate monthly pounds sold and revenue.


The Textile Recycling Financial Model is an Excel template for a US dry textile sorting, wiping-cloth cutting, and mechanical fiber-opening plant. Monthly production, grade prices, and operating costs drive financial projections for 2026–2030.
The illustrated Midwestern plant leases 10,000 square feet and sells five recovered textile grades wholesale ex works. Chemical recycling, spinning, laundry, retail, and charged collection services are excluded.
Editable assumptions feed monthly calculations and financial reporting.
Edit utilization, grade mix, and prices to calculate monthly pounds sold and revenue.
Plan direct, variable, and fixed expenses alongside separate role-based payroll.
Schedule equipment investment, owner equity, and optional debt payments.
Review monthly earnings, liquidity, financial position, and combined reports.
Compare scenarios, break-even and returns, and model reconciliation checks.
Revenue starts with installed monthly saleable capacity and utilization, then divides the resulting pounds across five wholesale product grades.
Installed saleable output is 167,200 pounds monthly. The model applies utilization and active-month timing, then allocates sold pounds once using grade weights of 10, 35, 10, 20, and 20 divided by 95.
The 2026 illustrative utilization of 55% produces 91,960 sold pounds monthly. Annual utilization rises to 65%, 73%, 80%, and 85% through 2030, while each outlet grade has its own year-specific price per pound.
The Revenue Forecast shows utilized production volume, grade allocations, prices, and sales. Its monthly Calc schedule uses one capacity pool across all five grades, preventing duplicate volume.
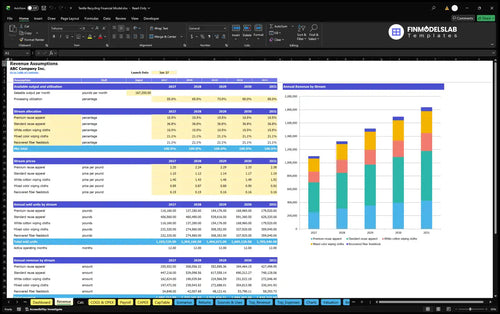
| Output grade | Share | Price/lb | Monthly sales |
|---|---|---|---|
| Premium reuse apparel | 10.53% | $2.20 | $21,296 |
| Standard reuse apparel | 36.84% | $1.10 | $37,268 |
| White cotton wiping cloths | 10.53% | $1.40 | $13,552 |
| Mixed color wiping cloths | 21.05% | $0.85 | $16,456 |
| Recovered fiber feedstock | 21.05% | $0.15 | $2,904 |
Percentage shares are displayed rounded; calculations use the exact 10:35:10:20:20 weights divided by 95.
167,200 saleable pounds/month × 55% utilization = 91,960 sold pounds/month; grade-level sales total $91,476 monthly, or $1,097,712 over 12 active months.
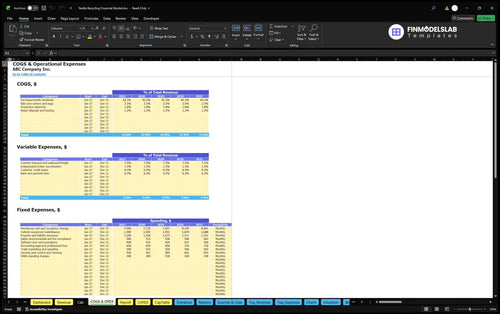
Direct costs and variable spending move with revenue, while the facility budget and fixed base salaries are planned separately.
Selected direct-cost assumptions include purchased feedstock at 42.33% of revenue, packaging at 2.5%, electricity at 1.8%, and disposal at 1.2%. Variable inputs cover freight at 7.5%, broker commissions at 1.5%, customer credit losses at 0.5%, and payment fees at 0.3%.
Fixed expenses cover warehouse rent, maintenance, insurance, compliance, software, professional fees, marketing, security, and standing utility charges. Illustrative 2026 occupancy costs are $7,500 per month.
The COGS and Operating Expenses report separates direct and variable charges from scheduled fixed costs. Compare how spending responds to sales versus unused processing capacity.
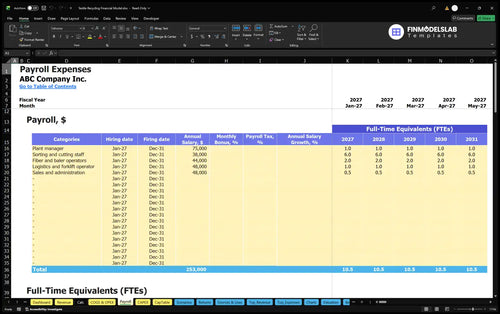
The staffing plan has 10.5 annual-average FTE: one manager, six sorting/cutting staff, two fiber/baler operators, one logistics operator, and 0.5 sales administrator. Fixed annual base salaries total $463,000.
The 2026 case includes $525,014 direct costs, $107,576 variable expenses, $157,200 fixed expenses, and $463,000 payroll. Salaries are excluded from other cost pools.
The Payroll Forecast connects role-level FTE and salaries to monthly staff costs. Adjust staffing to examine the effect of fixed base pay on EBITDA.
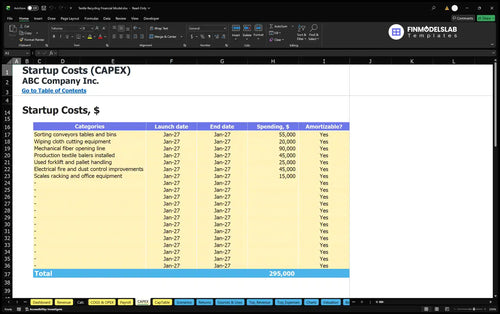
The startup budget separates production assets, opening cash items, working-capital requirements, and financing sources from annual operating expenses.
Key assets include sorting equipment ($55,000), cutting equipment ($20,000), the fiber-opening line ($90,000), and installed balers ($45,000). Additional items include a forklift, dust/fire improvements, scales, racking, and office equipment.
The Capital Expenditure Plan schedules equipment purchases and depreciation. These investment cash outlays are distinct from recurring operating expenses and feed asset reporting.
Opening cash needs include deposits, permits, preopening payroll, and buyer samples. Working-capital settings are 24 receivable days, 28 inventory days, and 14 payable days.
Estimated initial owner funding of $753,598 covers assets, other opening cash, launch working capital, and three months of recurring cash operating outflows. It is a reserve estimate, not committed financing or tested peak cash sufficiency.
The Sources and Uses of Funds report organizes equity, optional debt, cash receipts, operating payments, and investment spending. Funding is distinct from revenue and EBITDA.
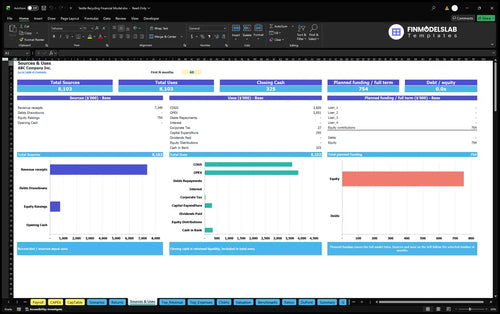
The case illustrates rising revenue as processing utilization increases, with a shift from negative to positive operating EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $1,097,712 | $1,252,790 | -$155,078 |
| 2027 | $1,323,242 | $1,387,474 | -$64,232 |
| 2028 | $1,515,825 | $1,503,313 | $12,511 |
| 2029 | $1,694,403 | $1,611,228 | $83,175 |
| 2030 | $1,836,310 | $1,698,159 | $138,151 |
Planning-case projections, not historical performance or industry averages. Whole-dollar rounding can create small displayed differences.
Revenue rises from $1,097,712 in 2026 to $1,836,310 in 2030; operating expenses rise from $1,252,790 to $1,698,159. EBITDA first turns positive in 2028 at $12,511 and reaches $138,151 by 2030.
EBITDA excludes depreciation, interest, and taxes; it is not net profit or cash available. Monthly Income Statement, Balance Sheet, and Cash Flow reports exist, but their case totals are not supplied.
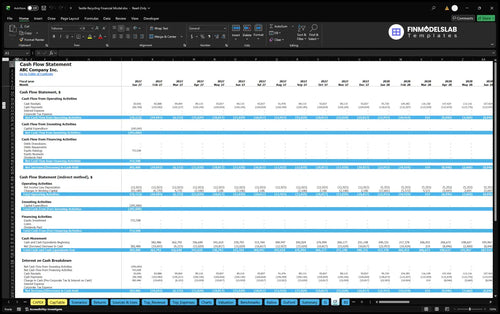
The Cash Flow Forecast tracks operating, investing, and financing cash flows. Receivable, inventory, and payable assumptions affect timing, so positive EBITDA need not imply positive cash.
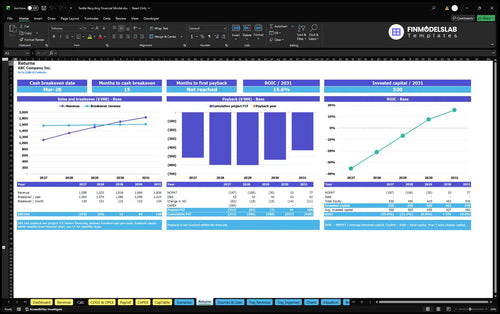
The workbook provides distinct tools for assessing operating break-even, cash break-even, investment payback, and return on invested capital.
Sales break-even tests operating cost coverage; cash break-even tests cash coverage. Payback measures cumulative cash recovery, while annual ROIC measures returns relative to invested capital.
Dashboard Low, Base, and High multipliers adjust revenue, direct, variable and fixed costs, and payroll. The example establishes no break-even date, payback period, ROIC, IRR, or valuation.
The Returns analysis shows operating break-even, cash break-even, investment payback, and ROIC separately. EBITDA alone does not establish investment recovery.
Debt controls support four financing facilities, and Valuation supports discounted cash-flow analysis. This illustrative case provides no loan terms or valuation result.
The template fits one wholesale US plant using dry sorting, wiping-cloth cutting, and mechanical fiber recovery.
Plant owners and advisors can compare throughput, grade mix, wholesale pricing, staffing, equipment investment, and funding. The capacity-based engine is designed for one physical processing line.
Replace estimates with buyer contracts, feedstock quotes, yields, wages, and equipment costs. Collection-fee businesses, chemical recycling, laundry, spinning, and retail operations need different assumptions.
Answers to common questions about editing the assumptions and interpreting the workbook reports.
Yes. Edit annual utilization, illustrated as 55%, 65%, 73%, 80%, and 85% for 2026–2030.
No. All five share one saleable-pound pool, using weights totaling 95 before normalization.
No. Its $463,000 annual base pay excludes employer taxes, benefits, and personal taxes.
Using 24 receivable days, 28 inventory days, and 14 payable days, the workbook models cash and working-capital timing.
Yes. CAPEX plans purchases and depreciation separately from recurring operating expenses.
No. It is estimated owner funding for startup investment and cash needs.
Yes, after entering assumptions; no approved loan or payback date is documented.
No. They are illustrative projections, not observed results, guarantees, or industry averages.
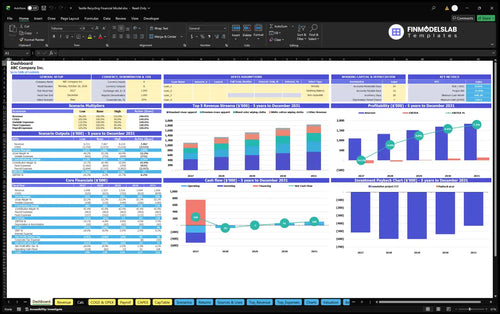
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
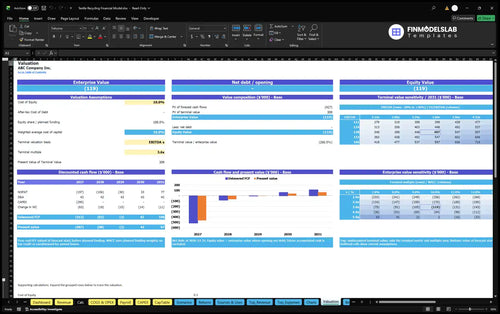
DCF valuation and sensitivity analysis.
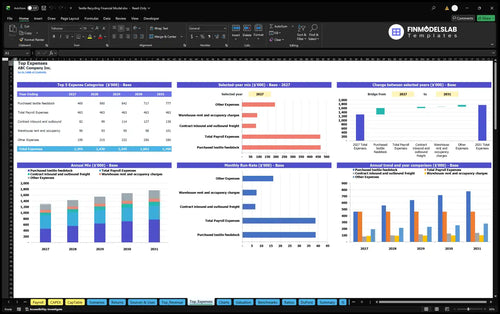
Largest costs and spending trends.
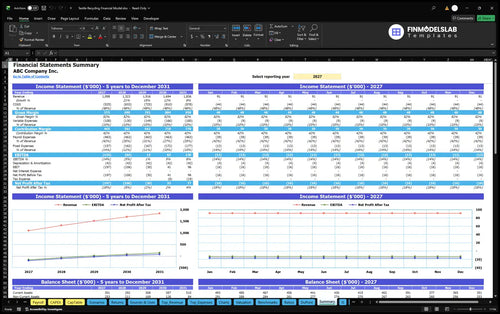
Annual and monthly financial performance.
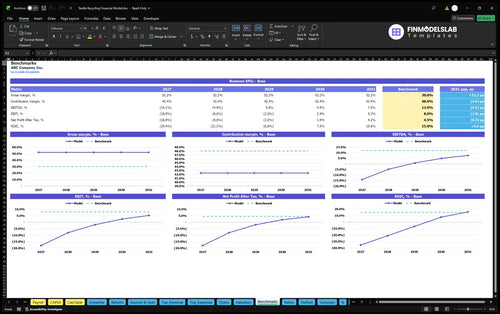
Compare margins and returns to benchmarks.

This template made margins and break-even easy to see, so I spent less time guessing and more time planning. I built a cleaner forecast in under 2 hours and could explain the profit picture without digging through formulas.
I was unsure what investors wanted to see, but the layout gave me the right outputs and structure right away. It helped me prep a meeting in one afternoon and made the numbers easy to walk through.
Switching between low, base, and high cases used to be tedious, but this model made it simple. I cut scenario work from half a day to about 30 minutes and could compare assumptions without rebuilding the sheet.