

Revenue & Calc
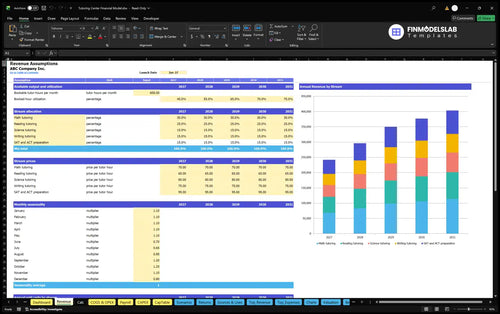
Set bookable tutor-hours, annual utilization, the school-year calendar, and five hourly program prices. Monthly calculations allocate sold hours only once.


The Tutoring Center Financial Model is an Excel template for building monthly financial projections for a one-to-one academic tutoring business. It connects tutor-hour capacity, student bookings, subject prices, staffing, operating costs, startup investment, and financing assumptions to revenue and financial reports.
Its illustrative case models a leased 1,800-square-foot center in Raleigh, North Carolina, from 2026 through 2030. Four salaried tutor FTE share 600 bookable hours monthly across five exclusive programs; the projections are editable planning estimates, not actual results or industry averages.
Editable operating schedules feed integrated financial statements and decision reports.
Set bookable tutor-hours, annual utilization, the school-year calendar, and five hourly program prices. Monthly calculations allocate sold hours only once.
Plan curriculum supplies, processing, marketing, seven recurring overhead categories, and salaried tutor, director, and administrative staffing.
Schedule teaching equipment and center improvements, record owner contributions, and examine funding allocation alongside optional debt facilities.
Review the projected Income Statement, Cash Flow Statement, and Balance Sheet, with a combined Summary and model reconciliation checks.
Compare Low, Base, and High cases, break-even and payback measures, valuation sensitivity, projected financial trends, and entered KPI benchmarks.
Revenue depends on one shared pool of available tutor-hours, booked utilization, seasonal demand, and the hourly mix of five programs.
The case starts with 600 bookable hours each month, not six teaching stations multiplied by individual tutor capacity. Utilization rises from 45% in 2026 to 75% in 2030; the repeating calendar adjusts activity for school-year demand.
Math, reading, science, writing, and SAT/ACT preparation receive exclusive shares of 30%, 25%, 15%, 15%, and 15%. Their prices combine to a $74.75 weighted hourly rate; no hour is sold twice.
The Revenue Forecast translates monthly tutor-hour capacity, utilization, seasonality, subject allocation, and prices into program-level sales. Compare enrollment capacity and pricing before changing the five-year projections.
| Program | Share of hours | Price per hour |
|---|---|---|
| Math tutoring | 30% | $70 |
| Reading tutoring | 25% | $65 |
| Science tutoring | 15% | $80 |
| Writing tutoring | 15% | $75 |
| SAT/ACT preparation | 15% | $95 |
600 monthly hours × 45% utilization × 12 seasonally normalized months × $74.75 per hour = $242,190.
The monthly calendar peaks at a 1.20 multiplier in September and October and dips to 0.65 in July. Its twelve multipliers sum to 12, so the annual calculation reconciles without pretending every month has identical demand.
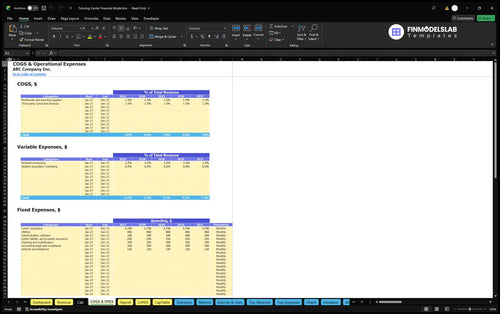
The expense build separates revenue-linked direct and variable costs, fixed center overhead, and fixed base salaries.
Workbooks and curriculum licenses each equal 1.5% of sales, producing combined COGS of 3%. Payment processing adds 3.2% and student acquisition marketing 6% as variable operating expenses.
Center occupancy, utilities, software, insurance, cleaning, professional services, and communications are fixed operating costs. The case holds these at $63,600 per year, including $3,700 monthly occupancy.
The COGS and Operating Expenses report organizes direct materials, curriculum licensing, payment fees, marketing, and fixed center overhead. Its distinct expense schedules help assess gross and contribution margins without burying staff pay in cost of sales.
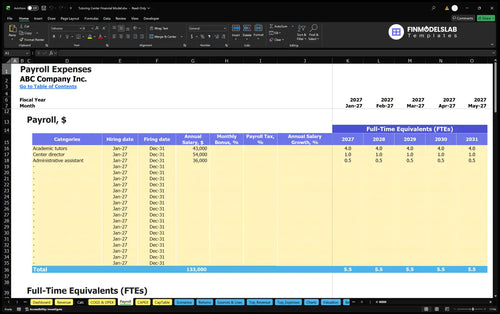
Four tutors earn $43,000 annually per FTE, the center director earns $54,000, and a half-time administrator has a $36,000 full-time base. Together they create $244,000 in annual payroll, counted once.
The Payroll Forecast plans role-level FTE, salaries, hiring dates, and personnel costs. Tutor salaries remain in Payroll rather than appearing again in COGS or fixed center expenses.
The initial owner funding estimate covers startup assets, distinct preopening cash items, opening supplies, and an operating reserve, without treating capital contributions as revenue.
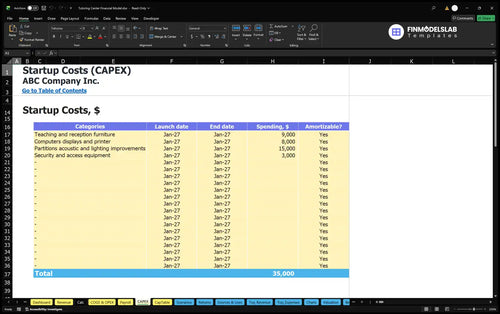
The case budgets $9,000 for furniture, $8,000 for technology, $15,000 for partitions and improvements, and $3,000 for security: $35,000 in startup assets. Occupancy deposits, recruitment, launch marketing, and preopening services are separate cash requirements.
The Capital Expenditure Plan schedules furniture, computing equipment, premises improvements, and security purchases. It separates capital spending and depreciation from the annual operating-cost build.
Estimated initial owner funding is $141,985, including a three-month operating reserve once. The working-capital inputs specify zero receivable days, zero payable days, and 15 inventory days; families prepay and there are no school-district credit contracts.
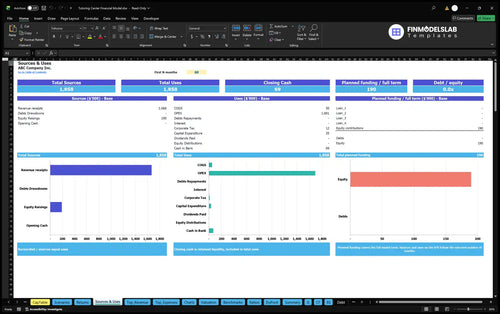
The Sources and Uses of Funds report reconciles modeled equity, any entered borrowing, operating receipts, investment spending, and cash retained. Use it to examine where planned startup resources are allocated rather than reading funding as operating earnings.
Higher booked-hour utilization grows sales while the model holds base payroll and recurring fixed overhead constant in this illustrative case.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $242,190 | $337,147 | -$94,957 |
| 2027 | $296,010 | $343,713 | -$47,703 |
| 2028 | $349,830 | $350,279 | -$449 |
| 2029 | $376,740 | $353,562 | $23,178 |
| 2030 | $403,650 | $356,845 | $46,805 |
Projected annual amounts are rounded to whole dollars; differences of a dollar can arise from display rounding.
In the Base case, EBITDA is slightly negative in 2028 and positive in 2029. This is operating earnings before interest, taxes, depreciation, and amortization, not net profit, free cash flow, or proof that startup funding is sufficient.
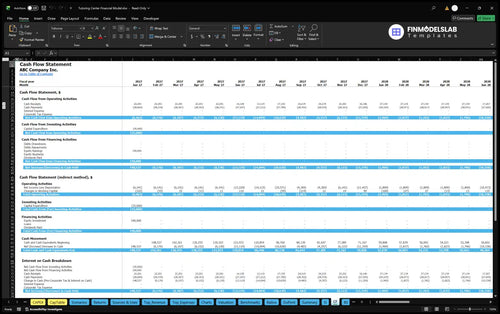
The Cash Flow Forecast shows projected operating receipts and payments, equipment spending, and equity or debt cash movements. Review opening and closing cash to evaluate liquidity separately from EBITDA, especially during early operating losses.
Returns and scenario reports help examine how changes in tutoring demand, costs, and funding affect distinct investment and operating outcomes.
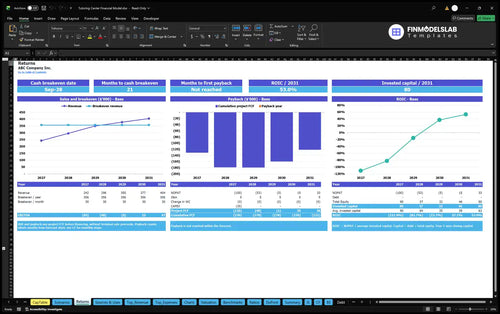
Sales break-even assesses the revenue needed to cover modeled costs; cash break-even tests the timing of cash coverage. Investment payback concerns recovery of invested funds, while annual ROIC compares operating returns with invested capital.
The Returns report compares sales break-even, cash break-even timing, project free cash flow, investment payback, and annual return on invested capital. The provided case does not establish a payback date or ROIC figure.
Dashboard controls allow Low, Base, and High multipliers for revenue, COGS, variable costs, fixed costs, and payroll. The four debt rows support configurable amount, timing, term, interest, and repayment structure when financing is relevant.
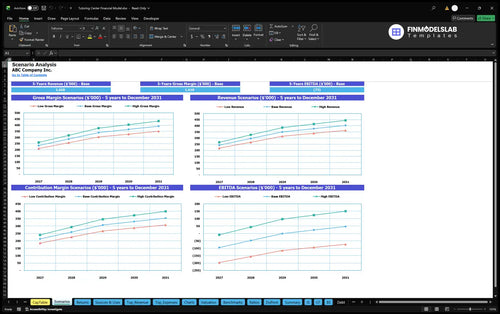
The Financial Scenario Analysis compares revenue and operating margins under Low, Base, and High assumption sets. It helps test whether changing bookings or staffing costs shifts the center toward or away from operating break-even.
Use the template for capacity-limited academic tutoring operations with salaried instructors, subject-specific hourly rates, and parent-paid sessions.
The documented case excludes group-class seat multiplication, childcare, franchise royalties, district contracts, and online marketplace fees. Adjust prices, operating hours, seasonal activity, staffing, opening assets, and scenario inputs if your tutoring format or location differs.
Answers to practical questions about editing assumptions and interpreting the model reports.
Yes. Change the five subject prices, program shares, annual utilization, available tutor-hours, and repeating seasonal multipliers in the operating inputs.
No. Six teaching stations support one shared pool of 600 monthly bookable tutor-hours; subject programs divide sold hours without duplicating them.
Yes. Payroll separately models four tutor FTE, one director, and a half-time administrative assistant with their annual base salaries.
Yes. The case uses revenue-based supplies, curriculum licensing, payment processing, and student acquisition marketing, alongside fixed center operating expenses.
No. It is estimated owner funding for distinct startup assets, preopening cash items, opening supplies, and a reserve, not an annual operating expense.
No. EBITDA excludes investment and financing flows; the Cash Flow and Returns reports evaluate liquidity, payback, and investment returns separately.
Yes. Dashboard Low, Base, and High controls adjust revenue and cost assumptions, with scenario comparisons for profitability.
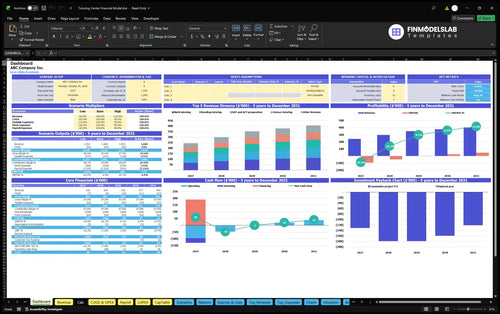
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
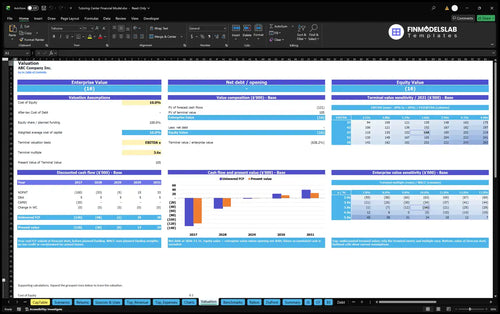
DCF valuation and sensitivity analysis.
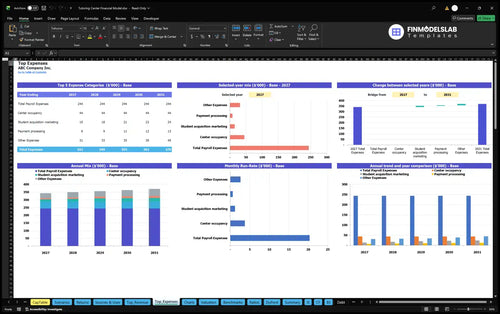
Largest costs and spending trends.
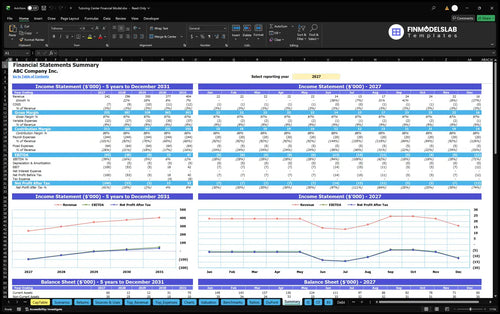
Annual and monthly financial performance.
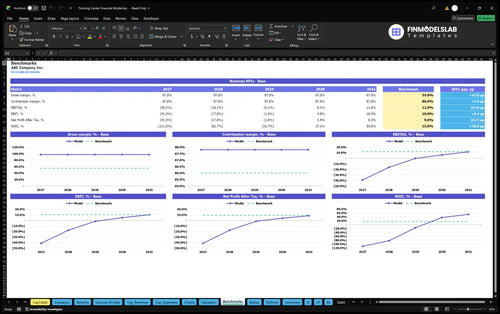
Compare margins and returns to benchmarks.

This template helped me map cash flow month by month, so I could spot a shortfall before it became a problem. I cut two hours of guesswork and walked into my lender call with a clearer funding plan.

I was stuck staring at an empty spreadsheet, and this gave me a clean place to start. The structure saved me about a day of setup time and made the first forecast much easier to build.
I am not strong in advanced Excel, so having the formulas and tabs already laid out mattered a lot. I built the model without outside help and finished my first draft in under three hours.