

Revenue & Calc
Set qualified leads, close rates, vehicle mix, selling prices, and seasonality. Calc applies launch timing to forecast monthly sales by category.


The Used Car Dealership Financial Model is an Excel template projecting retail vehicle sales, costs, staffing, and funding. Monthly revenue follows qualified buyer leads, close rates, vehicle mix, and realized selling prices.
The illustrated 2026–2030 case is a leased suburban Dallas, Texas, lot selling mostly mass-market vehicles with some premium cars. Financing is arranged through third parties, repairs are outsourced, and its editable assumptions are not industry averages.
Connected operating inputs, financial statements, and decision reports link dealership activity to projected results.
Set qualified leads, close rates, vehicle mix, selling prices, and seasonality. Calc applies launch timing to forecast monthly sales by category.
Plan vehicle purchases, reconditioning, selling costs, lot overhead, and role-based salaries without duplicating sales incentives.
CAPEX schedules asset purchases and depreciation; CapTable records equity; Debt models separately entered financing; Sources & Uses tracks cash allocation.
Review projected income, cash flow, balance sheet, Dashboard scenarios, investment returns, valuation, and model checks.
One demand-based sales pool is calculated from qualified buyer leads, conversion rates, and a repeating monthly seasonal profile.
The 2026 case starts with 150 monthly qualified leads and 12% conversion, before seasonality. In 2030, those inputs reach 260 leads and 16%; neither staffing nor stock creates a second sales cap.
Sales mix covers compact/midsize cars (25%), SUVs (35%), pickups (22%), minivans (10%), and premium cars (8% residual). Category-level realized prices exclude pass-through taxes and registration fees.
The Revenue Forecast organizes qualified leads, conversion, vehicle-class allocations, and realized prices. Its monthly calculations turn one projected vehicle pool into sales by class, allowing users to test demand or pricing changes without creating duplicate sales.
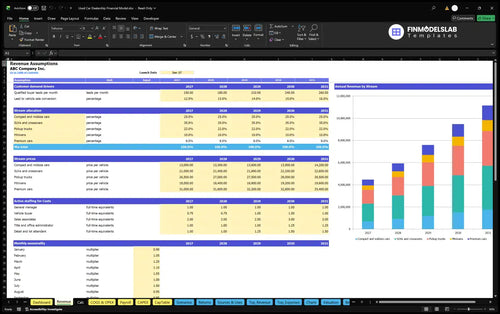
150 leads/month × 12% conversion × 12.0 summed monthly seasonal factors = 216 modeled vehicles; 216 × $20,710 weighted realized price = $4,473,360 annual revenue.
Vehicle purchases and reconditioning dominate direct costs, while lot overhead and fixed role-based pay complete the operating expense forecast.
Direct COGS equal 88.9% of revenue: 80% purchases, 2% parts, 4% outsourced repairs, 1.5% auction/transport, 0.5% warranty repairs, and 0.9% sales incentives.
Variable operating costs total 0.5%: payment fees (0.15%), vehicle history/deal services (0.15%), and concessions (0.2%). Fixed costs cover the lease, insurance, software, advertising, compliance, utilities, and upkeep.
The COGS and Operating Expenses forecast separates vehicle costs, variable selling costs, and scheduled overhead. Purchase prices, repairs, and premises costs flow through gross and operating margins.
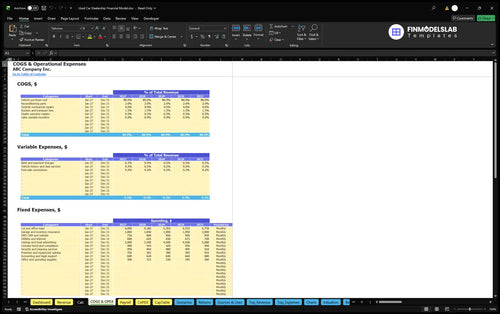
The lot and office lease starts at $6,000 monthly ($72,000 annually). Total fixed expense projections rise from $171,000 in 2026 to $213,600 in 2030.
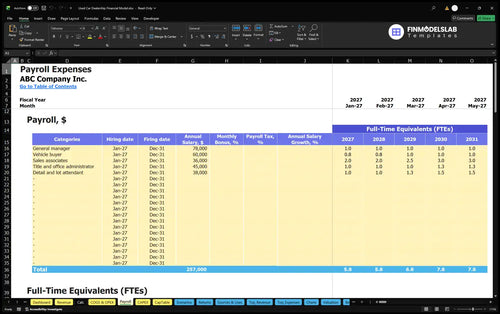
The Payroll Forecast models manager, buyer, sales, title/office, and lot attendant roles by FTE and salary. Fixed base payroll totals $278,000 in 2026; the 0.9% sales incentive is counted in COGS.
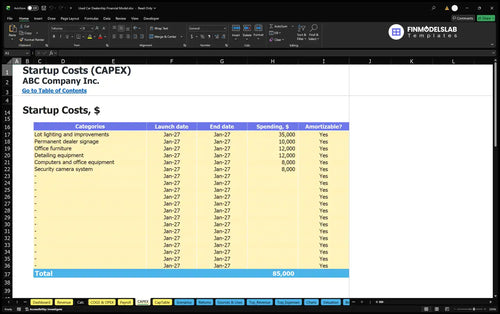
The opening budget separates long-lived assets, cash paid before launch, vehicle inventory needs, and an operating cash reserve.
Opening assets include $35,000 for lighting, $10,000 signage, $12,000 furniture, $12,000 detailing equipment, plus computers and cameras. Separate cash uses include permits, deposits, launch advertising, utility setup, and December 2025 preopening pay.
The model uses 41 inventory days, 3 receivable days, and 1 payable day. Funding covers qualifying assets, opening cash, launch-mix working capital, and a three-month cash operating reserve.
The Capital Expenditure Plan schedules purchases, dates, and depreciation. It separates site improvements and equipment from recurring vehicle costs and operating expenses.
The selected case starts with $1,704,296 in owner funding and no uncommitted borrowing. CapTable records equity; Dashboard debt controls allow alternative loan terms and repayments.
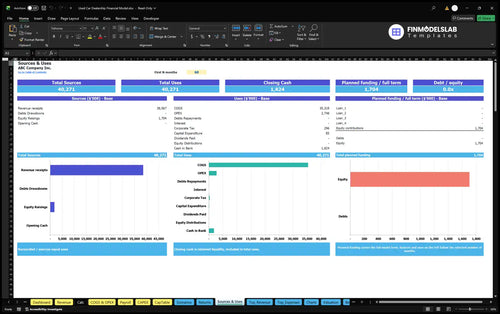
The Sources and Uses of Funds report compares equity and entered debt with operating cash movement, investments, and retained cash. Owner funding is capital, not sales revenue.
The documented Dallas-suburban example projects higher vehicle sales and operating EBITDA from 2026 to 2030, using the selected planning inputs.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $4,473,360 | $4,448,184 | $25,176 |
| 2027 | $5,931,338 | $5,762,177 | $169,162 |
| 2028 | $7,597,901 | $7,305,203 | $292,697 |
| 2029 | $9,481,968 | $9,038,989 | $442,979 |
| 2030 | $11,163,110 | $10,552,671 | $610,440 |
Selected-case projections only; values rounded to whole dollars, so displayed totals may differ slightly.
The 2026 case produces $4,473,360 revenue, $4,448,184 operating expenses, and $25,176 EBITDA. Higher leads, conversion, and prices lift the 2030 forecast to $11,163,110 revenue and $610,440 EBITDA.
Revenue less operating expenses gives EBITDA, not net profit. The Income Statement, Balance Sheet, and Cash Flow Statement separately reflect depreciation, financing, taxes, and working capital.
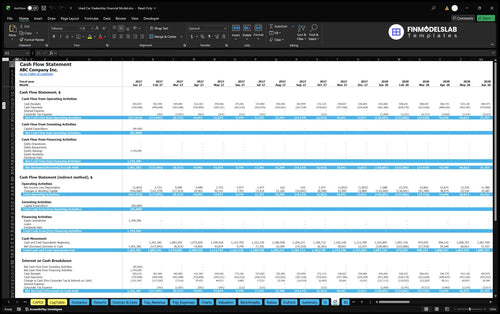
The Cash Flow Forecast separates operating receipts, investment spending, equity, and financing movements. Its opening-to-closing cash reconciliation addresses liquidity that EBITDA alone cannot establish.
The Returns and scenario reports help test whether operating performance and funding assumptions support an investment decision.
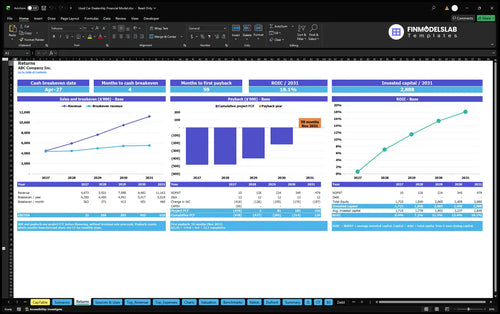
Sales break-even measures operating cost coverage; cash break-even concerns cash timing. Investment payback measures capital recovery, and annual ROIC compares returns with invested capital. Neither is EBITDA.
The Returns report examines sales break-even, cash break-even, payback, and ROIC using cash flow and invested capital. Positive EBITDA alone does not establish a payback date or return.
Dashboard Low/Base/High settings change revenue, cost, and payroll assumptions. Valuation offers DCF and sensitivity reports, but the example establishes no valuation, break-even date, or investment return.
This Excel template suits users evaluating an independent used-vehicle retailer under their own market, sourcing, and staffing assumptions.
Prospective owners can test lead generation and sales conversion; operators can analyze acquisition costs, repairs, overhead, and staffing. Inventory-day inputs connect merchandise planning to funding.
The Dallas-area assumptions are not national benchmarks. Cox Automotive and NIADA publications provide context, not verification of inputs marked Estimated; substitute your own operating evidence.
Answers to common questions about the template’s sales logic, financial statements, and editable assumptions.
Yes. Change annual qualified leads, sale conversion rates, monthly seasonal factors, vehicle shares, and realized prices to rebuild the single sales forecast.
No. Sales are demand-based in this case; inventory days instead affect working-capital planning.
No. Retail financing is arranged through third parties; buy-here-pay-here lending and financing income are outside the case scope.
The 0.9% variable sales incentive is part of COGS, while fixed base salaries are planned separately in Payroll.
Yes. The Cash Flow and Balance Sheet reports evaluate liquidity and financial position, but the provided illustrated numbers establish operating results only through EBITDA.
Yes. Dashboard debt controls support up to four financing facilities; the illustrated startup funding selection assumes owner equity and no uncommitted borrowing.
No. Payback, sales break-even, cash break-even, and annual ROIC are separate analyses using cash flow and invested capital.
No. The example is Dallas suburban in setting, but its selected numbers are planning estimates rather than verified local or national averages.
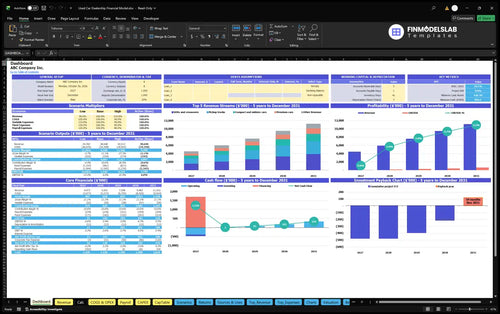
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
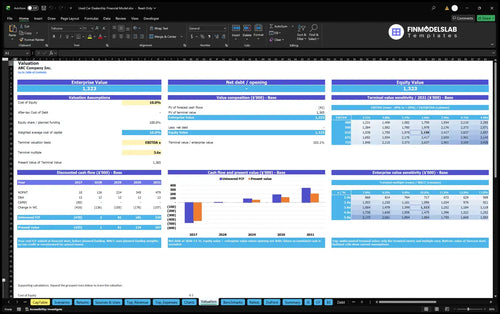
DCF valuation and sensitivity analysis.
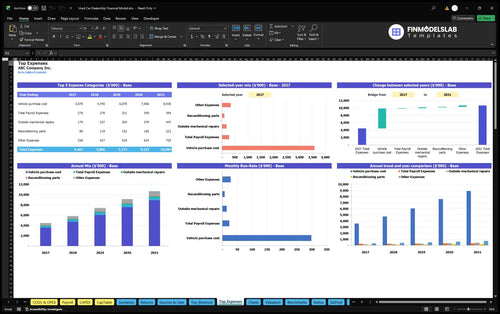
Largest costs and spending trends.
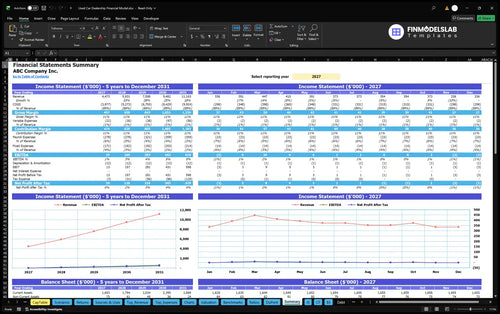
Annual and monthly financial performance.
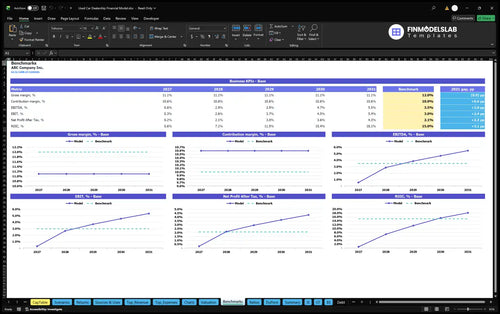
Compare margins and returns to benchmarks.

The pricing, cost, and growth tabs finally felt organized, so I could clean up my assumptions in under an hour instead of bouncing between messy sheets. It made the whole model much easier to review with my partner.
I could see cash needs and possible shortfalls much earlier, which saved me from guessing at monthly runway. That clarity helped me set a funding call with my lender before things got tight.
I’m not deep into Excel, and this template still made advanced modeling feel manageable. The layout and formulas were easy to follow, so I spent less time stuck and more time actually planning.