

Membership Revenue & Calc
Set billable members, dispatch frequency, box shares, and prices. Monthly calculations allocate one member pool into orders and sales.


The Wine Club Financial Model is an Excel template for a California-only online wine retailer. It converts paid members, quarterly shipments, five wine-box formats, and delivered prices into monthly sales and a five-year financial forecast.
The Sacramento-area example owns tax-paid wine inventory and outsources temperature-controlled storage and fulfillment. Its working owner is paid; production, importing, tasting rooms, wholesale, and out-of-state sales are excluded.
Editable commercial assumptions flow into expense schedules, projected statements, funding analysis, and management reports.
Set billable members, dispatch frequency, box shares, and prices. Monthly calculations allocate one member pool into orders and sales.
Budget wine, packaging, shipping, fulfillment, marketing, overhead, and staffing separately, including a paid owner and service coordinator.
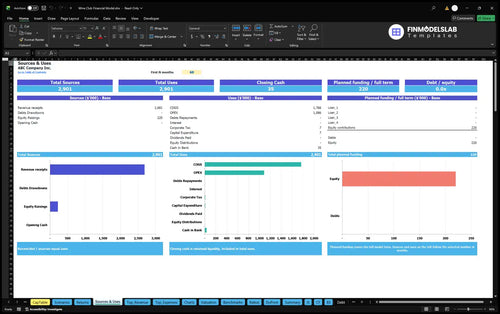
Enter startup assets, opening cash needs, equity, and optional debt. Sources & Uses traces planned funding.
Inspect monthly Income Statement, Cash Flow, Balance Sheet, and Summary reports. Checks flag reconciliation and input issues.
Dashboard, Scenarios, Returns, Valuation, Benchmarks, and trend analyses support different financial questions, not guaranteed outcomes.
Sales depend on billable members, four quarterly deliveries annually, and one allocation across five box formats.
The Base case grows average billable membership from 350 in 2026 to 1,350 in 2030. Staggered quarterly deliveries average one-third of a paid shipment monthly, not one monthly box per member.
Six-bottle red, white, and mixed boxes are priced at $129, $129, and $139. Twelve-bottle red and mixed boxes are $219 and $249; their respective order shares are 25%, 15%, 30%, 15%, and 15%, producing a $163.50 weighted shipment price.
The Revenue Forecast turns members, delivery frequency, box shares, and prices into projected orders and sales. Monthly Calc assigns each order once, preventing duplicated subscription revenue.
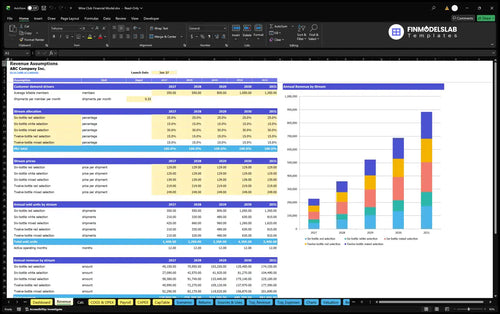
350 average members × 4 quarterly shipments × $163.50 weighted price = $228,900 in revenue.
Membership is net of churn and replacement, without separate cohorts or a capacity ceiling. All streams activate for the full January 2026 launch month; customers pay before dispatch.
COGS, variable spending, fixed overhead, and staffing affect EBITDA separately, without duplicate salaries.
Direct COGS equal 64% of sales: tax-paid wine 44%, packaging 3%, inbound freight 1.5%, picking and packing 3.5%, and outbound adult-signature delivery 12%. The resulting gross margin is 36%.
The COGS and Operating Expenses forecast separates wine and fulfillment costs from processing, platform fees, marketing, damage allowances, and overhead. Each category feeds operating margins.
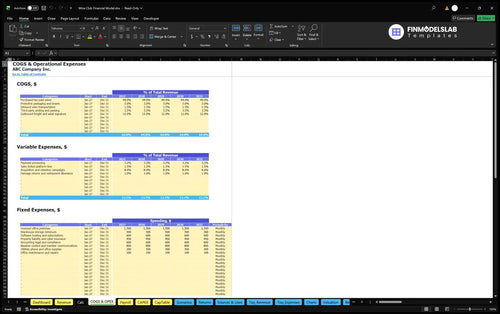
Variable costs equal 13.7% of sales: processing 3.2%, platform fees 1.5%, acquisition and retention 8%, and damage or reshipment 1%. Fixed overhead is $58,200 annually, including $1,500 monthly office rent.
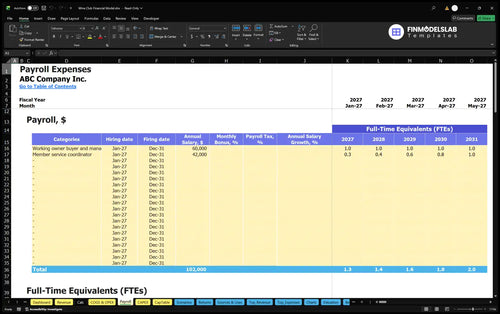
The Payroll Forecast includes a $60,000 salaried owner and a member coordinator increasing from 0.25 to 1.0 annual-average FTE. Combined base salaries grow from $70,500 in 2026 to $102,000 in 2030.
Owner funding covers opening assets, prelaunch costs, initial stock, and a policy reserve—not operating earnings.
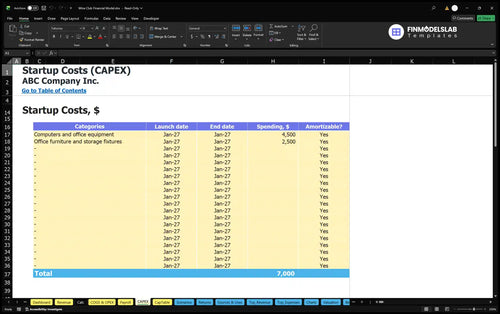
Startup assets include $4,500 of office equipment and $2,500 of furniture and fixtures. Separate cash needs include a lease deposit, licenses, website, prelaunch marketing, and preopening pay and premises.
The Capital Expenditure Plan schedules equipment and fixtures, purchase dates, and depreciation. These asset purchases differ from recurring wine purchases and EBITDA operating expenses.
Working capital assumes 33 inventory days, zero receivable days, and zero payable days. Those timings influence liquidity, while the supplied operating figures end at EBITDA.
The Sources and Uses of Funds report reconciles equity, entered debt, receipts, payments, and retained cash. It tracks funding allocation without equating EBITDA to cash.
The Base illustration retains three years of EBITDA losses before modest positive results in 2029 and 2030.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $228,900 | $306,555 | -$77,655 |
| 2027 | $359,700 | $414,487 | -$54,787 |
| 2028 | $523,200 | $549,926 | -$26,726 |
| 2029 | $686,700 | $685,366 | $1,334 |
| 2030 | $882,900 | $846,213 | $36,687 |
Projections are illustrative, not historical performance or industry averages. Rounding may create small apparent differences.
Membership growth raises revenue with fixed base prices and mix. The projected 2030 EBITDA of $36,687 is neither net income nor evidence of cash coverage or investor return.
The Projected Income Statement carries revenue, direct costs, operating expenses, and payroll into EBITDA, then depreciation, interest, tax, and net profit. The supplied example provides no net-profit figures.
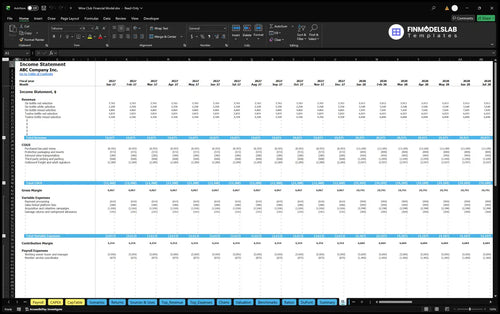
Dashboard and Summary connect these results with broader statements. Check inventory, working-capital timing, capital spending, equity, and debt before assessing cash.
The Cash Flow Forecast tracks operating, investing, and financing movements and reconciles cash balances. It exposes timing gaps from prepaid memberships, inventory, and opening costs missed by EBITDA.
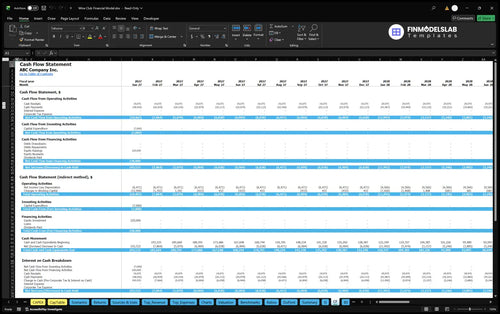
Returns and scenario results depend on entered cash flows, funding, and operating assumptions.
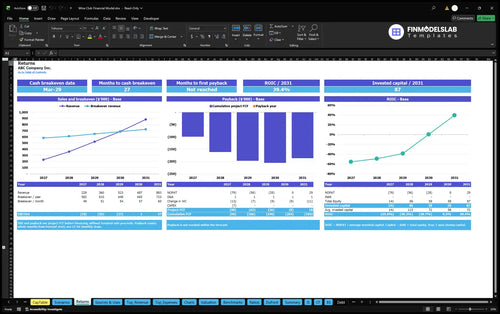
Returns distinguishes sales break-even, cash break-even, investment payback, and annual ROIC. Positive 2029 EBITDA does not establish any of those outcomes.
The Break-Even, Payback and ROIC analysis compares required sales, cumulative project cash flows, and investment recovery. Payback timing and annual ROIC depend on actual modeled financing and cash assumptions.
Dashboard Low, Base, and High multipliers adjust sales and cost categories. Four optional debt facilities feed repayment schedules; Valuation and Benchmarks compare assumptions without establishing verified investment results.
For California-only retailers, the template compares membership growth, box economics, staffing, and funding options.
Edit member volume, delivery frequency, box mix, prices, costs, staffing FTE, equipment, and financing. The retailer owns inventory and books gross sales rather than commissions.
This forecast does not validate shipping licenses, demand, taxes, or investment returns. Its Base assumptions are estimates, not verified California industry averages.
These answers clarify the shipment method, input flexibility, operating losses, funding assumptions, and reporting scope.
No. It converts staggered quarterly deliveries into about one-third of a paid order per average member per month.
Yes. The forecast uses annual average billable members and five mutually exclusive box shares, which should sum to 100%.
No. The annual average member input is already net of expected churn and replacement; no separate cohort schedule is assumed.
Yes. Purchased wine, packaging, inbound and outbound freight, and third-party picking and packing are separate direct-cost inputs.
In the illustrative case, growing gross and contribution profit does not yet cover annual fixed overhead and paid personnel costs.
No. It is an estimated opening funding amount with a policy reserve, not a validated peak funding requirement through operating losses.
Yes. It includes Cash Flow and Balance Sheet reports, but the provided case amounts support only the operating forecast through EBITDA.
Yes. Dashboard scenario multipliers and the Scenarios report compare Low, Base, and High operating cases without guaranteeing financial outcomes.
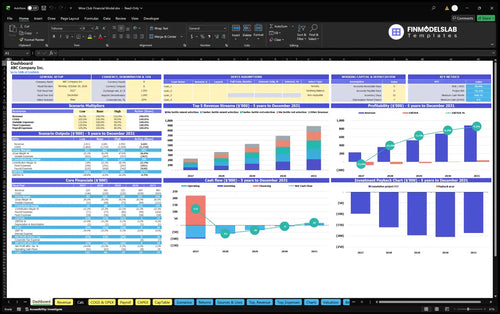
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
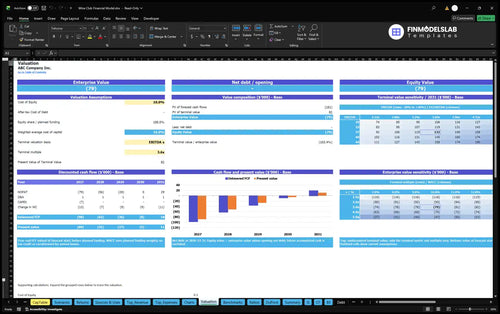
DCF valuation and sensitivity analysis.
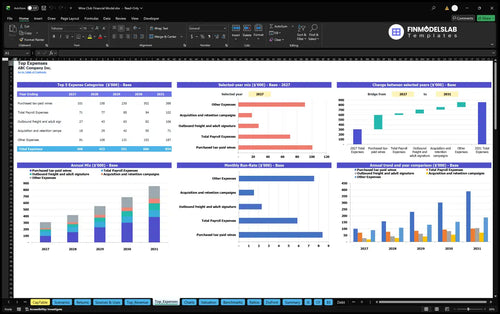
Largest costs and spending trends.
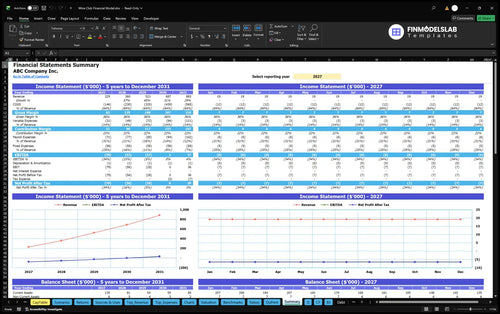
Annual and monthly financial performance.
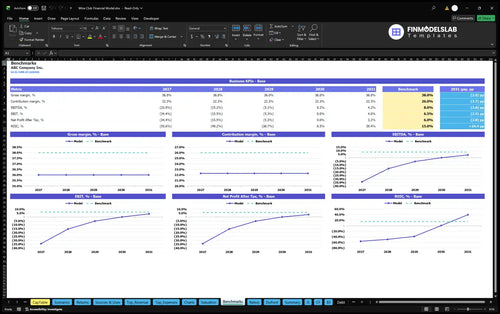
Compare margins and returns to benchmarks.

This template kept one broken formula from turning into a bigger mess. I found the inputs, checked the outputs, and had a clean model ready for a lender call in under an hour.
I stopped hunting through separate files for the P&L, cash flow, and charts. Everything was in one place, so I could send a clean update to my partner without spending half a day pulling numbers together.
I’m not strong in Excel, but the layout made the model easy to follow. I filled in the assumptions and had a five-year forecast ready for a planning meeting without calling in outside help.