A stabilized U.S. banquet hall can realistically leave an active owner about $150,000 to $200,000 a year in spendable business cash; this base case produces $174,240 after modeled tax and reinvestment reserves. It assumes $1.44 million of annual revenue, about eight mixed events per month at $15,000 each. Food and beverage inputs, payroll, property overhead, marketing, and debt are the main constraints. This is not guaranteed salary or passive income and excludes personal tax true-ups and unplanned capital projects.
How much can a banquet hall owner make after expenses?
Owner income depends on sold dates, event value, and whether the owner replaces a paid manager. This model covers an independent, leased U.S. banquet hall with in-house event management and meaningful food-and-beverage sales. The Knot reported the 2025 average wedding venue spend at $12,900. That figure anchors consumer spend, not banquet-hall profit.
At $120,000 of monthly revenue and a 70% gross margin, the base case has $84,000 of gross profit. Subtract $32,000 of payroll, $18,000 of fixed overhead, $5,000 of marketing, and $7,000 of debt service: pre-reserve profit is $22,000. Tax and reinvestment reserves total $7,480, leaving $14,520 monthly, or $174,240 annually, as owner income.
Owner income$174KNet margin12%Revenue for target pay$1.37MBusiness difficultyHard
What does this owner-income calculator assume?
The calculator keeps payroll separate from direct event costs. Its 70% base gross margin means 30% of sales goes to food, beverage, supplies, processing, and other non-labor direct costs. The National Restaurant Association reported 32.0% median food and non-alcohol beverage cost for full-service restaurants in 2024. Because venue fees and some rentals carry lower material cost, 70% is a blended planning assumption, not a banquet-hall benchmark.
The base case is owner-operated, so owner pay is not included in the $32,000 payroll line. The calculator treats owner income as residual cash after operating costs and reserves. A formal owner salary should instead be moved into labor so it is not counted again as a distribution; the tax reserve is only a cash-planning holdback, not a tax-rate forecast.
Owner income calculator
Adjust revenue, margin, staffing, overhead, financing, and reserves to estimate monthly owner take-home and the target-pay gap.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives banquet hall owner income most?
The strongest levers are sold dates, revenue per event, gross margin, staffing, facility and financing burden, and the booking pipeline. The National Restaurant Association reported full-service restaurant labor at 36.5% of sales in 2024. Banquet halls can schedule more labor around events, but setup, service, kitchen, bar, and cleanup hours still have to follow confirmed headcount.
1
Calendar utilization
5.4-12 events/mo
Moving from the low case to the base case spreads occupancy and management costs across roughly three more revenue-producing dates each month.
2
Revenue per event
$12K-$17.5K
Venue fees, guest count, catering, bar, rentals, A/V, and premium-date pricing determine how much each booked date contributes before payroll and overhead.
3
Gross margin
66%-73%
Food, beverage, supplies, processing, and direct vendor costs can erase pricing gains unless package-level contribution is tracked before labor.
4
Labor efficiency
$26K-$48K/mo
Event staffing must rise with volume, but owner cash improves only when payroll grows slower than gross profit and owner work is valued separately.
5
Facility + debt load
$24K-$31K/mo
Fixed overhead plus debt service is due whether or not a Saturday sells, creating a hard revenue floor before the owner sees distributable cash.
6
Booking pipeline + reserves
32%-37% held back
Marketing must turn into signed dates and deposits, while tax and reinvestment reserves keep apparent profit from becoming an unsafe owner draw.
Want to test these banquet hall assumptions in a full forecast?
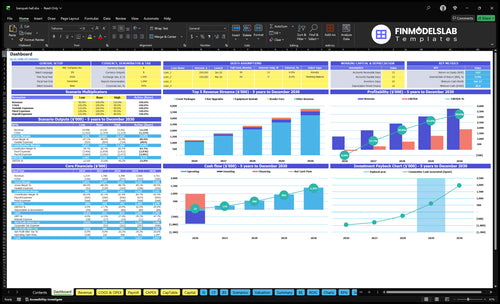
The Banquet Hall Five-Year Financial Model Template shows revenue, costs, scenarios, cash flow, and operating metrics. Use the dashboard to test event volume, package value, gross margin, staffing, debt, and reserves before setting owner distributions.
How many events does a banquet hall need to support owner pay?
With this cost structure, about six $15,000 events per month cover operating costs before reserves, while about 7.6 events support the $12,000 monthly target owner pay after reserves. The base case uses eight. The Knot reports that venues for weddings with 101 or more guests averaged $16,000 in 2025, making a $15,000 blended ticket plausible as a planning case, but local quotes should replace it before financing a site.
Base event math
8 events × $15,000 = $120,000 monthly revenue.
70% gross margin = $84,000 gross profit.
$62,000 monthly operating costs come before owner reserves.
$14,520 remains for owner income after the modeled reserves.
Break-even watch
Operating break-even is about $88,600 of monthly sales.
At a $15,000 event value, that is just under six events.
The target-pay formula lifts the need to about $114,500 a month.
Discounted dates only help if the contribution margin stays positive.
Booked revenue is not cash safe to spend. Deposits can arrive months before events while food, payroll, refunds, and final vendor payments occur later. Using those deposits for owner draws can create a working-capital squeeze even when the forward calendar looks strong.
How much does staffing change owner distributions?
Staffing can move owner income sharply because halls need both year-round selling and event-day execution. BLS reports 2024 median annual wages of $59,440 for event planners and $65,310 for food service managers, before payroll taxes, benefits, overtime, and local wage premiums.
Owner-operated case
The owner leads management, major sales, and operating oversight.
Owner compensation is the residual calculator output, not payroll.
Base employee payroll is $32,000 per month before owner pay.
Owner hours should still be tracked so labor is not mistaken for passive return.
Manager-run case
Adding roughly $7,000 a month of replacement management payroll lowers residual cash materially.
At the base reserve rates, a $7,000 operating-cost increase cuts owner income by roughly $4,620 a month while profit remains positive.
Annual owner cash would fall by about $55,000 unless revenue or margin rises.
Passive ownership therefore requires a different income target than owner-operated work.
Owner salary and owner distribution should stay separate. Salary pays for work performed; a distribution is residual cash after operating, financing, tax, and reinvestment needs. EBITDA sits earlier in the bridge and can overstate cash safe to distribute because debt principal, taxes, and capital needs come later.
How do seasonality, deposits, and debt affect owner cash?
A banquet hall can be profitable on paper yet cash-tight because sales are seasonal while property costs continue. The National Restaurant Association reported full-service restaurant occupancy costs at 5.7% of sales in 2024. A banquet hall is often more space-intensive, so this model uses a broader $18,000 monthly fixed-overhead allowance instead of applying that adjacent restaurant ratio directly.
Cash timing discipline
A 35% booking deposit is a planning policy, not an industry benchmark.
Track deposits by event date so advance cash is not mistaken for completed-event profit.
Keep a rolling 13-week cash forecast through peak and off-season months.
Reserve for refunds, repairs, insurance renewals, and supplier deposits before distributions.
Financing pressure
Base debt service is $7,000 per month and is separate from rent and overhead.
SBA says 7(a) loans may finance real estate improvements, equipment, working capital, and other eligible business needs.
Actual rates and payments are negotiated with lenders and must fit repayment capacity.
Debt principal reduces cash even when accounting profit looks healthy.
The reconciled base case produces $174,240 of annual owner income after modeled reserves on $1.44 million of sales.
About eight $15,000 events per month supports the base target; fewer than six events pushes the venue near operating break-even.
Owner-operated income includes the economic value of management work, while passive ownership requires extra payroll and usually lower distributions.
Debt service, tax reserves, reinvestment, deposits tied to future events, and property costs must be covered before cash is truly safe to distribute.
What do low, base, and high owner-income scenarios look like?
All three cases change revenue and costs together. The low case keeps minimum facility and debt costs despite weaker demand; the high case adds labor, overhead, marketing, debt, and a larger reinvestment reserve. These are researched planning assumptions, so local competitor quotes, actual capacity, signed pipeline data, and financing terms should replace them in a site-specific forecast.
Owner income scenarios
Low, base, and high cases reconcile bookings, blended event value, gross margin, labor, fixed costs, marketing, debt, and reserves.
Banquet Hall low, base, and high owner-income planning cases
Scenario factor
Low CaseDownside
Base CasePlanning case
High CaseUpside
Launch modelCalendar and demand posture
Slower ramp; about 5.4 events per month; protect cash before owner draws.
Steady owner-operated venue; about 8 events per month; mixed wedding and social calendar.
Strong demand; about 12 events per month; added weekday, corporate, and premium-date volume.
Typical setupRevenue and margin
$65,000 monthly revenue; 66% gross margin; about $12,000 blended revenue per event.
$120,000 monthly revenue; 70% gross margin; about $15,000 blended revenue per event.
$210,000 monthly revenue; 73% gross margin; about $17,500 blended revenue per event.
Cost driversMonthly operating load
Labor $26,000
Fixed overhead $17,000
Marketing $3,000
Debt $7,000
Reserves 32%
Labor $32,000
Fixed overhead $18,000
Marketing $5,000
Debt $7,000
Reserves 34%
Labor $48,000
Fixed overhead $22,000
Marketing $7,000
Debt $9,000
Reserves 37%
Owner income rangeAfter modeled tax and reinvestment reserves
$0
$174,240
$508,788
Best fitHow to use the case
Use to test a soft calendar where minimum facility and debt costs prevent owner distributions.
Use for a stabilized owner-operated venue with normal staffing, local pricing discipline, and a balanced event mix.
Use to test strong utilization with added staffing and reinvestment rather than assuming all incremental revenue becomes profit.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Six Banquet Hall Income Drivers to Track
These six drivers expand the same levers shown above: event count, ticket, gross margin, labor, fixed cash burden, and booking pipeline. Tracking them together explains why owner cash rises or falls before a distribution is made.
1. Calendar utilization
Sell enough dates to spread the room cost
An empty date earns nothing while rent, insurance, utilities, software, coordination, and loan payments continue. The model sells about 65 events a year in the low case, 96 in base, and 144 in high. BLS notes that planners serve weddings, corporate meetings, galas, conventions, and other events, and the occupation is projected to grow 5% from 2024 to 2034. Weekday corporate and nonprofit events can therefore reduce dependence on peak Saturdays.
At a $15,000 ticket and 70% gross margin, one extra event creates about $10,500 of gross profit. If it needs $3,000 of incremental payroll and support, about $7,500 remains before reserves. Two well-priced incremental dates can materially improve monthly owner cash; two deeply discounted dates may only add work.
Track sellable dates and revenue per available date
Separate Saturdays, Fridays, Sundays, and weekdays because their demand and price ceilings differ.
Booked events by month and day type.
Revenue per available event date.
Lead-to-tour and tour-to-contract conversion.
Cancellation and reschedule rate.
Base distributions on normalized occupancy, not one peak month; strong fall cash may need to carry the venue through a soft winter calendar.
2. Revenue per event
Price the date, guest count, and add-ons separately
The Knot reported a $12,900 national average wedding venue spend for 2025, with higher spending for larger guest counts. It also found that 74% of surveyed reception venues included rentals, 41% catering, and 37% alcohol. Package scope therefore matters as much as the room fee.
The model uses $12,000 per event in low, $15,000 in base, and $17,500 in high. At eight base events, a $1,000 increase in average event value adds $8,000 of monthly revenue and, at a 70% gross margin, $5,600 of gross profit before extra payroll or marketing. Track whether that lift comes from price, guests, bar, rentals, ceremony fees, A/V, or overtime because margins differ.
Track contribution by package, not just total sales
A premium package that adds low-margin food and heavy labor may increase revenue faster than owner income.
Average contracted revenue per event.
Venue fee versus food, beverage, rental, and service mix.
Revenue per guest and minimum spend by date.
Add-on attach rate and gross profit dollars.
Use date minimums by demand. A premium Saturday should carry more contribution than an easy-setup Wednesday corporate meeting.
3. Gross margin and direct event cost
Protect the spread before payroll is scheduled
The base gross margin is 70% after non-labor direct event costs; all payroll stays in the labor input. The National Restaurant Association found a 32.0% median 2024 food-cost ratio for full-service restaurants, while locations above $2 million in annual sales reported a lower 31.0% median food-cost ratio. These are adjacent food-service benchmarks, not banquet-hall targets.
If gross margin falls from 70% to 67% on $120,000 of monthly revenue, gross profit drops $3,600. With costs unchanged, pre-reserve profit falls from $22,000 to $18,400; after the 34% reserve rate, owner income falls about $2,376 a month, or $28,500 a year.
Cost every package before it is sold
Build a simple event contribution sheet that follows the contract from quote through final invoice.
Food and beverage cost by menu and guest.
Rental, linen, décor, and disposables cost.
Merchant fees and outside-vendor pass-throughs.
Gross profit dollars by event type.
Keep payroll out of gross margin when it is already in labor cost; otherwise staff is double-counted and owner income is understated.
4. Labor efficiency and owner role
Match staffing to headcount without treating owner labor as free
Banquet halls need coordination, kitchen leadership where food is in-house, service, bar, setup, cleaning, sales, and administration. BLS lists a 2024 median wage of $59,440 for meeting, convention, and event planners. The base case uses $384,000 of annual employee labor before owner pay, with the owner covering management.
Replacing the owner with a manager costing about $7,000 monthly including payroll burden raises operating costs to $69,000. With other base inputs unchanged, owner income falls to about $9,900 a month, or $118,800 annually—roughly $55,400 below the owner-operated case. That difference largely compensates the owner for management work, not passive capital.
Track labor per event and owner hours
Monthly payroll percentage alone can hide a badly staffed banquet or an owner working unsustainably long weeks.
Paid labor dollars per event and per guest.
Setup, service, kitchen, bar, and teardown hours.
Owner hours by sales, admin, and event operations.
Overtime and agency staffing frequency.
The high case raises monthly labor to $48,000 as revenue reaches $210,000; growth is not modeled with a frozen team.
5. Facility and debt load
Know the monthly cash floor before signing the site
The base model carries $18,000 of fixed overhead plus $7,000 of debt service each month, a $25,000 cash floor before payroll and marketing. Overhead includes occupancy, utilities, insurance, routine cleaning, software, repairs, permits, accounting, and administration; debt is separate. The SBA says 7(a) financing can support eligible improvements, equipment, and working capital, but repayment capacity still governs affordability.
Every $1,000 reduction in recurring overhead adds $1,000 to pre-reserve profit. At the 34% base reserve rate, about $660 reaches owner income monthly, or $7,920 annually. A higher rent, insurance premium, or loan payment therefore needs enough extra event contribution to justify it.
Track fixed cash burden as a monthly hurdle
Evaluate the site on cash coverage, not only on rent per square foot.
Fixed overhead dollars and percentage of sales.
Debt-service coverage from normalized operations.
Utilities and insurance by season.
Capital replacement schedule for kitchen, HVAC, A/V, furniture, and finishes.
Compare rent and build-out debt together; a cheap lease can become expensive after financing the space.
6. Booking pipeline, deposits, and reserve discipline
Convert leads early without spending future-event cash twice
Marketing rises from $3,000 to $7,000 monthly across the scenarios. At the $5,000 base spend and eight signed events, simple marketing cost per booking is $625 before sales payroll. If the same spend yields only four bookings, it doubles to $1,250 while the calendar stays underfilled. Track qualified leads, tours, contracts, referrals, and planner relationships rather than traffic alone.
A 35% deposit on a $15,000 event is $5,250, so ten future bookings can place $52,500 in the bank before their food, labor, refunds, and event obligations are settled. The IRS explains that many business owners make estimated tax payments during the year. Forecast deposits by event date and distribute cash only after debt, tax reserves, reinvestment, and known commitments remain funded.
Track booked gross profit and unrestricted cash
Separate sales success from liquidity so a busy future calendar does not create an aggressive current draw.
Marketing cost per qualified lead, tour, and signed event.
Booked gross profit by event month.
Deposit cash tied to future obligations.
Tax reserve, reinvestment reserve, and 13-week cash floor.
Safe owner cash is the last line: earn revenue, pay direct costs, payroll, property, marketing, lenders, and reserves, then distribute only the residual.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Banquet Hall Bundle
Choosing a selection results in a full page refresh.