

Revenue & Calc
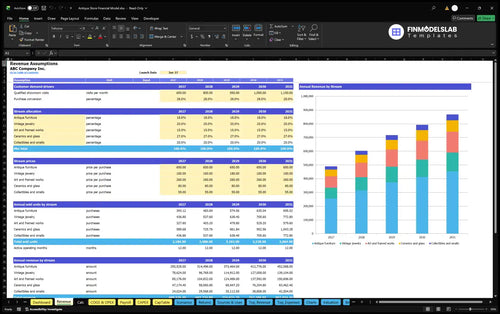
Edit showroom visits, basket conversion, category allocation, realized prices, and launch timing; review the resulting monthly and annual sales forecast.


This Antique Store Financial Model is an Excel planning template for an independent, owned-inventory antique and vintage retailer. It converts showroom traffic, purchase conversion, five merchandise allocations, selling prices, and operating expenses into monthly financial projections and management reports.
The included example represents one leased, 1,500-square-foot showroom in Columbus, Ohio, launching January 31, 2026. Its 2026–2030 figures are hypothetical planning assumptions, not actual store results, market averages, or a forecast for every buyer.
The workbook connects store-specific assumptions to operating calculations, financing schedules, financial statements, and decision reports.
Edit showroom visits, basket conversion, category allocation, realized prices, and launch timing; review the resulting monthly and annual sales forecast.
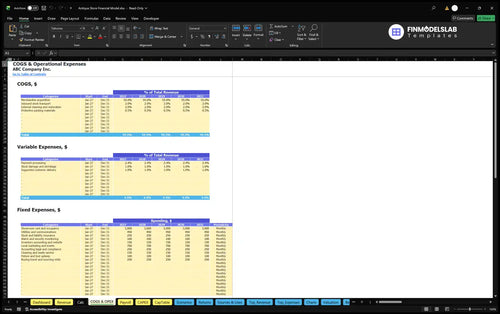
Separate merchandise purchase and handling costs from payment processing, shrinkage, supported delivery, and recurring showroom overhead.
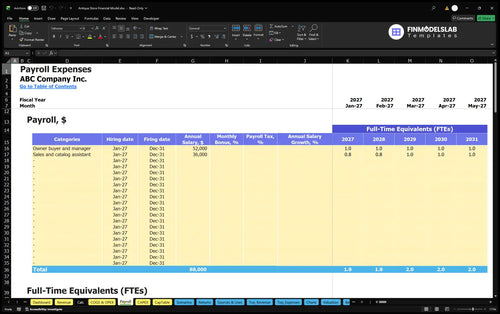
Plan the owner-manager and sales assistant by full-time-equivalent staffing, while tracking fitout, display, point-of-sale, and equipment investments.
Set the reporting case, working-capital days, Low/Base/High multipliers, and optional debt facility assumptions in one management area.
Review Income Statement, Cash Flow, Balance Sheet, Summary, Returns, Valuation, benchmarks, ratios, and reconciliation checks without assuming any unprovided example values.
Monthly sales are driven by qualified visits multiplied by the purchase conversion rate, with each paid basket assigned to exactly one merchandise group.
The illustrative plan uses 650 showroom visits per month in 2026, increasing to 1,150 by 2030, and a constant 28% purchase conversion. This creates one shared pool of purchases rather than five independent customer counts.
The five allocated groups are antique furniture, vintage jewelry, art and framed works, ceramics and glass, and collectibles and smalls. The model applies a realized selling price to the basket share in each group; the last allocation is residual.
The Revenue Forecast links showroom visits, purchase conversion, category shares, and average sale prices to annual merchandise revenue. The Calc worksheet distributes those inputs across forecast months and applies the store launch date.
| Merchandise category | Basket share | Price per sale |
|---|---|---|
| Antique furniture | 18% | $650 |
| Vintage jewelry | 20% | $180 |
| Art and framed works | 15% | $260 |
| Ceramics and glass | 27% | $80 |
| Collectibles and smalls | 20% | $55 |
The shares total 100% of one paid-basket demand pool; they are not separate visitor populations.
650 visits × 28% = 182 paid baskets; 182 × $224.60 weighted realized price ≈ $40,877 in monthly revenue.
The monthly example annualizes to approximately $490,526 in 2026 revenue. The chosen assumptions contain no material seasonality profile, and the forecast activates streams in the full launch month rather than using prelaunch sales.
Direct merchandise costs, sales-linked expenses, fixed monthly overhead, and role-based salaries each enter operating expenses once.
Estimated direct costs total 59.5% of revenue: acquisition 55%, inbound transport 2%, outside restoration 2%, and protective packing 0.5%. Variable expenses add payment processing 2.4%, damage and shrinkage 1%, and supported delivery 1%.
Fixed overhead includes rent, utilities, insurance, security, marketing, accounting, cleaning, and upkeep. The example budgets $64,800 annually in fixed expenses, including $3,000 monthly showroom rent and occupancy.
The COGS and Operating Expenses forecast separates acquisition and handling costs, sales-linked variable items, and scheduled fixed charges. It helps show how inventory economics and recurring showroom costs change contribution and EBITDA as sales vary.
| Expense category | 2026 | 2030 |
|---|---|---|
| Direct costs (COGS) | $291,863 | $516,373 |
| Variable expenses | $21,583 | $38,186 |
| Fixed overhead | $64,800 | $64,800 |
| Payroll | $79,000 | $88,000 |
These are illustrative forecast costs, rounded to whole dollars. Payroll is not counted inside COGS or variable expenses.
Payroll includes one full-time owner-buyer and manager at $52,000 annual base pay, plus a sales and catalog assistant at $36,000 per full-time equivalent. Assistant staffing is 0.75 FTE in 2026–2027 and 1.0 FTE from 2028.
The documented case excludes employer payroll taxes, benefits, and personal taxes. Operating EBITDA therefore reflects the stated scope rather than a claim about fully burdened wages or net income.
The Payroll Forecast schedules each position, compensation basis, and full-time-equivalent staffing level into monthly personnel costs. This makes the assistant staffing change visible without treating the owner’s salary or staff salaries as merchandise acquisition costs.
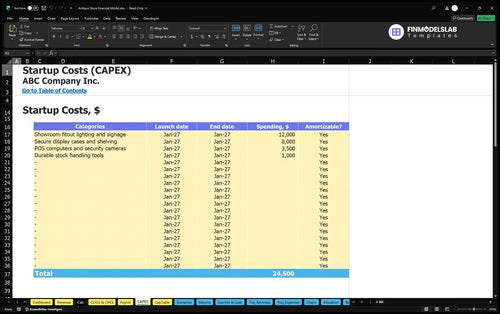
Store setup assets, preopening cash expenses, initial merchandise stock, and a planning reserve are distinct from recurring annual operations.
The hypothetical store includes $24,500 in startup assets for fitout, secure displays, point-of-sale and security equipment, and stock-handling tools. Another $17,000 covers separate prelaunch cash items such as deposits, registration, opening promotion, and preparation.
Working-capital controls use zero accounts-receivable days, zero accounts-payable days, and 168 inventory days. They reflect immediate customer payment, payment for stock before pickup, and a sizeable inventory holding assumption.
The Capital Expenditure Plan records fixture and equipment purchases, their spending dates, and applicable depreciation schedules. These capital investments are tracked separately from the revenue-based merchandise acquisition expenses and other operating charges.
| Funding use | Planned amount |
|---|---|
| Startup assets | $24,500 |
| Other preopening cash | $17,000 |
| Opening merchandise stock | $134,256 |
| Three-month recurring reserve | $114,312 |
Total estimated initial owner funding is $290,068 after rounding. Committed external funding in this example is zero.
The reserve equals a default three months of recurring expenses; it has not been proven sufficient for peak cash needs. The CapTable records equity contributions, while Dashboard debt inputs and the Debt sheet allow separate analysis of any financing assumptions a buyer enters.
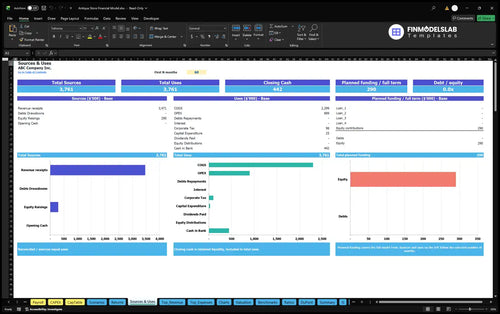
The Sources and Uses of Funds report organizes equity, potential borrowing, and business receipts against operating payments, capital spending, and retained cash. It supports a funding review without treating the illustrated opening reserve as a verified cash runway.
The documented base planning case projects growing showroom sales while showing all direct costs, variable expenses, fixed overhead, and Payroll through EBITDA.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $490,526 | $457,246 | $33,280 |
| 2027 | $603,725 | $529,580 | $74,145 |
| 2028 | $716,923 | $610,914 | $106,009 |
| 2029 | $792,389 | $659,136 | $133,252 |
| 2030 | $867,854 | $707,359 | $160,495 |
Hypothetical 2026–2030 forecast; original calculations use more precision than these whole-dollar display values.
In this example, EBITDA rises from $33,280 in 2026 to $160,495 in 2030 as monthly showroom visits increase and the sales mix and selling prices remain at their selected levels. The result is an operating forecast, not historical performance.
The workbook also includes an Income Statement, Balance Sheet, Cash Flow, Summary, charts, and consistency checks. Their functions are available for planning, but the example brief does not establish net profit, account balances, or a particular cash balance.
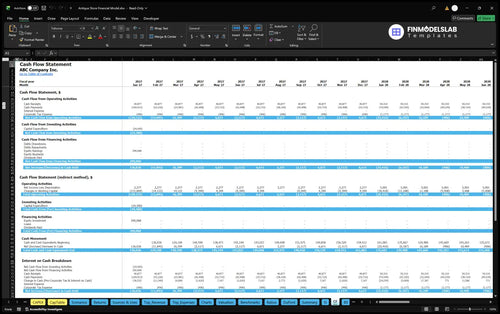
The Cash Flow Forecast separates operating, investing, and financing cash movements and reconciles opening to closing cash. It can expose funding needs from inventory, capital purchases, and repayment schedules that EBITDA alone does not show.
Returns and scenarios help test different business questions beyond the provided operating EBITDA forecast.
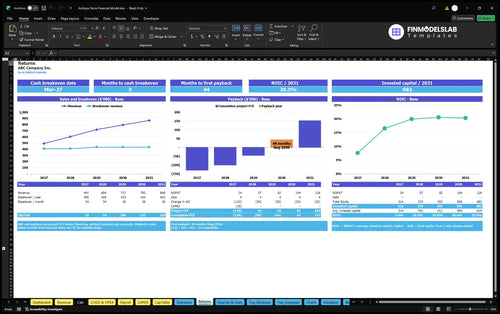
The Returns worksheet distinguishes sales break-even from cash break-even, tracks project cash flow toward investment payback, and evaluates annual return on invested capital. None of those measures can be read directly from the supplied EBITDA figures.
The Returns analysis displays break-even calculations, cash recovery and investment payback, and return on invested capital based on the relevant workbook schedules. It is designed for testing a store investment without asserting an unsupported payback date or ROIC.
The Dashboard provides Low, Base, and High multipliers for revenue, direct costs, variable expenses, fixed costs, and Payroll. Comparing those cases is useful when visits, selling prices, stock purchase economics, or occupancy costs depart from the example.
Valuation and benchmarks are separate workbook analyses. A DCF value depends on entered discount and terminal assumptions, while benchmark comparisons depend on user-selected references; neither establishes a verified market value or industry average.
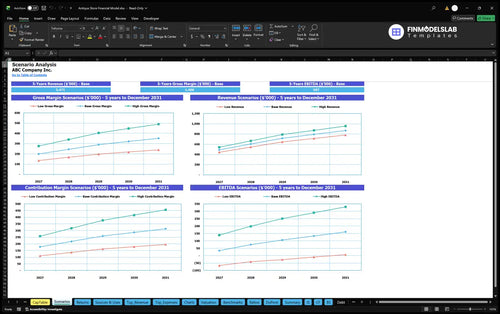
The Financial Scenario Analysis compares Low, Base, and High outcomes for revenue, gross margin, contribution margin, and EBITDA. It lets a store owner review sensitivity to changing assumptions without presenting any scenario as a guaranteed business result.
This workbook suits an owned-stock antique retail concept where one showroom sells merchandise directly to customers.
Use it to draft a new-store business plan, compare traffic and category pricing assumptions, plan opening inventory and fixtures, or discuss potential financing with an adviser. Replace the sample estimates with your actual lease, supplier terms, marketing plan, staffing, and sales assumptions.
The reference case does not model consignment commissions, dealer booth rental, or staff-constrained appointment capacity. Businesses with those mechanics should revise the revenue engine rather than reuse this example unchanged.
These answers clarify editable inputs, the example assumptions, and the distinction between operating projections and investment decisions.
Yes. Edit qualified showroom visits and conversion assumptions in Revenue; the model recalculates the paid-basket pool and merchandise sales.
No. Each modeled paid basket is allocated once across the five principal merchandise groups using shares totaling 100%.
Yes. Edit category realized prices and the relevant COGS assumptions to test different revenue and gross margin outcomes.
No. The sample represents store-owned inventory bought outright, not consignment sales or rented dealer booths.
No. They are hypothetical U.S.-dollar projections based on estimated inputs for a single Columbus showroom.
No. Owner and assistant base salaries flow through Payroll separately from COGS, variable expenses, and fixed overhead.
No. It includes a default three-month reserve, not a tested maximum cash requirement; use Cash Flow to evaluate liquidity.
Yes. Returns supports break-even, payback, and ROIC analysis, while Dashboard scenario controls compare Low, Base, and High assumptions.
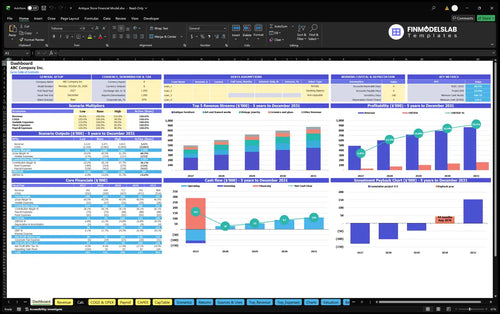
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
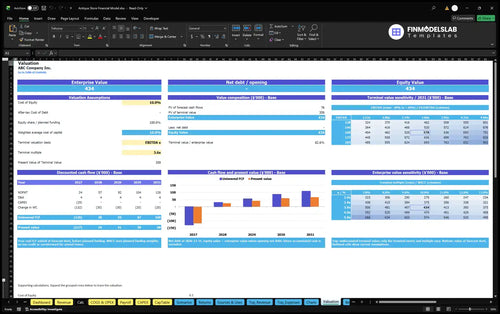
DCF valuation and sensitivity analysis.
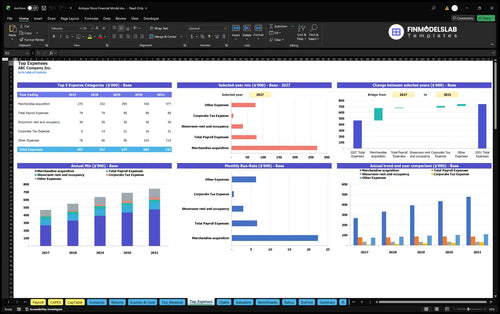
Largest costs and spending trends.
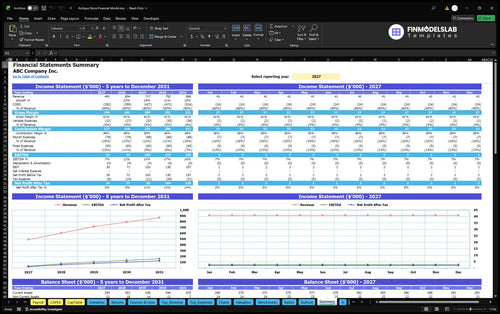
Annual and monthly financial performance.
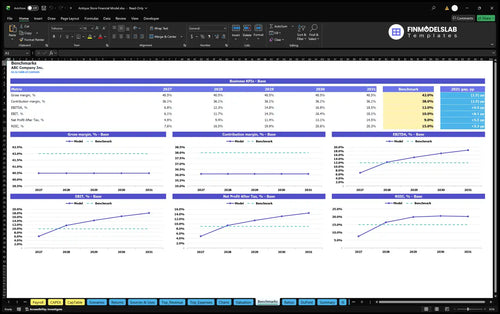
Compare margins and returns to benchmarks.

I stopped spending hours juggling low, base, and high cases by hand. The template made side-by-side scenario planning simple, and I had my financing discussion ready the same day.

Pricing, costs, and growth were all over the place before this. Now the assumptions sit in one model, so I could tighten the numbers in under an hour and finally explain them without losing the thread.
Our statements and charts used to live in separate files, which made every update a mess. This pulled everything into one place and saved me a full day before our lender meeting.